SoFi Could Be Building Something Wall Street Hasn’t Fully Priced In
SoFi just posted its sixth straight earnings beat and issued a 2027 outlook management called well ahead of estimates, yet the stock sits nearly 36% down for the year. Something about that gap deserves a closer look.


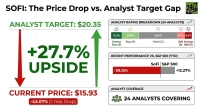
SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) just posted its 6th consecutive adjusted EPS beat. Management also issued a 2027 outlook it described as well ahead of analyst estimates. Shares trade near $16.80.
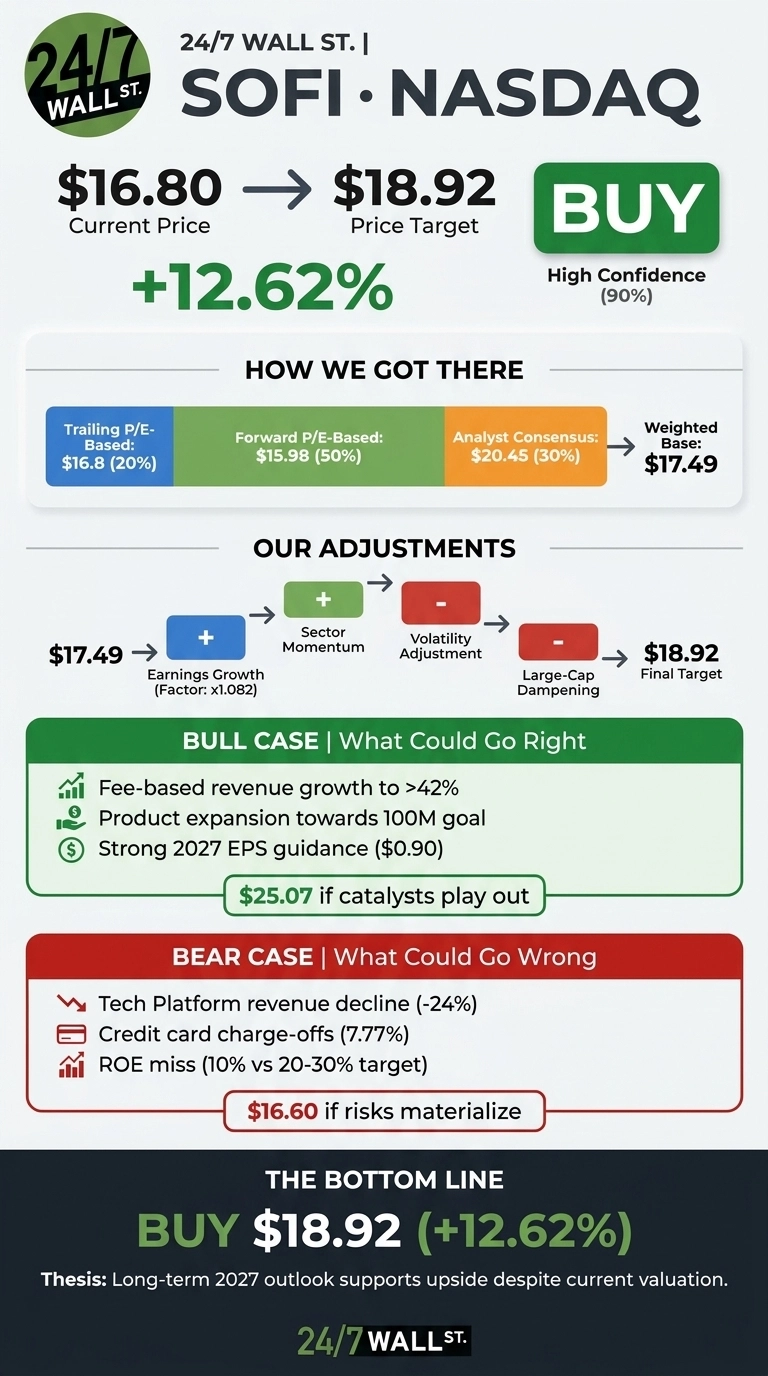
The 24/7 Wall St. price target for SoFi is $18.92 over the next 12 months, which means 12.62% upside. The stock earns a buy rating from the model, with a high confidence reading.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $16.80 |
| The Price Target from 24/7 Wall St. | $18.92 |
| Upside/Downside | 12.62% |
| Recommendation | BUY |
| Confidence Level | 90% |
Management now guides to $0.90 in 2027 adjusted EPS, yet the stock trades at roughly 21x forward earnings and is down 35.79% year to date.

Record Quarter Sparks a 16% Post-Earnings Rebound
SoFi reported on October 27, 2026. Adjusted EPS came in at $0.18 against a $0.1682 estimate, and revenue of $1.385B beat expectations of $1.26B. GAAP net income grew 72.89% to $240.99M. Loan originations hit a record $16.93B, and deposits rose $5.8B to $51.3B.

Shares climbed from $14.48 at filing to $16.825 a day later, a 16.17% gain. That puts the stock up 14.51% for the week and 1.39% for the month. It sits 48.64% below its 52-week high of $32.73.
Why Bulls See $25 Within Reach
In the bull case, the stock hits $25.07. The main driver is fee revenue. Fee-based revenue hits $570.63M, or 42% of the total, and management’s long-term goal is 50%. Interchange revenue rose 77%, and products per member climbed to 1.56 from 1.47.
The 2027 plan calls for $6.40B in revenue with “no capital raise assumed or needed.” Anthony Noto said that “it doesn’t take much imagination to see how that can drive 4X in earnings” on the path to 100 million products by 2030.
Among analysts, 4 rate the stock Strong Buy and 5 rate it Buy. The consensus target is $20.45.

Risks That Could Keep SoFi in the Teens
The bear case is $16.60. Technology Platform revenue fell 24%, though excluding a left client it grew 18%. The credit card charge-off rate of 7.77% needs monitoring. Return on tangible common equity was about 10%, well short of the 20% to 30% target.
Rate moves led to fair-value losses above $800 million, but hedge gains of roughly $734 million largely offset them. Analysts are split, with 12 Holds, 2 Sells, and 2 Strong Sells.

How SoFi Compares to Affirm and Happen
Affirm Holdings (NASDAQ:AFRM) is a direct consumer-credit rival with a market cap of $21.54B, close to SoFi’s $21.78B. Affirm trades at 11x trailing earnings, while SoFi trades at an implied 31x. I think much of SoFi’s premium is earned by its deposit funding, which covers about 90% of liabilities. Affirm relies on warehouse lines and securitizations instead.
Happen (NASDAQ:HAPN), formerly LendingClub, runs a similar deposit-funded consumer lending model. Its most recent net interest margin was 6.14%, the same as SoFi’s. However, Happen grew originations 29% to $3.15 billion, while SoFi grew them 71%.
Happen’s market cap is $1.65B, which shows the market already pays up for SoFi’s scale. Compared with these two peers, I see our target as reasonable.
| Company | Market Cap | Key Metric |
|---|---|---|
| SoFi | $21.78B | Originations +71% |
| Affirm | $21.54B | Revenue +32.64% |
| Happen | $1.65B | Originations +29% |
SoFi Price Prediction 2026-2030
The 24/7 Wall St. price target of $18.92 comes with a buy rating from our model and 90% confidence. SoFi’s earnings power grounds my view.
I would grow more constructive if fee revenue keeps rising toward half of the mix and credit holds steady. I would turn cautious if card charge-offs climb or Technology Platform growth stalls. On balance, I think the 2027 guidance offers more upside than the current price reflects.
The table below extends our model several years out. It assumes current growth trends and market conditions hold.
| Year | The Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $18.92 |
| 2027 | $20.34 |
| 2028 | $21.86 |
| 2029 | $23.49 |
| 2030 | $25.25 |
The estimates rest on SoFi continuing to execute on its cross-selling strategy. Faster progress toward 100 million products could push performance far beyond this path, while a credit downturn could pull them below it.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.