If You Invest $500 a Month in Nvidia Starting Now, This is What You’d Have in 2030
Nvidia sits at the heart of a $2 trillion cloud backlog, and a simple monthly contribution strategy could turn that tailwind into a dramatically different number by 2030. The spread between the best and worst case scenarios tells a very…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) sits at the center of the AI infrastructure buildout, and putting $500 a month into it starting now would ride four more years of that story. The stock trades at $224.64 as of September 23, 2026, up 20.73% year to date and 22.64% over the past year.
The engine’s nearest modeled horizon is the five-year target dated September 22, 2031, so any 2030 figure here is anchored to the modeled path and labeled illustrative.

Base Case Answer for a $500 Monthly Stake
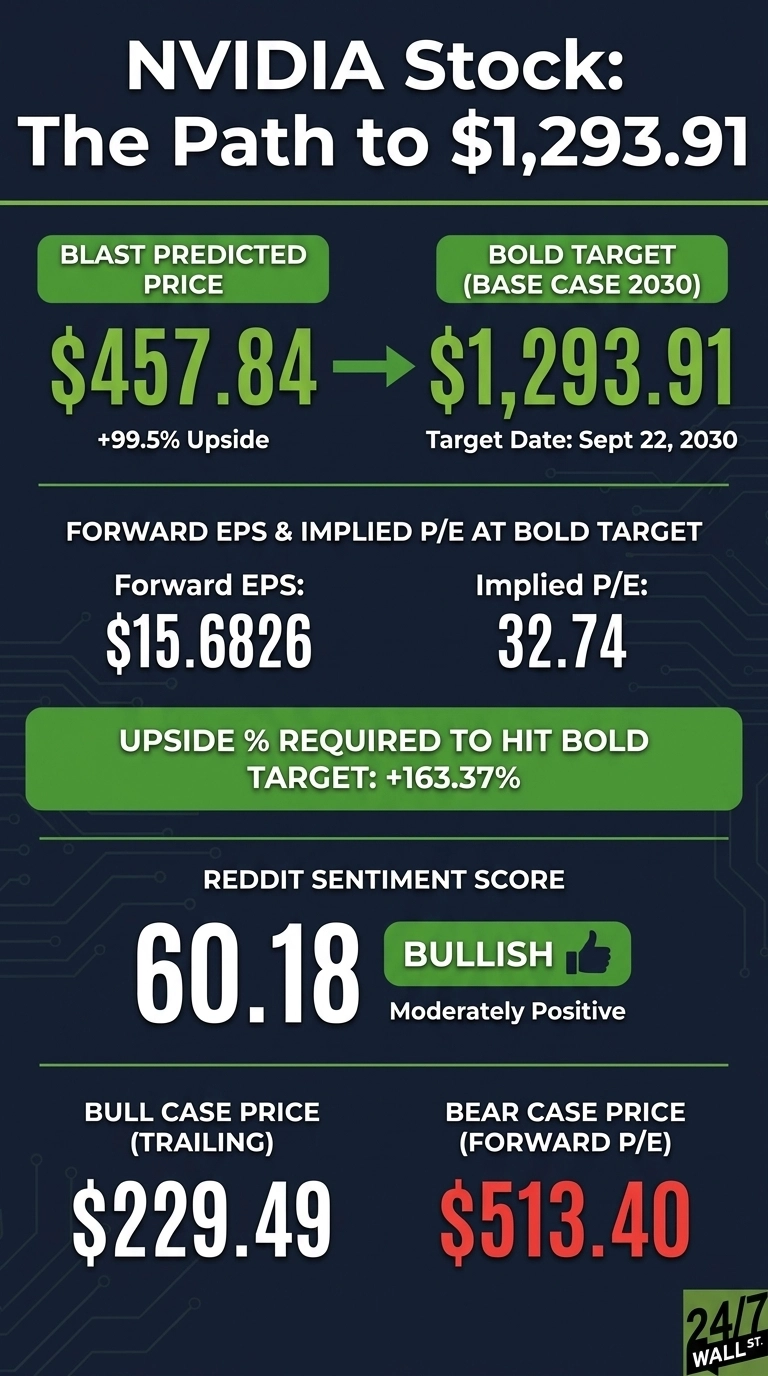
Under the base case, a recurring $500 per month from now through September 2030 would total $24,000 in contributions. On the modeled base-case path, that stake could grow to roughly $63,208.56, a total return of about 163.37% on cash invested.
The per-share anchor behind that figure is a base-case modeled price of $1,293.91 at September 22, 2030, drawn from the same five-year model that carries a 0.9 confidence rating and a buy signal.
Scenario Table: What $500 a Month Could Become by 2030
The table below uses the illustrative 2030 anchor point (2030-09-22) from the modeled five-year path. Total return is measured against the $24,000 of cumulative contributions.
| Scenario | 2030 Target Price | Total Return on $500/mo | Ending Value of $24,000 Invested |
|---|---|---|---|
| Base | $1,293.91 | 163.37% | $63,208.56 |
| Bull | $1,219.85 | 153.85% | $60,923.14 |
| Bear | $600.93 | 66.46% | $39,950.26 |
For context on the same model’s longer horizon, the five-year endpoints at September 22, 2031 land at $666.43 bear, $1,513.43 base, and $1,423.47 bull, with annualized returns of 23.77%, 45.83%, and 44.05% respectively.
Analyst consensus points to a shorter-horizon target of $327.70, with 9 strong-buy, 48 buy, 2 hold, and 1 sell ratings on file.

Why the Model Sees Room to Run
The base-case math sits on top of an earnings ramp that analysts keep revising upward. Consensus EPS for fiscal 2028 has moved from $12.6737 ninety days ago to $15.6826, with 42 upward revisions and zero downward revisions in the trailing 30 days. Fiscal 2028 revenue consensus now sits at $682.7 billion.
Management framed the demand picture in blunt terms on the Q2 FY2027 call. CFO Colette Kress said NVIDIA expects “to grow revenue by approximately 70% in fiscal 2028” and called it “a supply-constrained outlook.”
Cloud industry backlog was pegged at greater than $2 trillion, and top-five hyperscaler capex is forecast to reach $1.3 trillion in 2027 (all of that spending has to be powered, cooled, and networked by somebody, which is the whole point of our free report on seven AI infrastructure suppliers that aren’t chipmakers).
The Vera Rubin platform, which CEO Jensen Huang said was “built to power exactly this moment,” is expected to deliver $40 billion per gigawatt in AI factory revenue opportunity, up from $25 billion for Blackwell.

Q2 FY2027 itself set the tone: revenue of $96.22 billion (up 105.8% year over year), Data Center revenue of $89.02 billion, and non-GAAP EPS of $2.22. Guidance for Q3 called for revenue of $108.0 billion plus or minus 2%.
Risks That Could Sink the Projection
The bear column reflects tangible risks. Kress told investors that “given ongoing geopolitical uncertainty, there is no China data center compute revenue in our forward outlook,” and China H20 shipments were less than 1% of Data Center revenue in Q2.
Memory pricing is another squeeze: gross margins are expected to bottom in Q4 in the 71% to 72% range before settling at 72% to 73% in fiscal 2028.
NVIDIA has also committed to $279 billion in supply obligations and $108.5 billion in guarantee obligations to cloud and data-center partners.
If AI capex softens, or if customer-built silicon (Amazon (NASDAQ:AMZN) Trainium, for example) pulls share, the compounding math flips fast. Beta of 2.217 means any correction hits harder than the market.
Bottom Line for a $500 Monthly Stake by 2030
Contributing $500 a month from now through 2030 puts $24,000 of cash to work. The modeled outcomes place the ending value between roughly $39,950.26 in the bear case and $63,208.56 in the base case, with the bull path close behind at $60,923.14.
Every figure here is a scenario tied to modeled prices at September 22, 2030, not a guarantee. This is a projection, not investment advice, and NVIDIA’s actual four-year path will hinge on AI compute demand, supply constraints, and margin discipline.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.