Bad News Keeps Piling Up For Blue Owl, As Oracle Sends Force Majeure Letter To Lender. Stock Already Down Over 45% In The Last Year
Oracle just sent a force majeure letter to its lender on a piece of the $165 billion Stargate campus, and Blue Owl is the one absorbing the paperwork risk while its stock sits near a one-year low.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
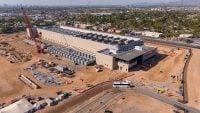
On the morning of September 24, 2026, Oracle (NYSE:ORCL | ORCL Price Prediction) sent a force majeure letter to Blue Owl Capital (NYSE:OWL) tied to the New Mexico piece of its $165 billion Stargate campus across Texas, New Mexico, and Ohio. Oracle told CNBC the project remains on schedule and that the notice is not a cancellation.
The market read the story as an Oracle problem, but Oracle shares were down 5.02% at $137.31, but the paperwork risk landed on the lender. Blue Owl, already bruised, traded at $9.20, down 4.22% on the session, down 21.23% over one month and down 46.7% over one year.
What the Letter Actually Covers
Per CNBC’s Seema Mody, the notice is “by no means a cancellation” but “a way for oracle to sort of reiterate its contractual rights” and “to understand the obligations, the financial obligations tied to this $165 billion campus” should local pushback extend beyond six to nine months. The New Mexico site faces issues on three fronts: water, power, and air, with a permit still pending.
Undisclosed: Blue Owl’s specific dollar exposure to the New Mexico piece (an earlier CNBC segment characterized the underlying project at $18 billion), the fund vehicle holding it, and any Blue Owl response as of publication.
Read-Through by Ticker
Blue Owl (NYSE:OWL) has market cap of $6.29 billion. Its real assets platform reported $89.4 billion in AUM, up 25% year over year, driven by digital infrastructure and net lease. On August 28, 2026, its managed funds led a $2.4 billion AI factory financing for IREN. The firm has publicly framed its data-center book as “an IG business” with non-investment-grade exposure “essentially inconsequential.” A force majeure invocation on a flagship Stargate parcel tests that framing publicly for the first time.

Oracle (NYSE:ORCL) has market cap of $415.31 billion. Q1 FY2027 delivered $19.345 billion in revenue, up 29.6%, with Remaining Performance Obligations of $664 billion. On the September 10 call, management said “neither Shackleford nor New Mexico or Wisconsin or Michigan were delivered in Q1” and “All of our eggs are not in a single basket.” A single site slipping is not a catalyst against that RPO base. The stock is down 55.75% over one year, reflecting valuation reset, not this letter.

Reality Check
Blue Owl has been leaning into AI credit as private credit stress widens. The private credit default rate rose to a record 6.3% in the 12 months through August, per CNBC on September 15, 2026. Management said on the July call it was “prepared for some normalization off of very low loss rates,” but a hyperscaler formally invoking contract relief on a lender-financed campus is a category the transcript did not contemplate. Notably absent from Oracle’s earnings call: any mention of a force majeure letter, and no reference to Oracle in Blue Owl’s Q2 commentary on the same portfolio.
Oracle’s counter framing is that the letter is a contractual bookkeeping shield. That is plausible given the RPO backlog. It also does not make the lender’s problem smaller if permitting drags. The financiers, power suppliers, and cooling vendors sitting behind these campuses are where the real AI buildout risk lives (we profiled seven of them in a free report you can grab here).
Does This Change the Blue Owl Thesis?
Blue Owl’s growth story has been digital infrastructure credit at scale. Today’s letter is the first public data point that the counterparty will use contractual mechanics when a site hits regulatory friction. Watch for an 8-K from Blue Owl disclosing exposure to the New Mexico project, or a Q3 earnings report (Blue Owl last filed an 8-K on July 30, 2026 at $9.56) that quantifies the specific fund exposure. If OWL breaks and holds below $9.00 before that filing arrives, the market has already decided the answer.
Contact [email protected] for any questions or corrections.
AJ spent 10 years writing about financial markets at The Motley Fool. His coverage centers on technology stocks and the broader macroeconomic trends, from interest rates to geopolitics, that shape where markets are headed next. AJ is drawn to the stories where big-picture economics and individual companies collide.