Apple Stock Outlook: Our Target Leaves Wall Street Behind
Wall Street has Apple pegged at one price target, but our proprietary model lands somewhere else entirely, and the gap between the two tells a story about where this stock may be headed after a record-breaking June quarter.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
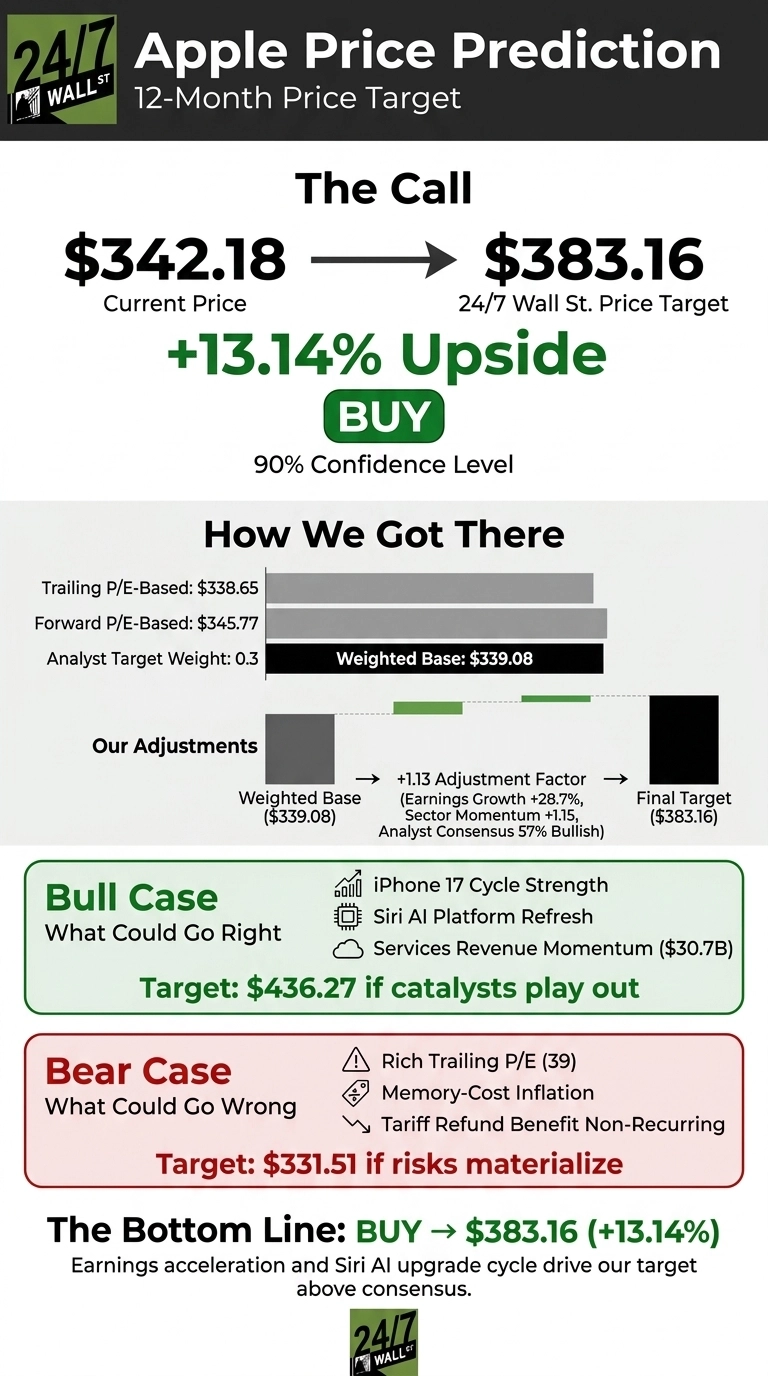
Apple (NASDAQ:AAPL | AAPL Price Prediction) has become one of the most talked-about mega-caps of 2026 after a monster iPhone 17 cycle. Our proprietary model sees more room to run, with a 24/7 Wall St. price target meaningfully above the Street’s consensus given earnings acceleration and Services momentum from the June quarter.
| Metric | Value |
|---|---|
| Current Price | $342.18 |
| 24/7 Wall St. Price Target | $383.16 |
| Upside | 13.14% |
| Recommendation | BUY |
| Confidence Level | 90% |
The24/7 Wall St. price target for Apple is $383.16, well above the Wall Street consensus of $328.22. Our model returns a buy rating with high confidence.

Momentum Coming Out of a Record June Quarter
Apple shares are up 26.21% year to date, trading just below its 52-week high of $344.27.
The Q3 FY2026 earnings report in late July was the catalyst: revenue of $109.4 billion rose 16% year over year, diluted EPS of $2.02 jumped 29%, and iPhone revenue climbed 22% to $54.3 billion. That extended Apple’s EPS beat streak to nine consecutive quarters.

Why Bulls See a Breakout Ahead
The bull case: the iPhone 17 cycle is running hotter than expected, Siri AI arrives as a platform refresh, and Services is a compounding cash engine. Tim Cook flagged that supply constraints stem from a “demand forecast issue” because iPhone and Mac are outperforming.
Services revenue hit $30.7 billion with $1.5 billion in paid subscriptions, and Mac grew 29%. Cook said, “I truly have never been more confident that the best is yet to come.” Our bull-case one-year price is $436.27.

Risks Worth Watching
Bears will point to a rich 39 trailing P/E, memory-cost inflation Apple called “a 100-year flood,” and a roughly two-percentage-point gross margin benefit from tariff refunds that won’t recur.
Management guided September gross margin to 47% to 48% and revenue growth of 9% to 11%, showing the business absorbs these pressures. Our bear-case one-year price is $331.51.

How Apple Compares to Microsoft and Alphabet
To gauge whether our target is reasonable, I stacked Apple against two mega-cap tech peers with genuine overlap.
| Company | Forward P/E | Analyst Target |
|---|---|---|
| Apple | 35 | $328.22 |
| Microsoft | 25 | $575.34 |
| Alphabet | 23 | $429.46 |
Microsoft (NASDAQ:MSFT) trades at a forward P/E of 25 with an operating margin of 45.1% and quarterly earnings growth of 31.7%. Apple looks pricier on that basis, but its 171.4% ROE and buyback pace are hard to match.
Alphabet (NASDAQ:GOOGL) trades at a trailing P/E of 18 with quarterly earnings growth of 294%, making Apple look expensive on paper. Yet Apple’s ecosystem lock-in and Services flywheel command the premium. The peer group makes our 24/7 Wall St. price target reasonable.
Bottom Line on Apple’s Setup
The 24/7 Wall St. price target is $383.16, a buy with 90% confidence. Earnings acceleration meets a Siri AI upgrade cycle at a mega-cap that returned $33 billion to shareholders in one quarter.
Investors focused on iPhone 17 momentum extending through the holiday may see continued upside, while those worried about memory costs compressing margins faster than tariff refunds offset have reason for caution.
Our model projects Apple’s price in the coming years, assuming current growth trajectories hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $383.16 |
| 2027 | $384.14 |
| 2028 | $413.22 |
| 2029 | $453.84 |
| 2030 | $484.17 |
These projections assume Apple continues executing on Siri AI, iPhone cycles, and Services expansion. Significant upside or downside could result from AI monetization pace or renewed China demand pressure.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.