JPMorgan Sees Micron Positioned for Beat-and-Raise Ahead of Q4 Results
JPMorgan sees multiple levers working in Micron's favor before its September 30 earnings report, but the stock has a troubling habit of selling off sharply even after big beats. Here is what separates a clean setup from a value trap…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
JPMorgan kept its Overweight rating and $1,540 price target on Micron (NASDAQ:MU | MU Price Prediction) ahead of the company’s fiscal Q4 report on September 30. The firm calls the setup “constructive,” with “multiple beat-and-raise levers still in play.”
The restatement shows Wall Street still has confidence in Micron’s pricing power. Investors now have to consider that against a history of sharp selloffs after earnings reports.
| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| MU | Micron | JPMorgan | Repeated | Overweight | Overweight | Not disclosed | $1,540 |
Analyst’s Case: Pricing Momentum Outran Guidance
JPMorgan says in a note that the memory background remains structurally tight across both DRAM and NAND. Micron should report Q4 revenue, gross margin and earnings above consensus estimates, the firm says.
The core of the call is pricing. According to JPMorgan, pricing momentum through the quarter stayed robust even though management had warned of “a meaningful moderation in the rate of price increases.”
Management’s own view supports the thesis: it expects DRAM and NAND supply-demand conditions to stay tight beyond calendar 2027.
Company Snapshot: Micron’s Record-Setting Streak
In fiscal Q3, revenue reached $41.46 billion, up 345.7% year over year. Non-GAAP EPS of $25.11 exceeded the $20.28 consensus, making it Micron’s seventh consecutive earnings beat. Free cash flow came in at $18.30 billion.

For Q4, Micron guided to revenue of $50 billion ± $1 billion, EPS of $31 ± $1 and gross margin near 86%. The company has also signed 16 multi-year Strategic Customer Agreements. Fourteen of them carry about $100 billion in total revenue at minimum-price terms.
Why Micron Stock’s Setup Matters This Week
The Street is already expecting more than the guidance. Consensus calls for Q4 EPS of $31.3542 on revenue of $50.97 billion, both above the guidance centers. To deliver the beat JPMorgan expects, Micron has to clear that higher bar.
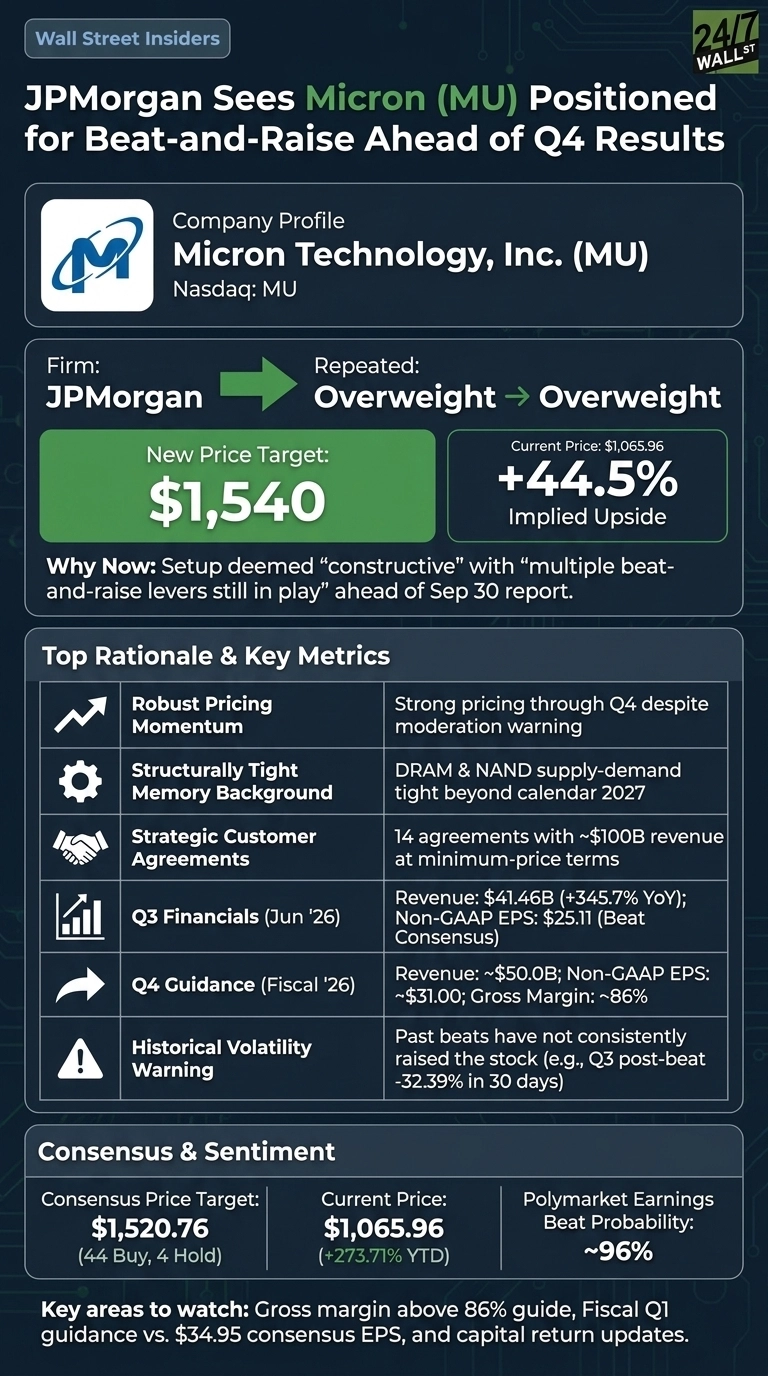
The shares trade near $1,065.96, up 273.71% year to date. That works out to a trailing P/E of about 24 and around 7x forward earnings.
The consensus price target is $1,520.76, with 44 buy ratings and 4 holds. On Polymarket, traders put the chance of an earnings beat at about 96%.

What It Means for Your Portfolio Before Wednesday’s Report
A beat has not consistently raised the stock. After fiscal Q3’s 23.79% EPS surprise, the stock was -19.61% after one week and -32.39% after 30 days. Fiscal Q2 followed a similar pattern, with a one-week change of -19.99%. With a beta of 2.222, the stock tends to make big moves in both directions.

Those saving for retirement should look past the headline numbers. Key points to check:
- Whether gross margin comes in above the around 86% guide
- Whether fiscal Q1 guidance clears the consensus EPS estimate of $34.9476
- Any update on the larger capital returns planned to begin December 9, 2026
JPMorgan’s view makes a strong case for studying the thesis closely. Near-term volatility remains a real risk.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.