Micron Walks Into the Biggest Earnings Setup of the AI Memory Cycle
Micron shares are up 247% this year and Wall Street has piled on with 92% bullish coverage, yet the stock sits nearly 40% below the consensus price target heading into a make-or-break earnings report. What it takes to reach $1,600…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Micron Technology (NASDAQ:MU | MU Price Prediction) has become the purest AI memory play, and the setup into next week’s earnings is unlike anything I’ve seen in this cycle. Shares are up 247.43% year to date, riding a fiscal 2026 that produced $41.46 billion in Q3 revenue and non-GAAP EPS of $25.11.
CEO Sanjay Mehrotra said memory has been elevated to “a strategic asset” in the AI era. With the earnings report scheduled for September 30, 2026, I want to answer one question: can MU actually hit $1,600 per share?
Why Micron Shares Have Stalled Above $990
The stock is digesting. MU is up just 1.39% over the past week and 5.34% over the past month, well behind its earlier trajectory.
After Q3 delivered a 15.74% day-of pop, shares gave back 19.61% the following week and 32.39% over 30 days as traders rotated. With a beta of 2.222, MU whips around. Q3 carried a $325 million loss on debt prepayments plus $7.83 billion of capex, so free cash flow discipline is under scrutiny.
Wall Street Wants $1,513. My Model Says the Path Runs Higher
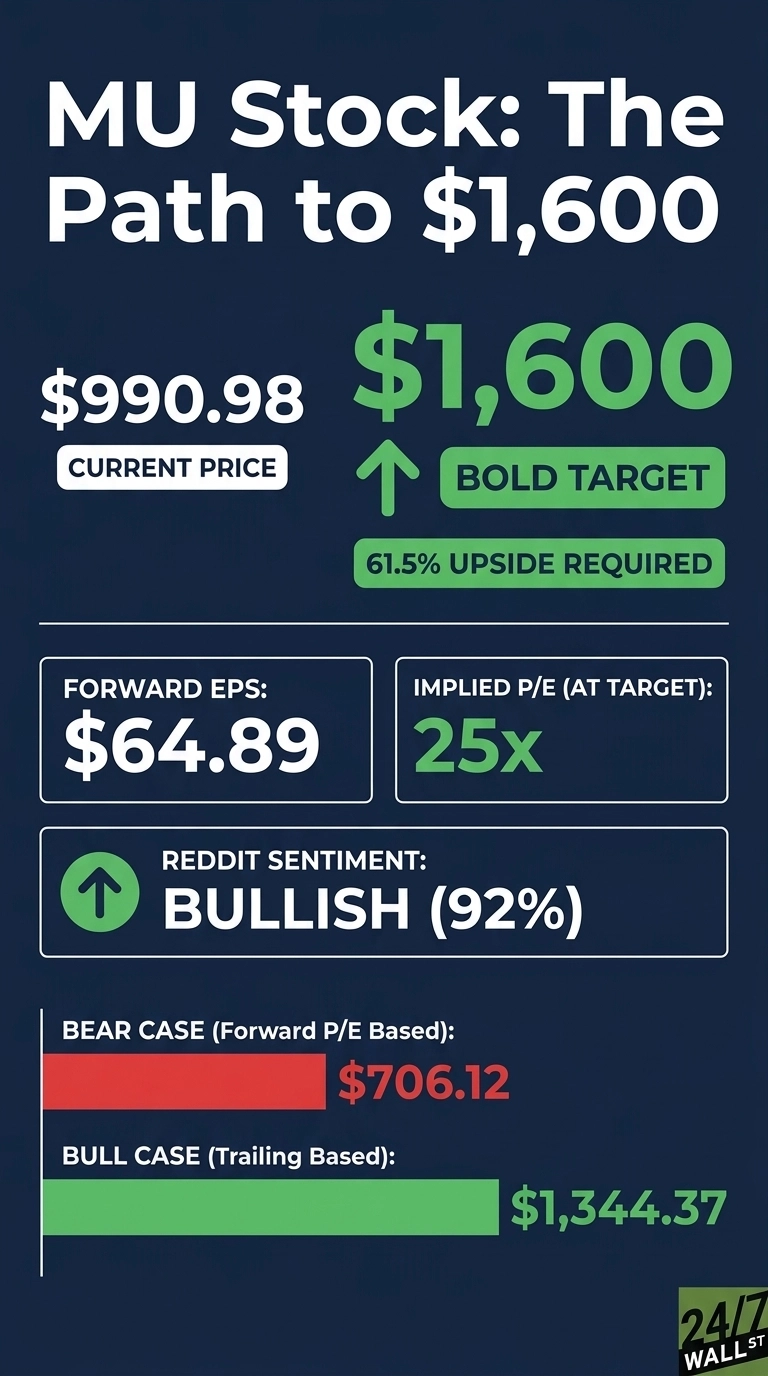
Consensus is bullish. The Street price target sits at $1,513.11, with 9 strong buys, 35 buys, 4 holds, and zero sells (92% bullish). Our base case is $949.19, with a bull case of $1,344.37 and a bear case of $706.12. Model confidence is high (0.9).
The base case leans on a trailing multiple that hasn’t absorbed the FY27 EPS ramp from $73.44 to $156.07. If the SCAs Mehrotra described land, analysts are still too low.

Path to $1,600 Per Share by 2027
Reaching $1,600 from $990.98 requires a 61.5% gain. With forward EPS of $64.89, a $1,600 price implies a forward P/E of 25x. Our base case of $949.19 implies 21x, so the bold target needs about 4x of additional multiple expansion.
Mehrotra told analysts Micron has signed 16 Strategic Customer Agreements covering roughly $100 billion in minimum-price revenue, with expected cash deposits of $22 billion.
He added, “We expect tight conditions to persist beyond calendar 2027 as a result of AI-driven demand across all segments coupled with structural supply constraints.”
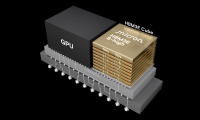
HBM4 12-high is ramping twice as fast as HBM3E, and the model’s adjustment factor of 1.14 reflects sector momentum and 92% bullish coverage. Primary risk: a demand air pocket if hyperscaler capex plans slip.
Where MU Actually Trades vs Its Earnings Power
At $990.98, MU trades at a forward P/E of just 15x against $64.89 in forward EPS. That is cheap for a company guiding Q4 revenue to $50 billion with GAAP gross margin near 86%.
Shares sit between a 52-week low of $154.40 and a 52-week high of $1,254.81. If FY27 EPS lands near the $156 consensus, today’s price is a starting point.

Is $1,600 Realistic? My Verdict
Reaching $1,600 requires a 61.5% gain and a forward multiple of 25x. I call it credible. Three things must go right: Q4 earnings must clear the $31 EPS bar, SCA-driven revenue visibility must translate into FY27 EPS revisions above $156, and HBM4 yields must ramp on schedule.

What derails it is a hyperscaler capex pause that lets memory supply catch up before pricing power peaks. The same AI buildout powering Micron’s order book is lifting a whole roster of picks-and-shovels suppliers most investors overlook (we profiled seven of them, from power to cooling, in a free report you can grab here). We’ve outlined the blueprint for how Micron Technology could reach $1,600 in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.