We’re Bullish on Oracle With 51% Upside Despite Recent Selloff
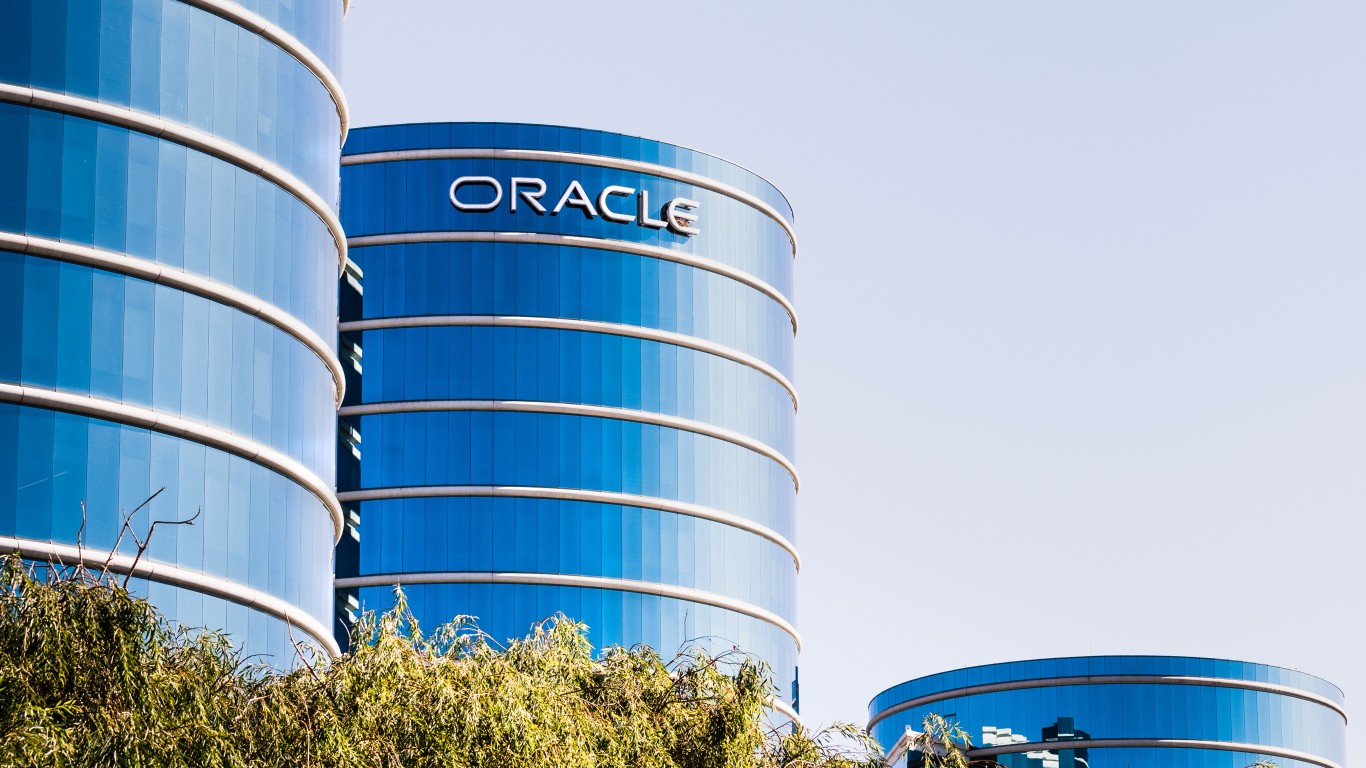
Oracle shares have cratered 28% this year while its AI contract backlog swells to a staggering size, and the gap between that selloff and the underlying business momentum raises a question Wall Street has not yet answered.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The 24/7 Wall St. price target for Oracle (NYSE:ORCL | ORCL Price Prediction) is $210.53 over the next 12 months. That implies 51.48% upside from the $138.98 reference price. The model rates Oracle a buy with 90% confidence, which is high conviction.
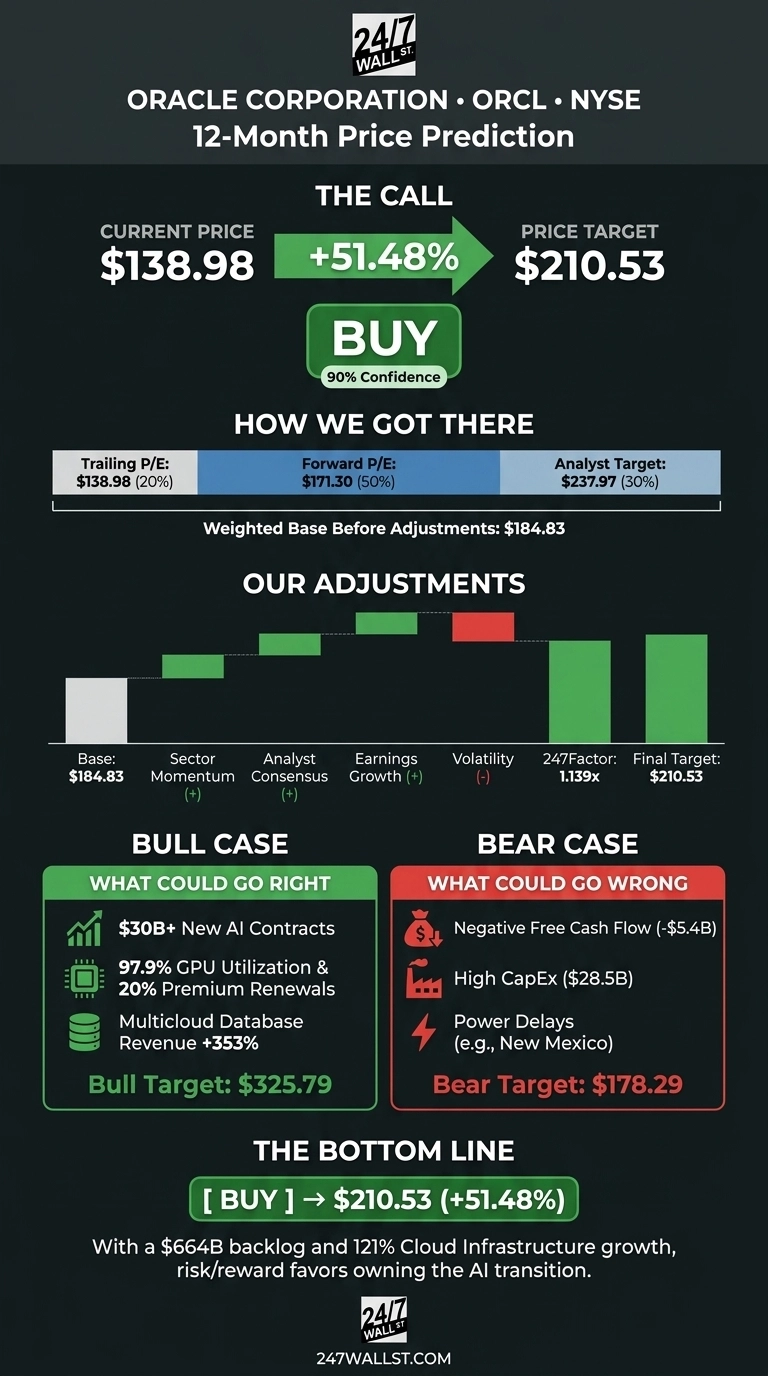
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $138.98 |
| Price Target from 24/7 Wall St. | $210.53 |
| Upside/Downside | 51.48% |
| Recommendation | BUY |
| Confidence Level | 90% |
Shares were trading near $138.29 Friday afternoon. In my view, the market is focused on cash burn and giving too little credit to how fast a $664 billion backlog is turning into revenue. Cloud now makes up 60% of sales.

A Steep Drawdown Collides With Triple-Digit Cloud Growth
Oracle fell 8.17% over the past week and 28.36% year to date. It sits about 56.7% below its 52-week high of $319.46. The fundamentals point the other way. Oracle reported fiscal Q1 on September 10.
Adjusted EPS of $1.92 beat the $1.7391 consensus, and revenue of $19.345 billion rose 29.61%. Cloud infrastructure revenue grew 121%. Management raised fiscal 2027 EPS guidance to $8.10.
This week’s slide followed a force majeure notice that Oracle sent to a Blue Owl unit developing its New Mexico campus. The notice cited potential delays in securing power.
On the call, management said New Mexico would not affect fiscal 2027 guidance. Power is quietly becoming the constraint for the entire AI expansion, and the suppliers solving it (utilities, cooling, grid equipment) are a separate trade we walked through in a free report on seven AI infrastructure stocks that aren’t chipmakers.
Why Bulls See $325 or More
Management expects about half of RPO (remaining performance obligations, meaning contracted revenue not yet recognized) to convert over the next 36 months.
Oracle signed more than $30 billion in new AI contracts without putting additional capital of its own. GPU usage reached 97.9%, and capacity that came up for renewal re-signed at a 20% premium.
Multicloud database revenue grew 353%. Wall Street largely agrees. The stock has 8 Strong Buy and 28 Buy ratings and a consensus target of $237.97. The bull case reaches $325.79.

Cash Burn and Power Delays Could Test Patient Shareholders
Free cash flow was -$5.396 billion. Management expects fiscal 2027 capex of $90 billion to $95 billion, and interest expense rose to $1.4 billion. A $20 billion equity program also diluted holders.
On the other side, operating cash flow rose 183.82%. CFO Hilary Maxson said scaled projects deliver “a free cash flow conversion ratio of something like 100% to post-tax EBITDA.” Our bear case of $178.29 still remains above today’s price.
Oracle Trades at a Discount to Microsoft and Amazon
Azure competes with Oracle for the same AI training customers, which is why Microsoft (NASDAQ:MSFT) belongs in this comparison. It trades at 25x forward earnings.
AWS is the largest IaaS rival and also a multicloud partner, and Amazon (NASDAQ:AMZN) trades at 24x forward earnings. Our target implies about 17x earnings, well below both peers, so it looks reasonable and even conservative.
| Company | Forward P/E | EV/EBITDA |
|---|---|---|
| Oracle | 18 | 14.87 |
| Microsoft | 25 | 17.72 |
| Amazon | 24 | 10.98 |
I’d Own the Backlog at This Price
The 24/7 Wall St. price target of $210.53 has a buy rating with 90% confidence. What tips the scale for me is backlog converting to revenue.
I’d be a buyer if cloud growth lands within the 65%-71% Q2 guidance. I’d stay on the sidelines if power delays spread beyond New Mexico. At under 18x forward earnings, I think the risk/reward favors owning Oracle.

If current trends hold, here is where our model projects Oracle could trade by year-end:
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $151.32 |
| 2027 | $231.65 |
| 2028 | $291.45 |
| 2029 | $361.36 |
| 2030 | $395.26 |
Oracle needs to keep delivering datacenter capacity on schedule for these projections to hold. Financing costs or the pace of AI demand could drove results well above or below these figures.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.