Prediction: Oracle’s Growth Story Has Entered a New Era, Eyes 40% Upside
Oracle just posted numbers that sent its backlog into record territory, yet the stock sits near a 52-week low. Whether that gap represents a generational buying opportunity or a debt-fueled trap depends on one question the market has not yet…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Oracle has quietly transformed from a legacy database vendor into one of the most strategically positioned AI infrastructure players in the market. That shift is reflected in a backlog few competitors can match, and it is the backbone of our updated 24/7 Wall St. price target.
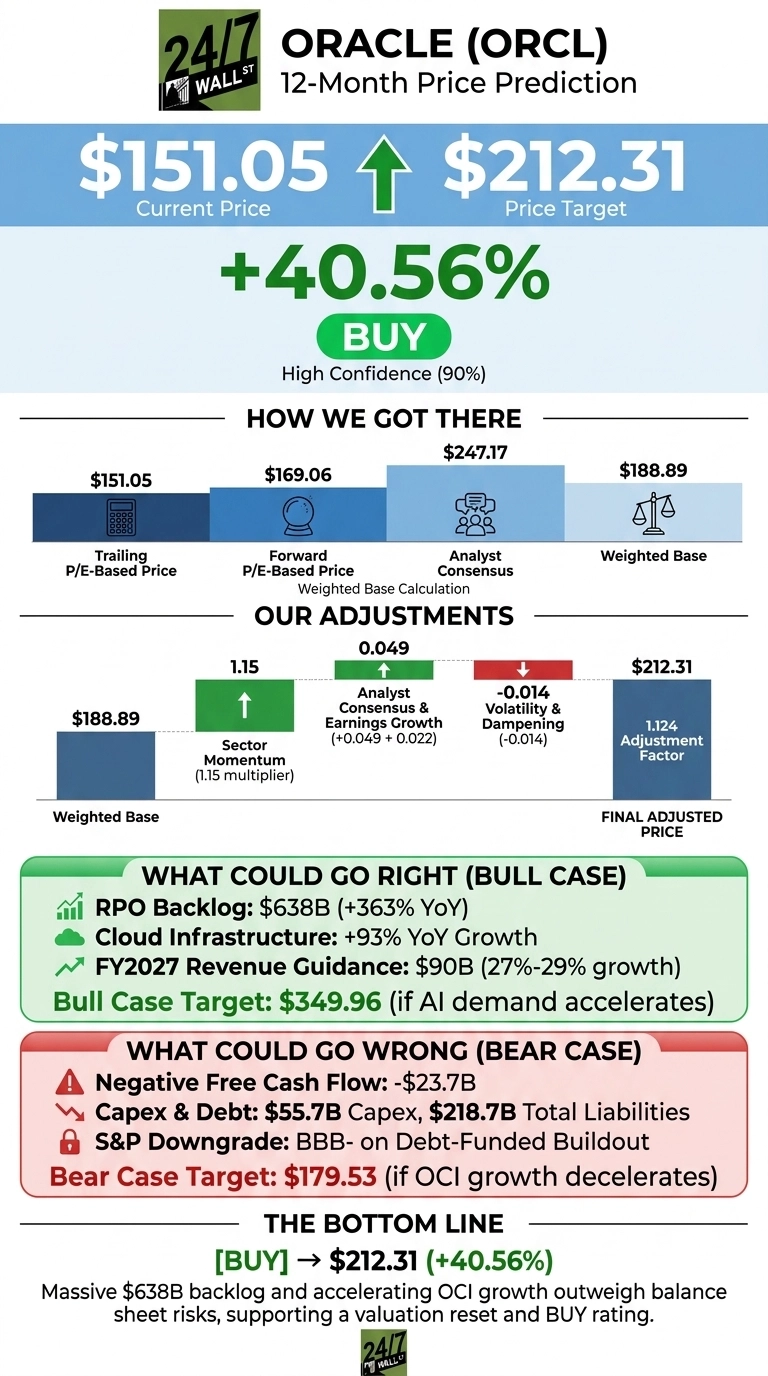
Oracle (NYSE:ORCL | ORCL Price Prediction) trades at $151.05 after a sharp drawdown from last October’s highs. Our 24/7 Wall St. price target is $212.31, implying 40.56% upside over the next 12 months.
We rate the shares a buy with 90% confidence, one of the higher readings our model has produced this cycle. The setup blends visible contracted revenue, accelerating cloud growth, and a valuation reset that has compressed the multiple materially.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $151.05 |
| 24/7 Wall St. Price Target | $212.31 |
| Upside | 40.56% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Reset That Went Too Far
Oracle is up 6.49% over the past week and 7.4% in the last month, but down 21.75% year to date and 38.9% over the trailing year. The 52-week range spans $341.82 to $114.50.
The Q4 FY2026 report in June was the fundamental highlight. Oracle posted EPS of $2.11 on revenue of $19.18 billion, with Cloud Infrastructure revenue up 93% YoY to $5.79 billion. Remaining Performance Obligations surged 363% to $638 billion.
Management confirmed $90 billion in FY2027 revenue and raised non-GAAP EPS guidance to $8.05. The offset has been a S&P downgrade to BBB- tied to debt-funded buildout.

The Bull Case
The bull case rests on RPO conversion. Safra Catz told investors OCI would grow from $18 billion in FY2026 to $32 billion, $73 billion, $114 billion, and $144 billion over the following four years, with most already booked.
Oracle is more than halfway through building 72 Multicloud datacenters inside Amazon, Google, and Microsoft, and Multicloud Database revenue jumped 404% in Q4. All top five AI models run on Oracle Cloud. If FY2027 delivers on the 27%-29% revenue growth guide, our bull-case scenario points to $349.96, roughly a 131% return.
What Could Go Wrong
The bear case is the balance sheet. Free cash flow was negative $23.69 billion in FY2026 on $55.66 billion of capex, and Oracle plans to raise roughly $40 billion more in FY2027 through debt and a $20 billion ATM equity program. UBS cut its target to $245 citing OpenAI concentration risk.
Management counters that it is investing behind contracted, prepaid demand rather than speculation, and acceptance times are shrinking, in one case to “one week”. Our bear case still lands at $179.53, above today’s price.
How Oracle Compares to Microsoft and Salesforce
Microsoft (NASDAQ:MSFT) is the cleanest hyperscaler comparison, since Azure and OCI now compete for the same AI workloads. Microsoft trades at a trailing P/E of 28 with $678 billion in commercial RPO on a much larger revenue base. Oracle’s forward P/E of 18 looks conservative against that.
Salesforce (NYSE:CRM) is the SaaS counterpoint. Salesforce trades at a P/E of roughly 22 with FY27 revenue guided to $45.9-$46.2 billion and mid-teens growth. Oracle’s cloud is growing far faster off a comparable base. The peer set makes our $212.31 target look reasonable, arguably conservative, given Oracle’s growth premium.
Oracle Price Projection 2026-2030
Our 24/7 Wall St. price target is $212.31, our recommendation is buy, and confidence is 90%. The $638 billion backlog tips the scale. The thesis holds for investors willing to underwrite the capex and leverage story for 18 months while RPO converts.
The setup weakens if OCI growth decelerates below the 58% low end of Q1 guidance, which would signal the AI order book is flattening.

| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $212 |
| 2027 | $255 |
| 2028 | $300 |
| 2029 | $345 |
| 2030 | $390 |
These projections assume Oracle converts RPO into recognized revenue on the trajectory Safra Catz laid out, reaching $144 billion in OCI by FY2030. Upside or downside hinges on whether AI infrastructure demand holds and whether Oracle can service its debt load without diluting shareholders further.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.