SoFi’s Next Growth Engine Could Surprise Wall Street
SoFi shares have collapsed nearly 40% this year even as the company keeps beating forecasts and adding members at a record pace. The path to a dramatic recovery exists, but it depends on a few catalysts Wall Street has not…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
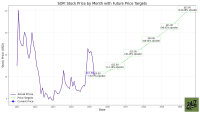
SoFi Technologies (NASDAQ:SOFI | SOFI Price Prediction) has been one of 2026’s toughest stocks to own. Shares sit at $15.97, down 39% year-to-date and well below the 52-week high of $32.73. The business continues to expand.
In the second quarter, SoFi added a record 2.2 million products. For the first time, it added twice as many products as members, a milestone CEO Anthony Noto called “a clear inflection point for SoFi.” With the stock close to its lows, I want to lay out how SoFi could reach $25 per share in 2027.

Wall Street Sees 27% Upside as 2027 Estimates Rise
The consensus price target of $20.35 implies about 27% upside. Analysts expect 2027 EPS of $0.8240, compared with $0.5947 in 2026. That works out to roughly 39% growth, on about 25% revenue growth. Ninety days ago, the 2027 estimate stood at $0.8127. Over the past 30 days, analysts made five up revisions and two down ones.

SoFi has also met or beaten EPS expectations for six straight quarters, and revenue topped estimates in every one of them. In Q2, EPS came in at $0.12, above the $0.1092 forecast. A run like that suggests the current estimates may turn out to be conservative.

Here’s What It Takes for SoFi to Reach $25
SoFi trades at about 19x 2027 earnings, below the S&P 500’s forward multiple of roughly 22x. At $25, the multiple would be about 30x. That is a premium, but management’s medium-term guidance calls for 38% to 42% annual EPS growth through 2028, and the stock’s PEG ratio is just 0.596.
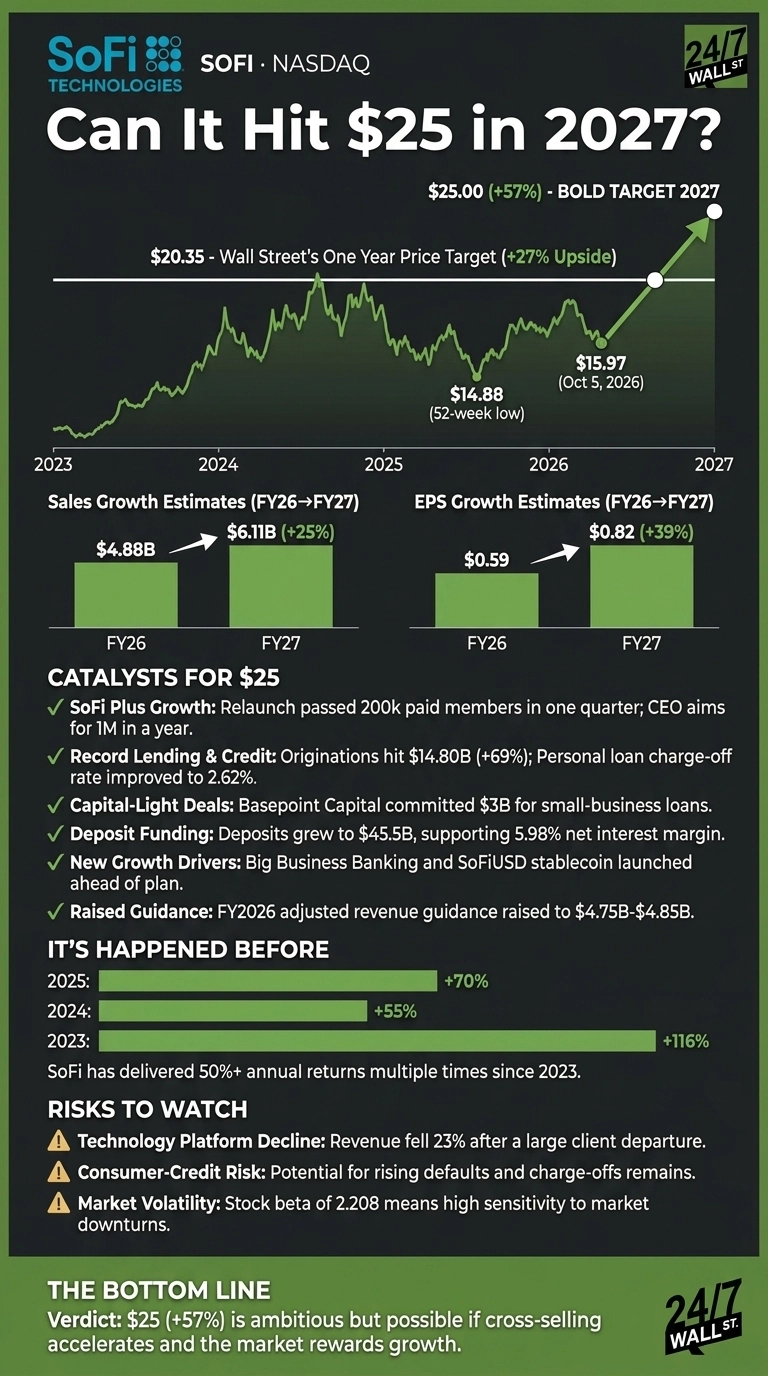
Here’s what could drive SoFi to $25.
- SoFi Plus growth: The relaunched subscription passed 200,000 paid members in one quarter. Noto said, “I’d be disappointed if we are not at 1 million SoFi Plus members generating annual revenue of $120 million a year from now.”
- Record lending with better credit: Originations reached $14.80 billion, up 69%. Over the same period, the personal loan charge-off rate fell to 2.62% from 2.83%.
- Capital-light platform deals: Basepoint Capital signed a $3 billion small-business loan agreement, and Sixth Street committed up to $1 billion for personal loans.
- Deposit funding: Deposits rose to $45.5 billion, supporting a net interest margin of 5.98%.
- New growth drivers: Big Business Banking, the SoFiUSD stablecoin, and planned Mastercard (NYSE:MA) card settlement in SoFiUSD were all launched outside the original 2026 plan.
- Raised guidance: 2026 adjusted revenue guidance now stands at $4.75 billion to $4.85 billion.
With a beta of 2.208, SoFi would gain more than most stocks from falling rates and a strong market. A downturn would make $25 toughest to reach.

SoFi’s History Says a 57% Gain Is Possible
Reaching $25 requires a gain of about 57%. SoFi has cleared that bar in two of its last three full years. Shares rose 116% in 2023 and 70% in 2025. The 55% gain in 2024 fell just short. SoFi’s volatility works in both directions.
Is $25 Realistic? Here’s My Take
A 57% gain is ambitious, but Wall Street already sees 27% upside, 2027 estimates are rising, and SoFi keeps beating forecasts.
Key hurdles remain: Technology Platform revenue fell 23% after a large client left, and consumer-credit risk never goes away. If cross-selling keeps accelerating and the market rewards that growth, $25 is within reach. Returns at this level aren’t an annual occurrence, but we’ve outlined the case for how SoFi could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.