Wall Street Agrees on Amazon and Can’t Agree on Tesla. The Targets Show Why
Analysts have nearly united behind one mega-cap while remaining deeply split on the other, and the price targets reveal exactly why these two stocks belong in completely different conversations.

Wall Street analysts have reached a consensus on one of these mega-caps and remain split on the other.
Amazon (NASDAQ:AMZN | AMZN Price Prediction) carries 16 Strong Buy, 43 Buy and 2 Hold ratings, with zero Sells. Tesla (NASDAQ:TSLA) has 4 Strong Buy, 15 Buy, 21 Hold, 2 Sell and 2 Strong Sell.
Amazon’s 24/7 Wall St. price target is $332.67. Tesla’s target from 24/7 Wall St. stands at $405.69.
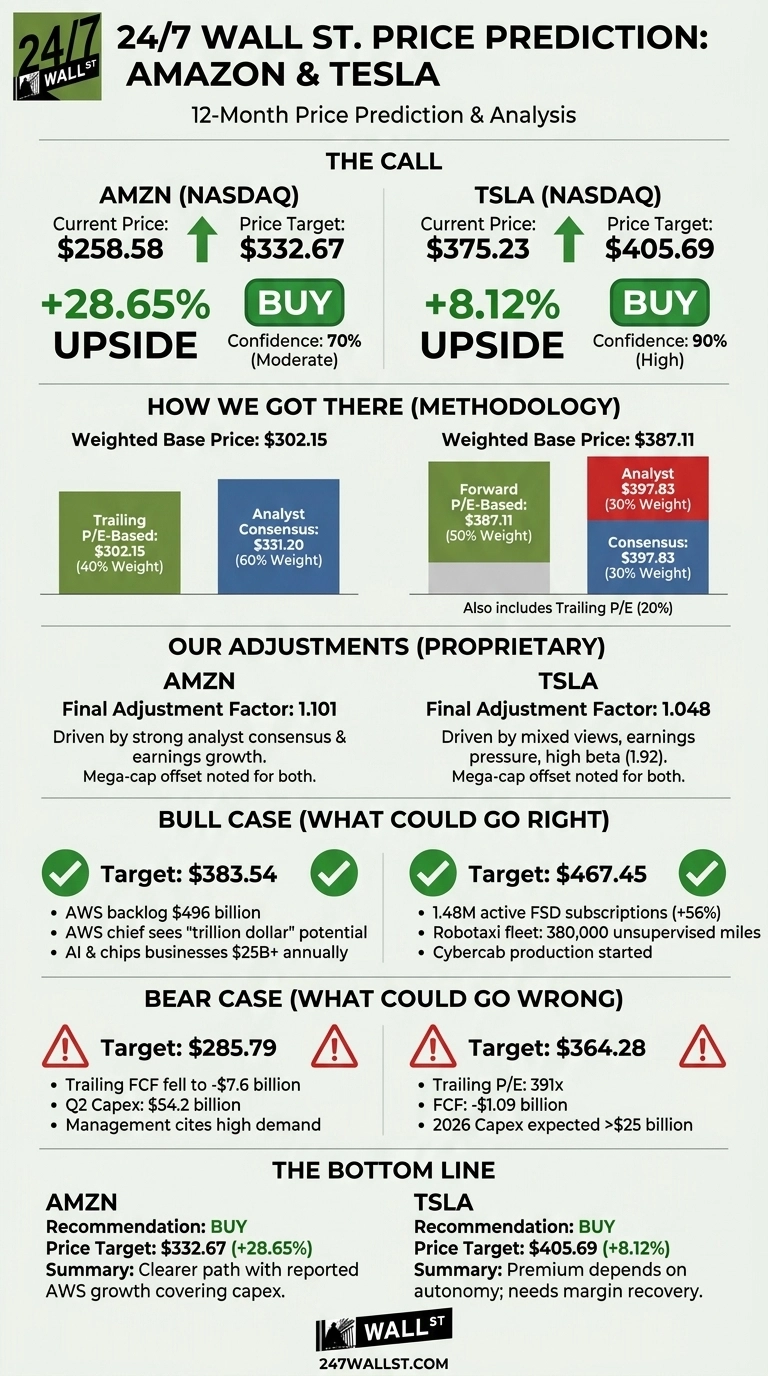
24/7 Wall St. Price Target Summary
| Metric | Amazon | Tesla |
|---|---|---|
| Current Price | $258.58 | $375.23 |
| The 24/7 Wall St. price target | $332.67 | $405.69 |
| Upside | 28.65% | 8.12% |
| Recommendation | BUY | BUY |
| Confidence Level | 70% | 90% |
Our model rates both stocks buy, with very different upside. Amazon’s larger upside comes with moderate confidence because it leans heavily on the analyst consensus target of $331.20.

Tesla’s lower upside is a high-confidence call because its valuation inputs line up closely with analysts’ $397.83 consensus.

AWS Is Accelerating While Tesla’s Margins Shrink
Amazon is up 1.83% over the past week, 1.63% over the past month and 13.06% year to date. Its 52-week range goes from $196 to $287.20.
Second-quarter revenue rose 19.6% to $200.61 billion. AWS grew 37%, its fastest pace in 18 quarters, and advertising climbed 26%. GAAP EPS of $5.75 included a $53.4 billion gain on Amazon’s Anthropic stake.
Tesla is down 16.6% year to date and stands 20% below its $498.83 52-week high. Revenue of $28.24 billion exceeded estimates, but EPS of $0.33 missed the $0.54 consensus as operating margin fell to 1.4%. Ahead of Tesla’s next earnings report, Morningstar is reassessing whether the stock is fairly valued.
Why Bulls Expect Breakouts in Both Stocks
AWS reported a backlog of $496 billion. Its chief executive said AWS could “very possibly be a trillion dollar annual revenue business”. Amazon’s AI and chips businesses each run above $25 billion annually. Amazon’s bull case stands at $383.54.

Tesla has 1.48 million active FSD subscriptions, up 56%. Its Robotaxi fleet logged 380,000 unsupervised miles with “zero notable incidents,” and Cybercab production has started in Texas. Tesla’s bull case stands at $467.45. Price targets from individual firms were not available.

Capex Bills and Valuation Strain Are the Key Risks
Amazon’s trailing free cash flow fell to -$7.6 billion after $54.2 billion of second-quarter capex. Management said most of its 2027 capacity is already reserved, which suggests customer demand is supporting that spending. Our bear case is $285.79.

Tesla trades at a 391x trailing P/E, and free cash flow came in at -$1.09 billion. Management also expects 2026 capex above $25 billion.
On the other side, Tesla holds net cash, and its automotive margins excluding credits would have been approximately flat after adjusting for one-time benefits in the first quarter. Our bear case is $364.28.

Walmart and GM Show What Each Valuation Assumes
Walmart (NASDAQ:WMT) competes with Amazon in retail, advertising and membership. It trades at 41x trailing earnings, above Amazon’s 36x, and its advertising revenue grew 38%. Amazon’s lower multiple comes with AWS on top of retail, which makes the 24/7 Wall St. target look reasonable.
General Motors (NYSE:GM) shows what the market pays for car profits alone. GM trades at 27x, beat consensus with Q2 adjusted EPS of $3.57, and raised its 2026 guidance to $12 to $14. Tesla’s premium therefore depends almost entirely on autonomy, which supports our modest upside call.
| Company | Trailing P/E | Key Metric |
|---|---|---|
| Amazon | 36x | AWS growth 37% |
| Walmart | 41x | Ad growth 38% |
| Tesla | 391x | Operating margin 1.4% |
| GM | 27x | Q2 adj. EPS $3.57 |
Amazon Has the Clearer Path to Upside
Our model rates both stocks buy. For Amazon, I see 28.65% upside with 70% confidence. For Tesla, I see 8.12% upside with 90% confidence. Amazon wins on growth you can see in reported results.
My view on Amazon holds as long as AWS demand continues covering capex. Tesla needs to show margins recovering in its upcoming earnings report. Amazon’s growth is already reported, while Tesla’s still depends on performance.
Amazon and Tesla Price Prediction 2026-2030
| Year | Amazon | Tesla |
|---|---|---|
| 2026 | $276.33 | $392.50 |
| 2027 | $332.67 | $405.69 |
| 2028 | $389.65 | $425.04 |
| 2029 | $438.62 | $452.37 |
| 2030 | $506.28 | $481.45 |
Tesla’s figures for 2028 through 2030 extend our base case’s 6.43% annualized return.
All of these projections assume each company continues performing as it does today. AI capex returns, Robotaxi regulation and Optimus expansion could move them sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.