Prediction: Eli Lilly Stock Could Be a Long-Term Winner for Investors
Eli Lilly just crushed earnings again and sits within striking distance of its all-time high, but a looming price war with Novo Nordisk and a dangerously concentrated revenue base raise real questions about how long the momentum holds.

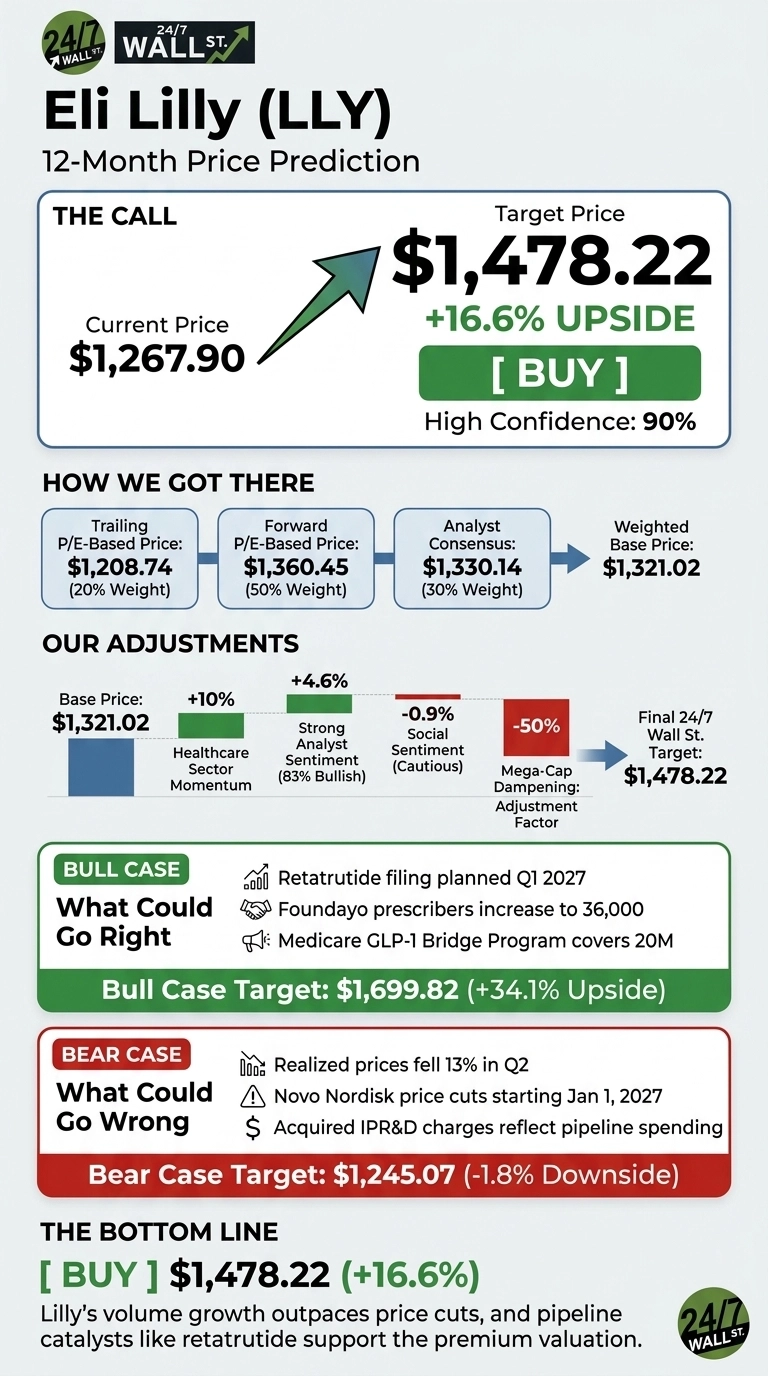
The 24/7 Wall St. price target for Eli Lilly (NYSE:LLY | LLY Price Prediction) is $1,478.22 over the next 12 months. Shares trade near $1,267.90 at noon, so the target means 16.6% upside. Our model rates Lilly a buy with 90% confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $1,267.90 |
| 24/7 Wall St. Price Target | $1,478.22 |
| Upside | 16.6% |
| Recommendation | BUY |
| Confidence Level | 90% |
That confidence reflects earnings momentum few mega-caps can match. Lilly has beaten EPS estimates for five straight quarters, raised full-year guidance, and holds the next major obesity catalyst in retatrutide. The incretin business should carry earnings well into 2027, according to the model.
Lilly Rallies Toward Its 52-Week High After Another Guidance Raise
Lilly gained 4.89% in today’s session after healthcare stocks including Lilly, Merck and AbbVie rallied Wednesday. Shares are up 6.66% over a week, 11.39% over a month, 18.55% year to date and 57.07% over the past year. The stock sits 1.9% below its 52-week high of $1,292.65 and 62.8% above its low of $778.94.
In Q2, revenue rose 47.67% to $22.97 billion, beating the $20.69 billion estimate, while EPS of $8.38 exceeded the $6.58 forecast. Mounjaro sales grew 91% to $9.94 billion. Management raised 2026 revenue guidance to $85 billion to $87 billion.

Why Bulls See $1,700 Ahead
Retatrutide is the main catalyst, with a U.S. filing planned for Q1 2027. On the Q2 call, Lilly’s CEO said, “We have a pretty large lead over any competitors with a triple acting medicine.” The oral GLP-1 Foundayo grew from about 8,000 to 36,000 prescribers, and the Medicare GLP-1 Bridge Program opened coverage to 20 million eligible Americans.
Wall Street agrees: 25 analysts rate the stock a buy or strong buy, with a consensus target of $1,330.14. Jim Cramer said in June he is “sticking with Lilly for the long haul.” Our bull case reaches $1,699.82, or 34.1% upside.

Pricing Pressure Is the Risk to Respect
Realized prices fell 13% in Q2, and Novo Nordisk (NYSE:NVO) plans to cut Wegovy’s list price by about 50% starting January 1, 2027. Mounjaro and Zepbound produced $14.9 billion of Q2 revenue, a heavy concentration, and guidance excludes pharma tariffs.
Volume growth of 60% more than covered the price cuts, though. The $2.78 billion in acquired R&D charges reflect pipeline spending that won’t repeat. The bear case of $1,245.07 sits only 1.8% below today’s price.
Lilly Outgrows Novo Nordisk and Pfizer by a Wide Margin
Novo Nordisk is Lilly’s direct GLP-1 rival. Its Q2 adjusted sales grew just 7% at constant currency, and it still guides to a 2026 decline of 0% to 6%. That gap explains why investors pay up for Lilly.
Pfizer (NYSE:PFE) shows the valuation trade-off. It trades at a P/E of about 21, compared with Lilly’s trailing 40 and forward 24. Pfizer’s revenue grew only 2.6%, however, as COVID sales faded.
| Company | Latest Quarterly Revenue Growth | Operating Margin |
|---|---|---|
| Eli Lilly | 47.67% | 54.2% |
| Novo Nordisk | 7% (adjusted, CER) | 41.3% |
| Pfizer | 2.6% | 24.7% |
Lilly’s forward multiple sits only a few turns above Pfizer’s P/E, even though Lilly is growing far faster. Against that background, our 24/7 Wall St. price target looks reasonable.
Lilly’s Growth Justifies the Premium
The 24/7 Wall St. price target of $1,478.22 carries a buy rating at 90% confidence. What tips the scale is volume growth outpacing price cuts.
The bull case strengthens if retatrutide’s filing stays on schedule and Foundayo keeps gaining share. The outlook weakens if realized prices drop faster after Novo’s 2027 list-price cuts. For now, Lilly’s earnings support a higher stock price.

Eli Lilly Price Prediction 2026-2030
The model projects where Lilly could trade if current growth trends and market conditions hold.
| Target Date | Base Case | Bull Case |
|---|---|---|
| December 2026 | $1,243.28 | $1,284.43 |
| October 2027 | $1,478.89 | $1,591.40 |
| October 2028 | $1,713.01 | $1,937.42 |
| October 2029 | $1,894.05 | $2,231.53 |
| October 2030 | $2,074.95 | $2,492.66 |
Lilly would need to keep executing on its incretin strategy for these projections to hold. Retatrutide’s approval timing and U.S. drug-pricing policy could move results sharply in either direction from these tracks.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.