Eli Lilly’s Next Trillion-Dollar Opportunity May Go Beyond Weight-Loss Drugs
Mounjaro and Zepbound built Lilly into a trillion-dollar company, but a surge in oncology, immunology, and neuroscience revenue hints that the real growth story is just getting started.

The 24/7 Wall St. price target for Eli Lilly (NYSE:LLY | LLY Price Prediction) is $1,572.21 over the next 12 months. That implies 22.65% upside from the model’s starting price of $1,281.91.
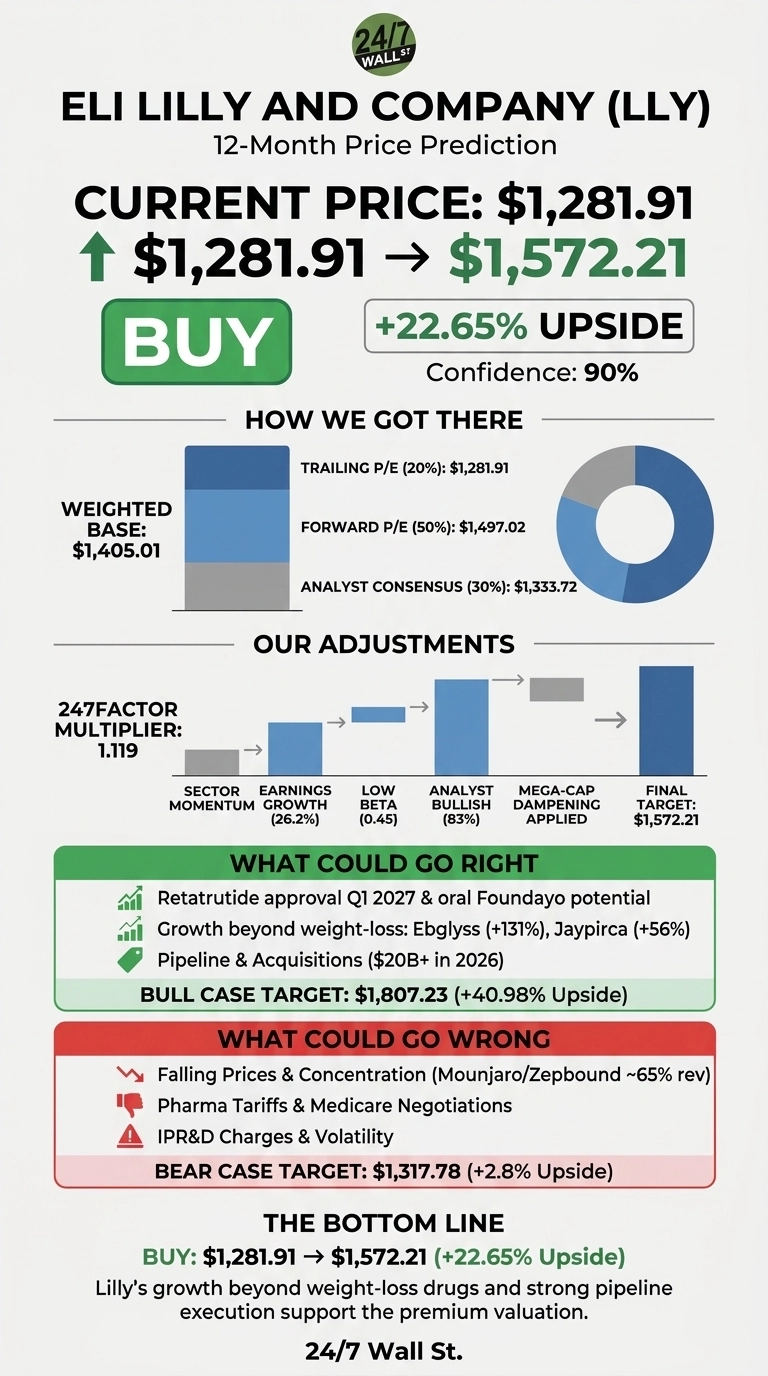

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $1,281.91 |
| Price Target from 24/7 Wall St. | $1,572.21 |
| Upside/Downside | 22.65% |
| Model Rating | BUY |
| Confidence Level | 90% |
Mounjaro and Zepbound took Lilly past a $1.146 trillion market cap. I think the next leg of growth could come from somewhere else.
In Q2, Lilly’s Key Products in immunology, oncology and neuroscience grew 121% year over year. Our confidence is high. The rating rests on a streak of earnings beats, guidance that has gone up, and 83% bullish analyst opinion.
Steady Gains Follow a Blowout Quarter and a Busy October
Lilly shares rose 0.3% this past week. They are up 8.8% over the past month, 20.39% year to date and 56.79% over the past year. The 52-week range runs from $804.56 to $1,321.21.
Q2 revenue came in at $22.97 billion, up 47.7%. EPS was $8.38, well above the $6.58 estimate. Lilly also raised its 2026 revenue guidance to $85 billion to $87 billion.
October’s news has mostly been about drugs outside weight loss. The FDA expanded Jaypirca’s label to cover previously untreated CLL/SLL. Lilly also presented olomorasib lung cancer data at ESMO.
On top of that, retatrutide produced more than double the weight loss of Ozempic’s highest approved dose in a head-to-head trial released today. Goldman Sachs and Bank of America both raised their price targets this month.
Why Bulls See $1,800 and Beyond
The bull case is $1,807.23. Lilly plans to file retatrutide for approval in Q1 2027. Foundayo, its oral GLP-1, could reach patients who do not want shots. Growth beyond weight loss is already visible: Ebglyss rose 131% and Jaypirca rose 56%.
In early data, the VERVE-102 gene editor cut LDL cholesterol by up to 62%. Lilly has also spent about $20 billion on acquisitions in 2026. Analyst ratings stand at 6 Strong Buy and 19 Buy.

Falling Prices and Revenue Concentration Are the Risks to Watch
The bear case is $1,317.78. Realized prices fell 13% in Q2. Mounjaro and Zepbound together bring in about 65% of revenue. Possible pharma tariffs and Medicare price negotiations add more pressure.
Still, volume grew 60%, and gross margin reached 85.8%. Reported earnings were also held down by $2.78 billion in one-time acquisition charges (acquired IPR&D). That spending is paying for the diversification described above.

Is Lilly Worth Its Premium Over Novo Nordisk and Merck?
| Company | Forward P/E | Market Cap |
|---|---|---|
| Eli Lilly | 32x | $1.146 trillion |
| Novo Nordisk | 12x | $172.6 billion |
| Merck | 15x | $349.9 billion |
Novo Nordisk (NYSE:NVO) competes with Lilly directly in GLP-1 drugs. Its quarterly earnings fell 20.6% year over year, so its low multiple looks more like a value trap than a bargain.
Merck (NYSE:MRK) is a useful comparison because it is the cancer-drug leader Lilly hopes to become. Its quarterly revenue grew just 5.1%. Given how much faster Lilly is growing, I think the peer comparison makes our target look reasonable.
Lilly’s Growing Pipeline Tips the Scale
I see a 24/7 Wall St. price target of $1,572.21, a buy rating and 90% confidence. Lilly’s growth outside obesity drugs tips the scale for me.
The outlook improves if retatrutide is approved on schedule and the cancer and immunology drugs keep growing faster than 50%. I would be more conservative if price cuts start to outpace volume growth.
Looking further ahead, here is where our model projects Lilly could trade if current growth and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $1,331.00 |
| 2027 | $1,581.07 |
| 2028 | $1,807.24 |
| 2029 | $2,041.58 |
| 2030 | $2,193.77 |
The estimates rest on Lilly continuing to execute on its current strategy. The results could land well above or below these figures depending on retatrutide’s approval and on how far US drug prices fall.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.