Prediction: The Weight-Loss Drug Boom Could Be Just the Beginning for Lilly
Eli Lilly just crushed earnings and raised guidance, yet the most compelling part of its story has almost nothing to do with what already happened. The real question is whether the weight-loss boom is a peak or a launching pad…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

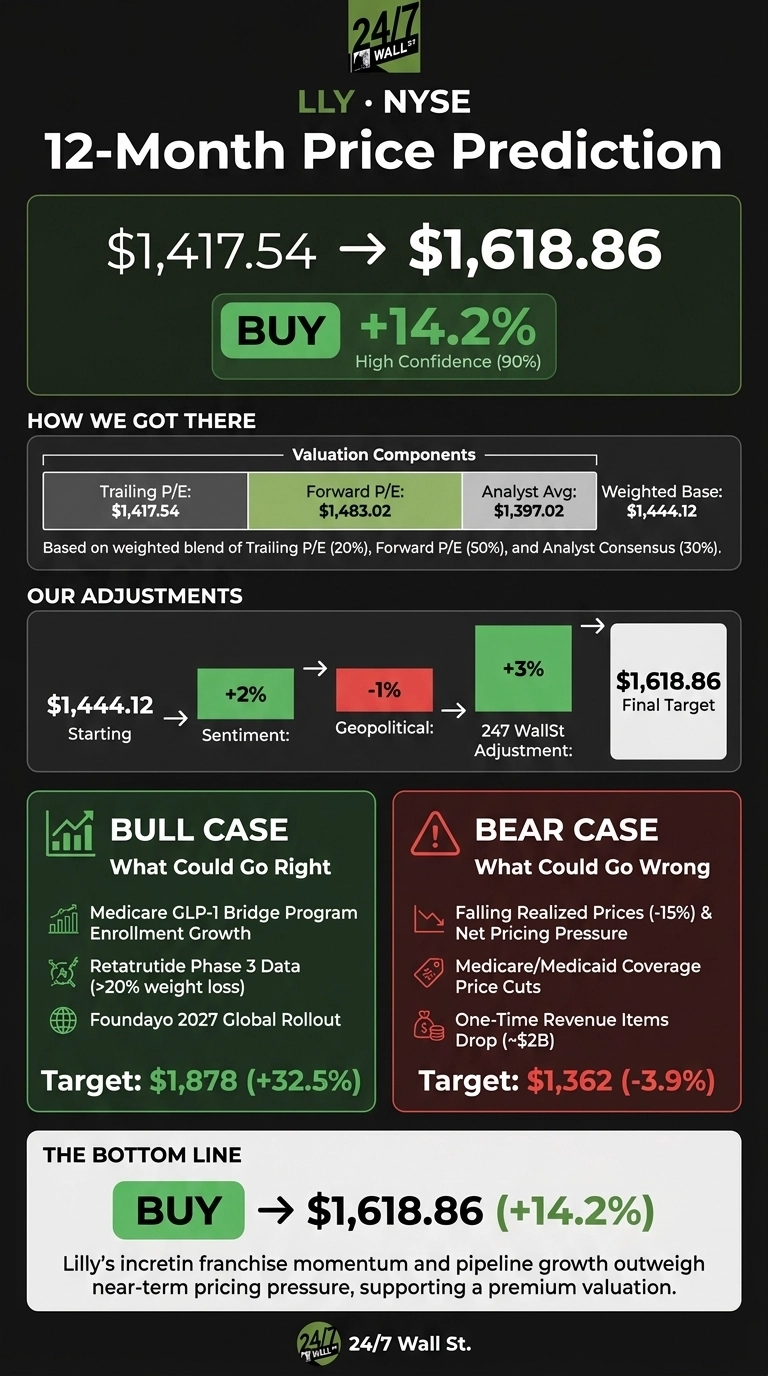
Eli Lilly (NYSE:LLY | LLY Price Prediction) closed its last full session at $1,417.54 and changed hands near $1,402.99 this afternoon. The 24/7 Wall St. price target for Lilly is $1,618.86 over the next 12 months. That implies 14.2% upside from the close, and our model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $1,417.54 |
| Price Target from 24/7 Wall St. | $1,618.86 |
| Upside/Downside | 14.2% |
| Recommendation | BUY |
| Confidence Level | 90% |

Lilly just raised full-year revenue guidance to $91 billion to $92 billion, up from $85 billion to $87 billion. Management also says the incretin market is barely tapped.
Tirzepatide volume rose 53% worldwide, and the oral drug Foundayo heads toward a global rollout in 2027. That makes today’s weight-loss franchise look like the foundation of a multiyear run, and that thesis drives our target.

Third-Quarter Beat Lifts Lilly Near Its 52-Week High
The stock has risen 10.17% over the past week, 21.25% over the past month and 31.18% year to date. It now sits near its 52-week high of $1,449.68, well above the $847.83 low.
Third-quarter revenue reached $24.40 billion, up 38.61% and above the $22.62 billion consensus. Non-GAAP EPS of $7.48 exceeded the $6.67 estimate even after $4.57 per share of acquired R&D charges. Mounjaro brought in $10.72 billion (+65%) and Zepbound $5.35 billion (+49%).
Why Bulls See $1,878 Ahead
Our bull case reaches $1,878.74, a 32.54% gain. Medicare’s GLP-1 Bridge Program has already reached more than half a million people, and 7 out of 10 new patients started on a Lilly drug.
In Phase 3, retatrutide delivered 20% to 21% weight loss compared with 9.4% for semaglutide. Lilly’s chief executive called it “the largest new category expansion in the history of the pharmaceutical industry.”
Wall Street largely agrees, with 6 Strong Buy and 19 Buy ratings.

Falling Prices Are the Risk Worth Watching
Realized tirzepatide prices fell 15%, and management expects about $2 billion of one-time 2026 revenue items to drop out. More Medicare and Medicaid patients also means lower net prices.
The consensus target of $1,403.64 sits below the last close, and our bear case points to $1,362.12. In Lilly’s favor, volume growth is exceeding price cuts. The $4.18 billion in IPR&D charges also paid for pipeline deals such as AtaiBeckley.
Lilly’s Premium Over Novo Nordisk and Merck Looks Earned
Novo Nordisk (NYSE:NVO) is Lilly’s direct GLP-1 rival. The stock trades at 12x forward earnings, but quarterly revenue grew only 2.1%, and Novo plans to cut Wegovy’s list price by about 50% in 2027.
Merck (NYSE:MRK) is a useful large-pharma benchmark. The stock trades at 16x forward earnings on 4.7% revenue growth while Keytruda sales decline.
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Eli Lilly | 30x | 38.6% |
| Novo Nordisk | 12x | 2.1% |
| Merck | 16x | 4.7% |
Lilly carries a higher forward multiple than its peers, yet it is growing far faster. Measured against that gap, the 24/7 Wall St. price target looks reasonable.
Lilly’s Growth Engine Earns the Premium
The 24/7 Wall St. price target of $1,618.86 carries a buy rating with 90% confidence. Volume keeps outpacing price cuts.
The bull thesis strengthens if Foundayo’s 2027 rollout and Bridge enrollment keep growing. I’d be more cautious if 2027 guidance in January shows pricing erasing volume gains. At this point, the data favor the bulls.
Eli Lilly Price Prediction 2026-2030
Looking further out, here is where the 24/7 Wall St. price target model sees Lilly trading if current growth and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $1,445.61 |
| 2027 | $1,618.86 |
| 2028 | $1,779.84 |
| 2029 | $1,943.88 |
| 2030 | $2,064.74 |
The projections rest on Lilly continuing to execute on its current strategy. The biggest key factors are retatrutide’s regulatory path and how far U.S. obesity drug prices fall as coverage expands.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.