Merck’s Pipeline Could Be Its Next Big Growth Driver. Its Latest Earnings Offer a Clue.
Merck just posted its sixth straight earnings beat and its CEO is targeting $70 billion in mid-2030s revenue, yet the stock carries a looming patent cliff that could reshape everything. Whether the pipeline saves the story or the bears win…

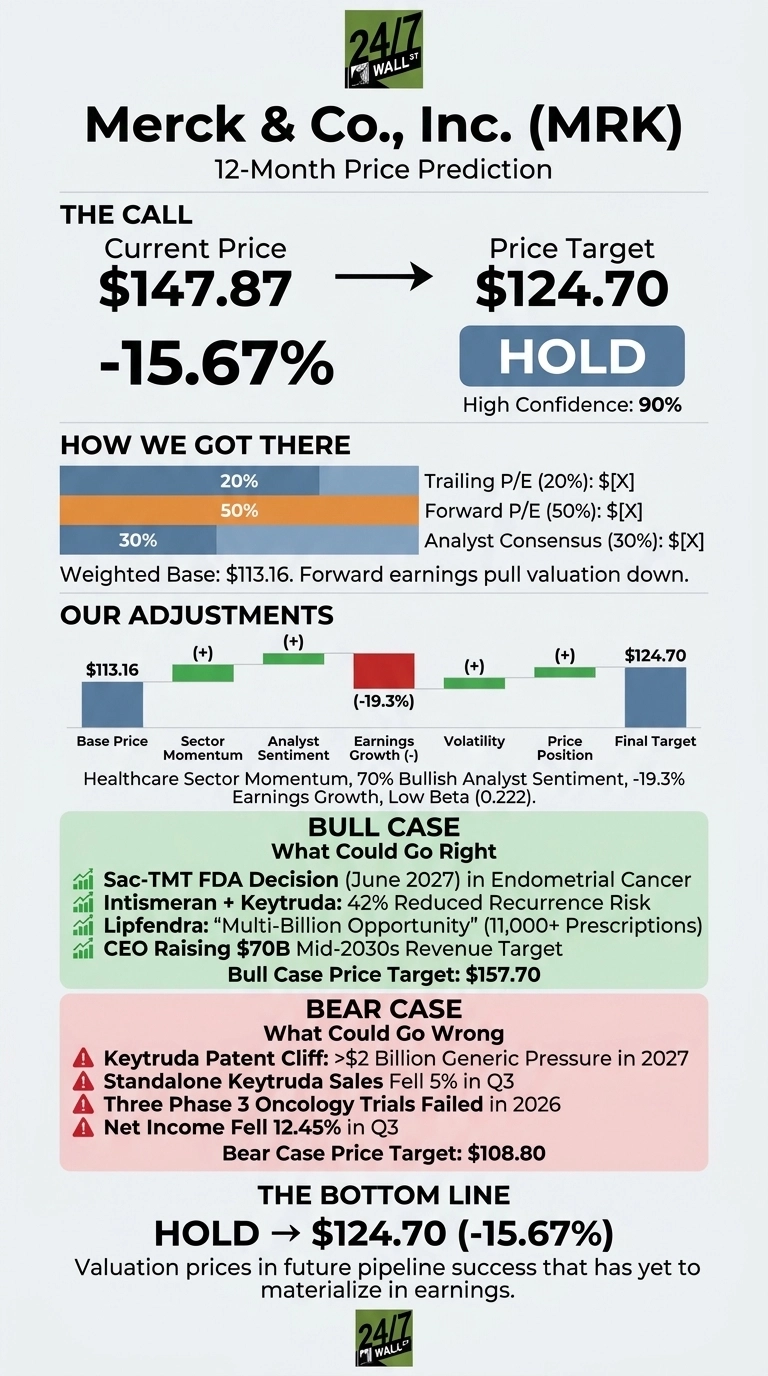
Merck (NYSE:MRK | MRK Price Prediction) just posted its sixth consecutive earnings beat and raised its 2026 profit outlook. The 24/7 Wall St. price target stands at $124.70.
Against the latest price of $147.87, that means 15.67% downside. This stock earns a hold rating, and the model has high confidence in that call.
| Metric | Value |
|---|---|
| Current Price | $147.87 |
| Price Target from 24/7 Wall St. | $124.70 |
| Upside/Downside | -15.67% |
| Recommendation | HOLD |
| Confidence Level | 90% |

The gap comes down to valuation. Merck has gained 75.82% over the past year, while 2026 earnings are taking in large acquisition charges.
Why We Could Be Wrong
Our target sits below today’s price, and the bull case is strong. Sac-TMT has a June 15, 2027 FDA decision date in endometrial cancer.
Chief Executive Rob Davis also said Merck now expects to raise its $70 billion mid-2030s revenue opportunity. Read our target as one datapoint among many. The bull case below lays out how Merck could beat it.

Six Straight Beats Lift Merck Within Reach of Its High
Third-quarter adjusted EPS of $2.49 exceeded the $2.09 consensus, and revenue of $18.09B came in above the $17.35B estimate. CNBC linked the higher outlook to the strength of the new subcutaneous Keytruda (CNBC), and Keytruda Qlex added $830M in sales. Winrevair rose 93% and Welireg climbed 56%. Merck now guides to non-GAAP EPS of $2.77-$2.82.

The stock is up 13.41% for the quarter and 43.41% YTD. It slipped 0.94% over the past month. Shares sit 5.21% below the $156 52-week high and 85.6% above the low.
Pipeline Wins Could Push Shares Toward $158
The bull case reaches $157.70, close to the Wall Street consensus target of $159.76. Analyst ratings include 5 Strong Buy, 14 Buy and 8 Hold, with no Sells.
In Phase 3, sac-TMT cut the risk of death by 32%. Intismeran plus Keytruda reduced the risk of recurrence or death by 42%. Lipfendra, Merck’s new oral cholesterol drug, drew more than 11,000 prescriptions in the quarter. Management called it a “multi-billion opportunity”.

Keytruda’s Patent Cliff Sets Up a $108.80 Downside Case
Bear-case estimates land at $108.80. Standalone Keytruda sales fell 5%, and management expects more than $2 billion of generic pressures in 2027. About $550 million of third-quarter sales came from purchase timing, and most of that should reverse.
Three Phase 3 oncology trials also failed earlier this year. Net income fell 12.45%, but a one-time $400M SciBrunch charge is part of the fall. Management also expects gross margin to rise as a Keytruda royalty rolls off.
How Merck Compares to Pfizer and Eli Lilly
Pfizer (NYSE:PFE) is the closest match: another mega-cap trying to overcome its patent cliffs with oncology launches. Its P/E is 22, and Merck’s forward P/E is 16. Pfizer’s 2026 EPS guidance of $2.80 to $3.00 is similar to Merck’s, yet its market value of $170.7B is far smaller. That gap suggests investors are already paying for Merck’s pipeline.
Eli Lilly (NYSE:LLY) shows what a premium valuation requires. Lilly’s third-quarter revenue grew 38.61%, compared with 4.68% for Merck. Merck’s mid-single-digit growth supports a defensive multiple, which makes our target look reasonable.
| Company | Market Cap | Latest Quarterly Revenue Growth |
|---|---|---|
| Merck | $361.02B | 4.68% |
| Pfizer | $170.7B | 2.6% |
| Eli Lilly | $1.22T | 38.61% |
Pipeline Approvals Will Decide Merck’s Next Move
The 24/7 Wall St. price target of $124.70 carries a hold rating with 90% confidence. The deciding factor is valuation: the stock already prices in pipeline success that has yet to show up in earnings.
I would grow more constructive if sac-TMT wins approval and Merck formally raises its 2030s revenue target. I would stay cautious if 2027 generic losses outpace new launches.
| Year | Price Target from 24/7 Wall St. | Bull Case |
|---|---|---|
| 2026 | $124.70 | $157.70 |
| 2027 | $124.43 | $155.02 |
| 2028 | $118.39 | $165.70 |
| 2029 | $117.74 | $177.88 |
| 2030 | $118.89 | $187.20 |
The 2026 row is our 12-month target, and later years reflect October points on the model’s path. They rest on Merck continuing to execute its current strategy. Pipeline approvals could push results toward the bull column, while a steeper Keytruda fall would add downside.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.