Costco Stock: Earnings Growth Could Shape the Next Big Move
Six straight earnings beats have pushed Costco shares up 20% this year, yet a 49x trailing P/E leaves little room for error. One metric could decide whether the rally keeps running or finally stalls.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
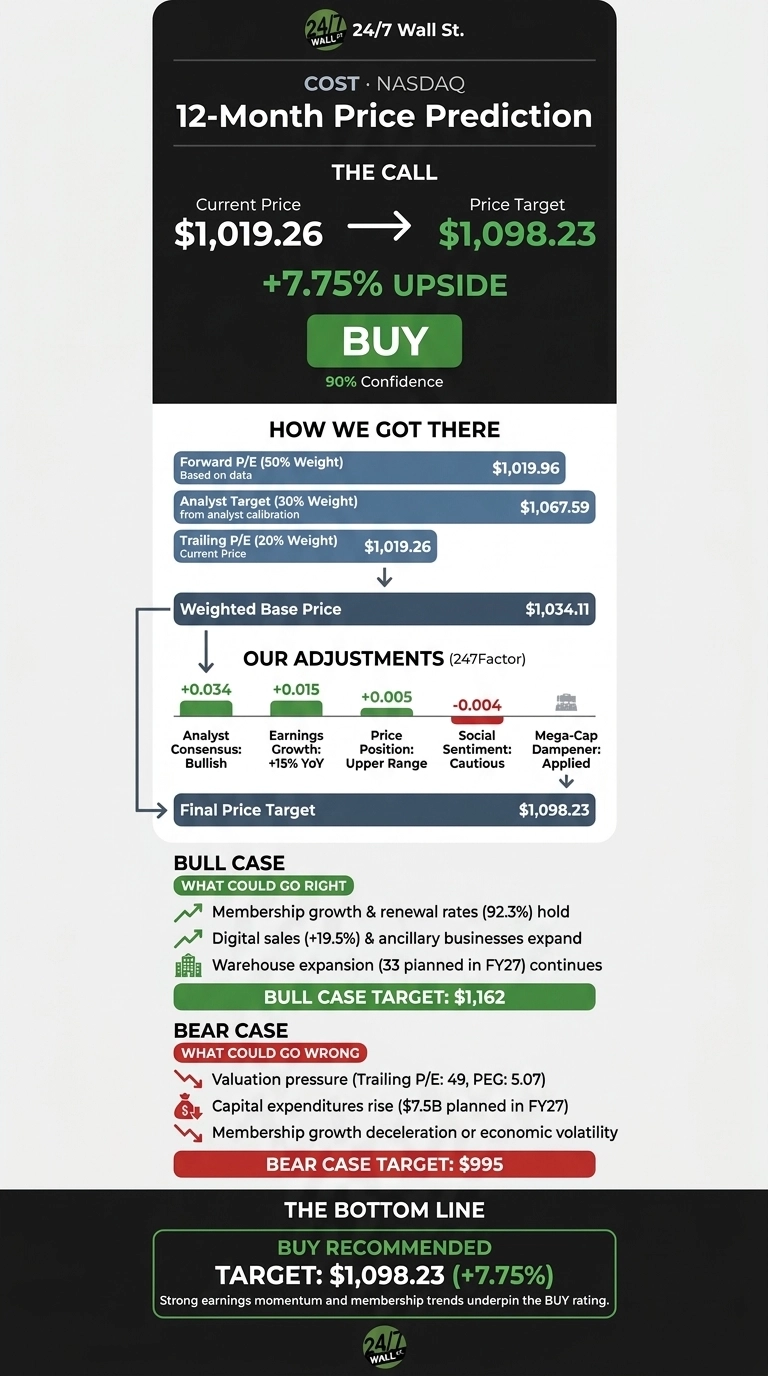
The 24/7 Wall St. price target for Costco (NASDAQ:COST | COST Price Prediction) is $1,098.23. That represents 7.75% upside from the $1,019.26 close. The stock earns a buy rating with 90% confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $1,019.26 |
| The 24/7 Wall St. Price Target | $1,098.23 |
| Upside/Downside | 7.75% |
| Recommendation | BUY |
| Confidence Level | 90% |
Costco has now beaten EPS estimates 6 consecutive quarters. Fiscal 2026 revenue grew 10.14% to $303.15 billion. Our model treats that earnings consistency as the variable most likely to drive the next move. Confidence is high because the trailing, forward and analyst-based valuations group tightly together.
Six Straight Beats Fuel a 20% Year-to-Date Run
Shares rose 4.27% over the past week, 12.37% over the past month and 20.49% year to date. At the latest close, the stock sits about 6.8% below its 52-week high of $1,093.14 and roughly 21.5% above its $839.11 low.
The fiscal fourth quarter, reported September 24, set the tone. EPS of $6.75 beat the $6.53 estimate. Revenue of $95.72 billion topped the $94.85 billion estimate and rose 11.1%. Excluding a $0.15 nonrecurring tariff refund benefit, EPS still grew 12.4%.
Digitally enabled comparable sales rose 19.5% as DoorDash (NASDAQ:DASH) and Uber Eats delivery from Uber (NYSE:UBER) expanded nationwide. The stock gained 7.52% in the 30 days after that report.

Why Bulls See $1,162 Within Reach
The bull case reaches $1,162.37. Membership quality drives it. Paid executive members reached 42.3 million, up 9.4%, and the U.S. and Canada renewal rate hit 92.3%. Management plans 33 openings in fiscal 2027, while the SG&A rate fell to 8.94% from 9.21%.
On the call, then-CFO Gary Millerchip pointed to “record high executive penetration, guest engagement, and digital engagement” as signs of loyalty. Analysts lean bullish, with 4 Strong Buy and 20 Buy ratings and a consensus target of $1,067.59.

What Could Stall the Rally
The bear case sits at $995.32. Valuation is the pressure point, with a trailing P/E of 49 and a PEG ratio of 5.07. After the fiscal Q2 2025 miss, shares fell 6.07% on earnings day.
Total paid members grew only 3.8%, and capex is set to rise to about $7.5 billion. Management expects capex growth to slow after fiscal 2027. That spending also funds the warehouse pipeline that creates future fee income.
How Costco Compares to Walmart and BJ’s
Walmart (NASDAQ:WMT) is the biggest scale rival, and its Sam’s Club unit competes directly for warehouse members. Walmart trades near 45x earnings, a smaller premium than Costco’s, but its latest revenue grew only 5.94%.
BJ’s Wholesale Club (NYSE:BJ) is the closest pure-play club. It beat EPS estimates by 16.52%, but its comparable sales excluding gas rose just 3.1%.
| Company | Latest Quarter Revenue Growth | Membership Fee Growth |
|---|---|---|
| Costco | 11.1% | 7.3% |
| Walmart | 5.94% | 17% |
| BJ’s | 15.73% | 9.9% |
Walmart’s high multiple, despite slower sales growth, suggests the 24/7 Wall St. price target is reasonable.
Earnings Momentum Tips the Scale Toward Buy
The 24/7 Wall St. price target of $1,098.23 supports a buy at 90% confidence. Steady double-digit earnings growth is what underpins the call.
The bull thesis strengthens if comparable sales excluding gas stay in the 6% to 7% range. The thesis weakens if membership growth slows further. Until that happens, the earnings case remains intact.

Costco Price Prediction 2026-2030
This is where the model projects Costco could trade if current trends hold.
| Year | The 24/7 Wall St. Price Target |
|---|---|
| 2026 | $1,029.40 |
| 2027 | $1,098.23 |
| 2028 | $1,165.48 |
| 2029 | $1,256.10 |
| 2030 | $1,294.14 |
These estimates rest on Costco continuing to execute on warehouse growth and membership. Faster openings in Asia could push results above these targets, while slower membership additions could pull them below.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.