3 Reasons Keep Me Buying SanDisk at $795

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
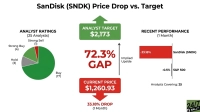
My position in SanDisk (NASDAQ:SNDK | SNDK Price Prediction) keeps growing, and the stock’s slide to $797.24 has only made me add faster. Shares fell 38.64% in a month. Over that same month, the company reported quarterly revenue of $11.031 billion[1], up 377.9% year over year.
Three factors drive my thinking. SanDisk makes the NAND flash that AI inference needs to hold its working memory. It sells much of that output under multi-year contracts. And it returns the cash back to shareholders like me.
Reason One: A Forward Multiple Near 3x Earnings
Management guided fiscal Q2 non-GAAP EPS to $55.00-$57.00[1] on a pre-split basis. If I annualize that range at today’s price, SanDisk trades at roughly 3x to 4x forward earnings. The trailing P/E is about 10. That price assumes margins will fall. Management, meanwhile, guided non-GAAP gross margin to 84.5%-85.5%[1], which includes small price increases.
Reason Two: Contracts Lock In Demand Through 2028
Under its New Business Model (NBM) agreements, SanDisk has committed about 50% of bits[2] for fiscal 2027 and about two-thirds for fiscal 2028. Management also said, “Our NBM pipeline exceeds our supply throughout the end of the decade.”[2] Its largest customers are generally investment-grade companies. Datacenter revenue reached $4.802 billion[1], up 61% sequentially. Management expects datacenter bit demand to grow about 40%[2] in calendar 2027.
Reason Three: Cash Comes Straight Back to Shareholders
SanDisk generated $5.7 billion[2] of adjusted free cash flow last quarter and spent $5.0 billion[1] buying back about 3.2 million shares. That works out to roughly 2.2% of shares outstanding in one quarter. The company still has $15.5 billion left on its authorization, carries no debt and holds $5.1 billion[2] in cash. SanDisk pays no dividend. For my retirement account, a shrinking share count does that job.
Why I Pass on Micron and Western Digital
The obvious alternative is Micron Technology (NASDAQ:MU). It is a great business, but its $806 billion market cap equals about 13x its fiscal 2026 free cash flow. Micron also spent $30.712 billion on capex that year. SanDisk’s capex last quarter was $54 million[1].
Western Digital (NASDAQ:WDC), SanDisk’s former parent, has a $106 billion market cap. That is close to SanDisk’s $113.44 billion. Yet Western Digital’s latest quarter brought in $4.381 billion in revenue and $1.377 billion in free cash flow. SanDisk brought in $11.031 billion[1] and $6.309 billion.
Risk That Could Hurt This Position
NAND is a cyclical industry, and the market clearly fears the next downturn. Consumer revenue already fell 39%[1] year over year as buyers pushed back on higher prices. SanDisk also relies on its manufacturing partner Kioxia, and management warned that fiscal Q3 is historically the weakest quarter. A sharp drop in pricing would hit earnings hard.
That risk has not changed my view. About 60%[2] of last quarter’s growth came from volume rather than price, and contracts cover most of the next two years of supply.
Why My Buy Button Stays Active
High Bandwidth Flash samples arrive next calendar year[2], and management leaves that product out of its long-term model. I get contracted demand, a debt-free balance sheet and an aggressive buyback at a price that assumes the cycle has already ended. As long as the cash keeps coming in this fast, I will keep buying.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.