The Real Cost of Retiring in The Villages, Florida, on a Single Pension
We get a version of this question almost every week. Someone has a single pension and has been told The Villages is the affordable answer in Florida. They want to know if the math actually works on one income. Here…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
We get a version of this question almost every week. Someone has a single pension and has been told The Villages is the affordable answer in Florida. They want to know if the math actually works on one income. Here is what it really takes.
What The Villages actually costs a single retiree
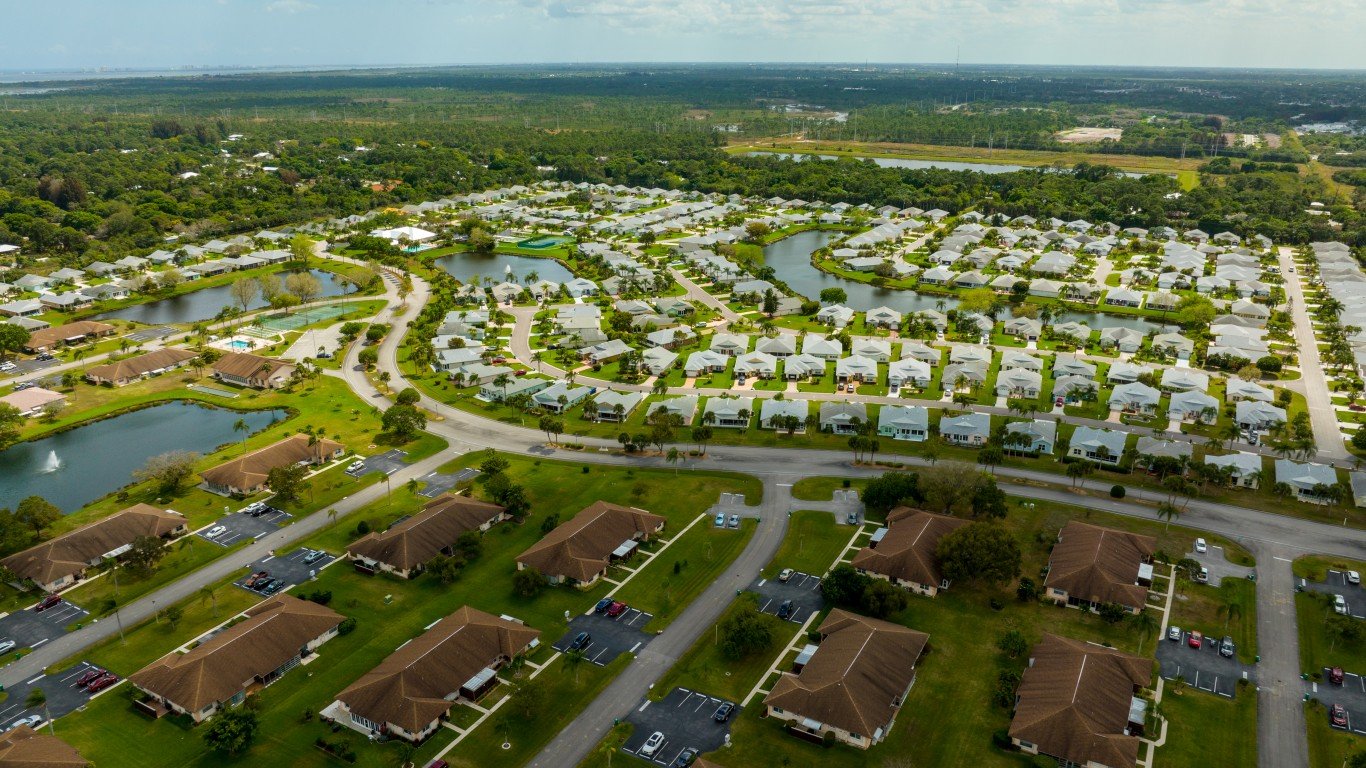
Start with the house. A patio villa or small courtyard villa in the older sections runs in the low to mid $300,000s, while a designer home north of 466A pushes past $500,000. The overall median sale price across The Villages came in at $355,000 for the three months ending May 2026, down 2.3% year-over-year as the market cooled from its pandemic-era highs. That softening extended into summer: Realtor.com listing data for August 2026 showed the median listing price at $377,784, down nearly 2% from the same month in 2025, with homes sitting on the market roughly twice as long as they did in 2022. For a buyer, price trends are working in their favor. Assume a single retiree pays cash for a roughly $325,000 villa. Property taxes in Sumter County land near $3,500 a year on that value, and Florida homeowners insurance has been a volatile budget line for several years running.
Inland buyers catch a meaningful break on premiums. Sumter County sits well removed from the coast, so annual premiums on a $300,000 home average closer to $1,620 to $2,200, far below the statewide headline figures. A wind-included policy on a modest home is realistic in the $2,000 to $2,800 range. Florida’s tort reform push, which eliminated one-way attorney fees and curtailed assignment-of-benefits abuse through 2022 and 2023 legislation, has produced genuine rate relief. Citizens Property Insurance, the state’s insurer of last resort, received an 8.7% average statewide rate cut in 2026 from the Florida Office of Insurance Regulation, the first reduction since 2015 and larger than the 2.6% Citizens originally proposed. Private carriers followed suit: State Farm filed for a 10.1% statewide reduction and Florida Peninsula filed for an 8.2% cut, both reflecting the same improved market conditions.
Then come the hidden line items. The monthly amenity fee runs around $200, indexed annually to CPI. Most homes carry a CDD bond, infrastructure debt baked into the property at closing. Depending on the home and how long the bond has been running, remaining principal can range from $10,000 to $30,000, with annual payments of $1,200 to $2,500 until the debt is retired. A fire assessment and trash collection add a few hundred more. The non-tax community carrying cost runs roughly $4,500 a year before a single light is turned on.
Healthcare at 65 means Medicare. Part B costs $202.90 a month in 2026, up $17.90 from $185 in 2025, with a $283 annual deductible. Add a Medigap Plan G (roughly $160 to $200 a month in central Florida for a 65-year-old), a Part D drug plan around $40, and dental and vision out of pocket, and the annual healthcare tab reaches $5,800 to $6,500 before any serious illness.
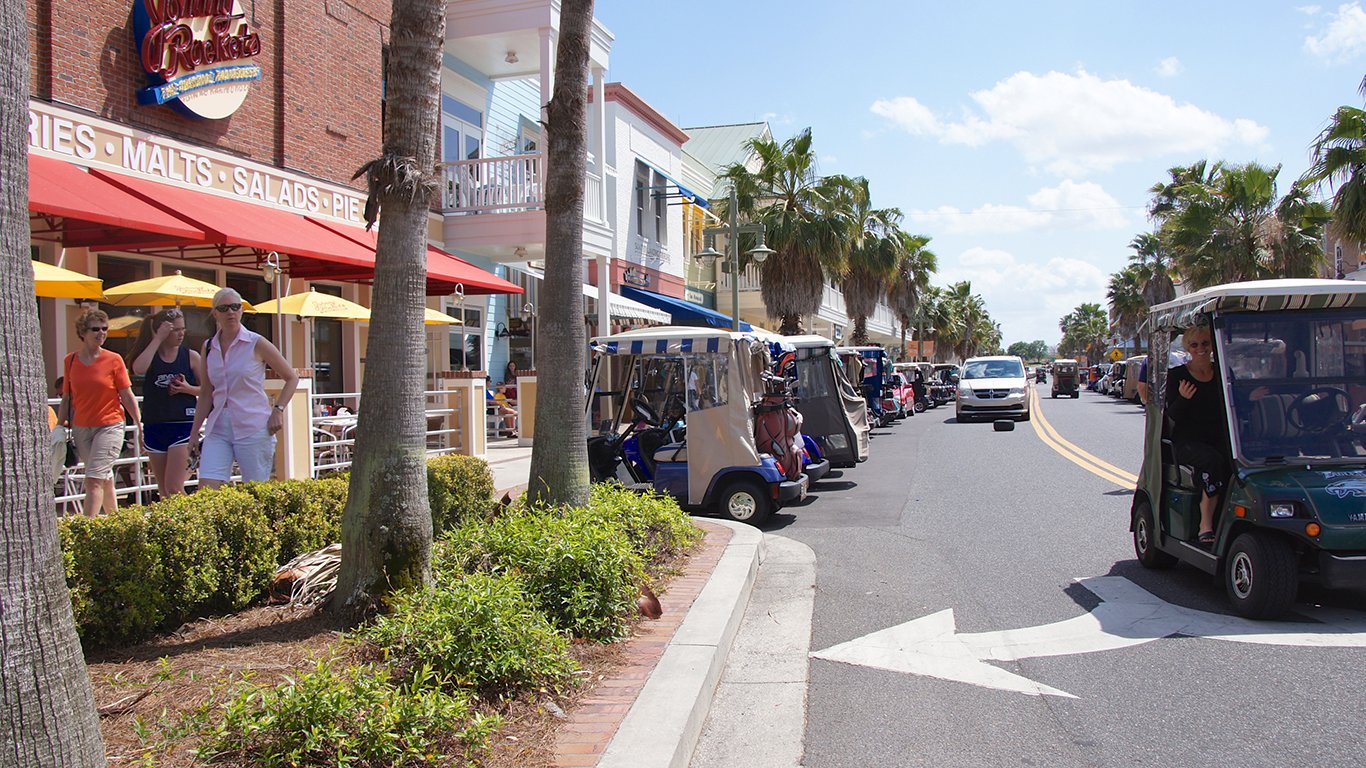
Food for one on the USDA Moderate plan runs about $4,800 a year, and Villages residents eat out regularly, so budget another $3,000 for the town squares. Electric in a small Florida home with summer AC averages $180 a month, and water and sewer add around $80. A car remains non-negotiable for medical appointments and warehouse runs even with a golf cart in the garage. Florida regular gasoline averaged around $4.28 a gallon at its September 2026 peak before pulling back to roughly $3.97 by early October, according to EIA data. Between fuel, insurance, registration, and the golf cart itself (purchase, batteries every five to seven years, maintenance), transportation lands around $5,000 to $5,500 a year.
A working all-in budget for a single retiree who owns the home outright:
- Property tax, insurance, amenity, CDD, utilities: about $13,500
- Healthcare (Medicare + Medigap + Part D + dental): about $6,200
- Food and dining: about $7,800
- Transportation: about $5,000
- Home maintenance, replacements, gifts, travel, reserves: about $9,000
- Federal income tax on pension and withdrawals: about $3,500
That totals roughly $45,000 a year, call it $45,500 to be conservative. The Bureau of Labor Statistics reports average household spending at $78,535 for 2024, but a single, mortgage-free retiree in The Villages can credibly run well below that all-household national figure.
Does one pension actually clear it
A single retiree claiming Social Security at full retirement age in 2026 averages just over $25,000 a year. The SSA’s August 2026 Monthly Statistical Snapshot put the average retired-worker benefit at $2,087.52 a month, a figure that has crept upward steadily since the 2.8% COLA took effect in January 2026. One additional tailwind: the SSA announced on October 14, 2026 that benefits will rise another 3.6% in January 2027, the largest increase since 2023, lifting the average retired-worker benefit to roughly $2,170 a month. Florida has no state income tax, so pension income arrives gross with no state bite.
If the pension is $30,000 gross, combined gross income is $55,000, which clears the $45,500 budget with a manageable cushion. If the pension is $20,000, the shortfall shrinks to roughly $500 a year, and that gap at a 3.75% withdrawal rate (appropriate for someone retiring at 65 and planning to age 95) implies a portfolio of roughly $13,000 to fill it. If the pension is only $15,000, the gap is closer to $5,500 a year, requiring roughly $147,000 invested. The structurally sound version of this scenario is a pension of at least $24,000 plus a $150,000 to $250,000 cushion in a balanced portfolio of index funds and a short treasury ladder.
Delaying Social Security from 65 to 70 lifts the base benefit by roughly a third. Each year of delay past full retirement age adds about 8%, and that increase is itself COLA-indexed for life. The 2027 COLA announcement makes this arithmetic even more compelling: a higher base benefit, compounded by annual adjustments over a 25-year retirement, creates a widening margin of safety that a fixed pension alone cannot replicate. It is the single largest lever a pension-dependent retiree holds, and it costs nothing except patience and a bridge strategy.
The line items nobody underwrites: insurance and the bond
Most analyses of The Villages overlook two critical items: the CDD bond and homeowners insurance. Both behave differently from the rest of the budget. Healthcare costs rise predictably, and people plan for that. Florida insurance is the blind spot. After compounding at double-digit rates for several years, the state’s market is showing early signs of stabilization, driven by tort reform that curtailed frivolous lawsuits and reduced assignment-of-benefits abuse. The 2026 rate relief from Citizens and several private carriers is real, but premiums still run well above where they stood five years ago. Over a 25-year retirement, this one line item can consume $100,000 or more in current dollars, and unlike a mortgage it never amortizes away.
The CDD bond is the second blind spot. Buyers see the home price but often miss the $18,000 or more in attached infrastructure debt with interest that survives the closing. Paying it off at purchase, when cash allows, is usually the right move for a fixed-income retiree. It eliminates a non-deductible annual obligation that does not shrink with inflation and clears one more line item from a budget with limited room to flex.
The takeaway
The Villages on a single pension works, but only on specific terms. The house needs to be paid for. The pension needs to be at least roughly $24,000, indexed or near-indexed. Social Security should be claimed as late as cash flow allows. And there should be a side portfolio of $150,000 to $250,000 for the gap years and insurance creep. A 3.75% withdrawal rate against that cushion, a paid-off CDD bond, and a realistic $45,500 to $52,000 annual budget is the version of this plan that survives 25 years of Florida weather and Florida premiums. Florida has no state income tax, which helps a pension stretch further than it would in most states. The upcoming 3.6% COLA for 2027 provides a small but genuine lift to the income side of the ledger. Anything short of the framework above, and the brochure is doing the talking.
Editor’s note: This pass updates the Social Security average retired-worker benefit to $2,087.52 per month, reflecting the SSA’s August 2026 Monthly Statistical Snapshot, and adds context on the SSA’s October 14, 2026 announcement of a 3.6% COLA for 2027, which lifts the average retired-worker benefit to roughly $2,170 starting in January. Florida gas prices have been revised to reflect EIA data showing the September 2026 peak near $4.28 per gallon and a pullback to approximately $3.97 by early October, with the transportation cost estimate adjusted accordingly.
Contact [email protected] for any questions or corrections.
I am a long time investor and student of business, and believe finding good companies that can become great investments is the best game on earth. After 20 years of writing and researching the public markets it is clear that individuals have never had more tools and information to take control of their financial lives. From ETFs and $0 commissions to cryptos and prediction markets there has never been a greater democratization of access to investing.
I write to help people understand the investments available to them so they can make the best choice for their portfolio, whether they're starting out or looking for income in retirement.