The Hidden Costs of The Villages Nobody Mentions Until You Move In
The napkin math looks clean until you move in and find three or four line items the sales center never mentioned, each one quietly reshaping the retirement you planned around.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Every week, someone in their late fifties or early sixties runs napkin math on a legal pad: sell the northern house, buy in The Villages, live on Social Security and a portfolio, spend the days on a golf cart. The brochure version is seductive. Then people move in and discover the budget was missing three or four line items nobody in the sales center mentioned. This piece is for the reader running that math right now: the one who wants the real annual number before signing a purchase contract.
The Real Budget Runs Well Above the Base
Start with Florida itself. The state’s overall cost of living index for early 2026 sits at roughly 100.7 to 102.8, depending on methodology, just above the national baseline of 100. That makes the “cheap Florida” framing softer than most retirees expect. Inside The Villages, the picture tightens further: one frequently cited cost-of-living index places the community at 120, meaning residents pay about 20% above the national average once local housing costs are priced in. Sumter County’s fee structure pushes it well past the Florida statewide figure.
A reasonable working budget for a couple in a modest patio villa, before Village-specific costs, looks like this in current dollars:
- Housing (property tax, homeowners and windstorm insurance, utilities, maintenance reserve): $14,000
- Food at home and dining out: $12,000
- Healthcare premiums, supplements, out of pocket: $10,000
- Transportation including a second vehicle and gas: $6,000
- Recreation, travel, gifts, personal: $8,000
- Miscellaneous reserves and federal income tax on withdrawals: $6,000
That is roughly $56,000 a year for a couple living comfortably but not lavishly. Now add the line items The Villages specifically imposes.
The Line Items Nobody Puts in the Sales Brochure
The bond assessment is the first surprise. Every home in The Villages carries a Community Development District (CDD) bond: a special tax assessment that funded roads, utilities, and infrastructure when each village was originally built. This is not an HOA fee. It is a government-imposed debt attached to the property itself, not the owner. Bond balances vary by age and home type: older homes may carry around $14,000 remaining, while newer homes can run $23,000 to $28,000. The balance is either paid at closing or amortized over the remaining bond term, typically 20 to 30 years, appearing as a non-ad valorem line item on the annual property tax bill.
The monthly amenity fee adds another layer. New buyers in 2026 pay approximately $204 per month. The developer’s website advertises $189 per month for homes contracted directly under the current new-home program, but resale buyers and those with older contracts typically pay the higher prevailing rate. The fee is a deed-based covenant, not optional, and adjusts annually based on CPI tied to each property’s first-transfer anniversary. It has increased every year since at least 2020 and carries no ceiling cap in the standard covenant.
Then there is the CDD maintenance assessment, a separate and permanent charge that survives even after the bond is fully paid off. Maintenance assessments vary by district, ranging from roughly $350 per year in older northern districts up to $800 or more per year in Marion County areas, with premier locations exceeding $1,000 per year. Combined CDD costs, bond repayment plus maintenance, commonly run $1,600 to over $6,000 per year across The Villages, depending on the location and age of the home.
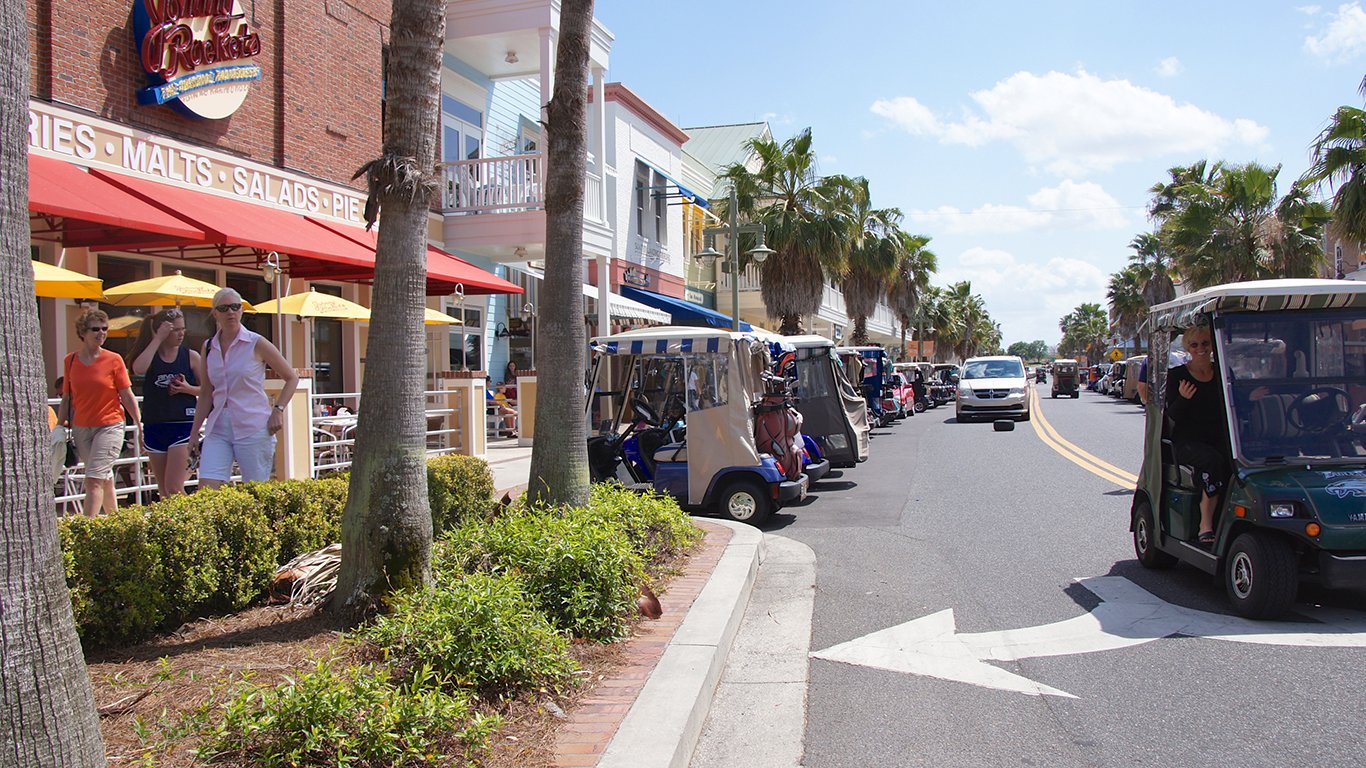
A golf cart is not optional in any practical sense. A new gas or lithium model runs $15,000 to $25,000, with insurance and eventual battery replacement as recurring costs, and most households end up owning two.
Homeowners insurance in Florida has been its own budget category for several years, though the picture shifted meaningfully in 2026. After premiums rose sharply between 2020 and 2025, the market is now stabilizing for the first time since 2019. Legal reforms tied to tort liability drove insurance litigation down nearly 50% in the 18 months after they took effect. Citizens Property Insurance filed for an average 8.8% rate decrease effective July 2026, and 44 private carriers filed for rate reductions in the same period. The average Florida homeowner still pays roughly $4,200 to $5,700 per year for standard coverage, more than double the national average, so wind, flood where applicable, and sinkhole riders in Sumter County will continue to push a modest home’s coverage past what a comparable house costs to insure in Georgia or the Carolinas. The stabilization is real, but the base remains elevated. Add all of that in and the $56,000 base budget becomes closer to $68,000 to $72,000 per year.
The Portfolio Math
Assume a couple, both claiming Social Security near full retirement age. The Social Security Administration estimates the average monthly combined benefit for an aged couple with both spouses receiving benefits at $3,208 after the 2026 COLA, up from $3,120 in 2025. That works out to roughly $38,500 a year. Against a $70,000 annual spend, the gap is approximately $31,500. At a 4% withdrawal rate, that points to a portfolio target around $787,000. At a more conservative 3.5% rate, appropriate for a 30-year horizon with rising fee escalators built into the covenant, the target climbs closer to $900,000. Couples with higher-than-average earning records, or who delay claiming past full retirement age, can close that gap meaningfully. Those relying on average benefits will find the math tighter than any sales-center conversation suggests.
Medicare is a cost you can lock in with confidence. The standard monthly Part B premium is $202.90 in 2026, up nearly 10% from $185 in 2025, and the annual Part B deductible is $283. A Medigap plan plus Part D drug coverage typically adds $200 to $300 per month per person on top of that. Those two layers together are the source of the $10,000 healthcare line in the base budget, and healthcare costs grow faster than CPI. One additional planning note: the Medicare Part B increase consumed more than a quarter of the 2026 Social Security COLA before retirees saw a dollar of it.
The Resale Problem Most Budgets Ignore
The Villages sells briskly on the way in, but the exit market is a different calculation. Inside a large age-restricted community, resale competition is concentrated. When one spouse’s health forces a move to assisted living, the home competes against hundreds of near-identical floor plans built by the same developer, many offered with fresh buyer incentives. The CDD bond balance transfers fully to the new buyer and reduces the price they are willing to pay. National existing-home sales data from the National Association of Realtors shows the broader market has been uneven in 2026, with results varying by region, and the South saw month-over-month declines in recent reports. A community-specific exit on a fixed timeline carries additional illiquidity risk that a single-family home in a mixed-age neighborhood does not.
Florida’s lack of a personal income tax reduces the carrying cost while you live there. That benefit is real. The resale liquidity risk, though, belongs in the same planning conversation. Keep six to twelve months of expenses in cash outside the portfolio specifically to bridge a slow sale, and avoid concentrating so much net worth in the house that a discounted exit forces a lasting lifestyle downgrade.
What It Actually Takes
For a couple drawing average Social Security benefits, plan on roughly $70,000 a year in current dollars, combined Social Security income of approximately $38,500, and an invested portfolio of $800,000 to $900,000 drawn at 3.5% to cover the gap. Keep a cash reserve outside that portfolio to absorb the bond balance, the escalating amenity fee, and a resale that may take considerably longer than the brochure implies. Couples with higher earnings records or delayed claiming ages will need a smaller portfolio. Those relying on average benefits will not have that cushion. The math is tight by design. Miss the reserve and the golf carts stop being fun.
Editor’s note: This pass updated the Florida insurance market section to reflect 2026 stabilization data, including Citizens Property Insurance’s 8.8% average rate decrease effective July 2026 and a nearly 50% drop in insurance litigation since tort reform, sourced from the Florida Office of Insurance Regulation’s July 2026 stability report and the American Property Casualty Insurance Association. The article also added context on The Villages’ community-level cost-of-living index of 120, compared to the Florida statewide figure of 100.7 to 102.8, and noted that the Medicare Part B premium increase consumed more than a quarter of the 2026 Social Security COLA.
Contact [email protected] for any questions or corrections.
I am a long time investor and student of business, and believe finding good companies that can become great investments is the best game on earth. After 20 years of writing and researching the public markets it is clear that individuals have never had more tools and information to take control of their financial lives. From ETFs and $0 commissions to cryptos and prediction markets there has never been a greater democratization of access to investing.
I write to help people understand the investments available to them so they can make the best choice for their portfolio, whether they're starting out or looking for income in retirement.