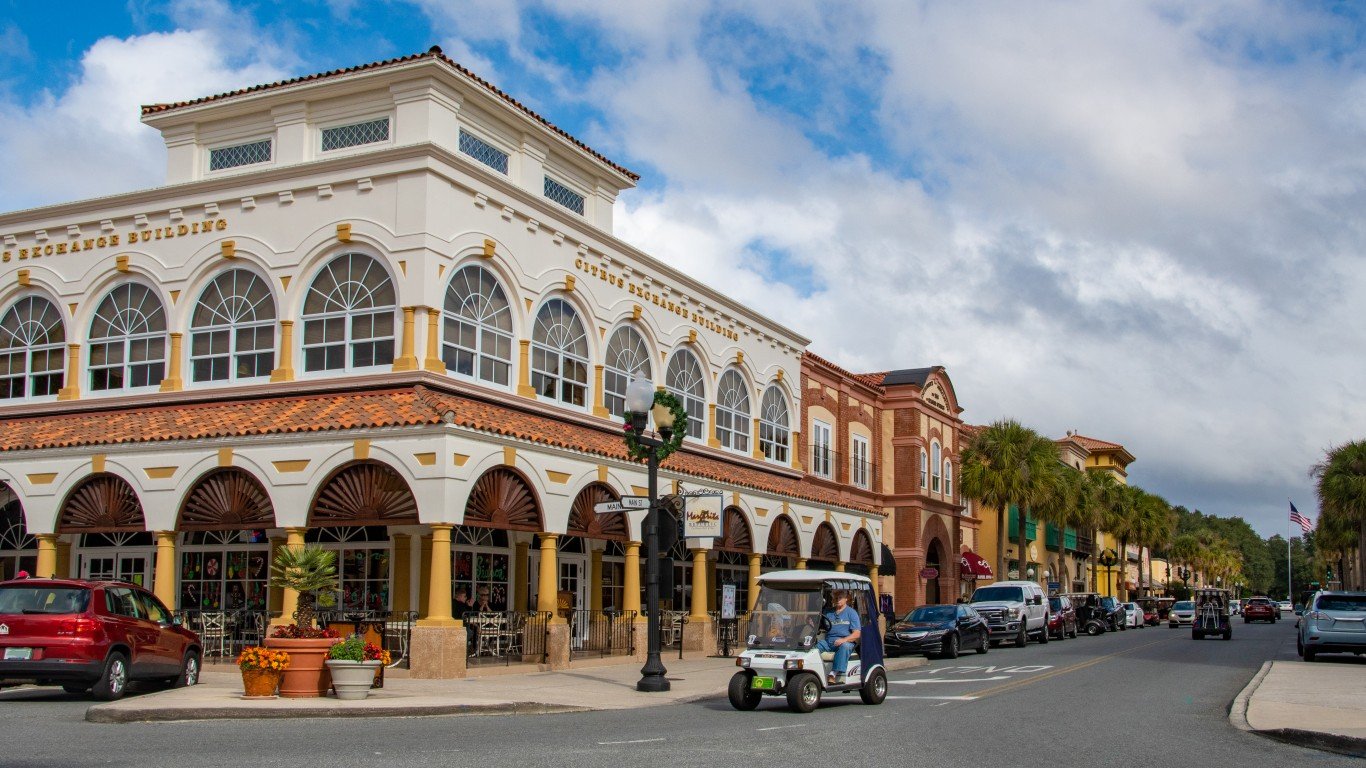
The Real Cost of Retiring in The Villages, Florida, on $2,000 a Month
Retirement brochures for The Villages make two thousand a month sound manageable, but the line items most buyers never see can quietly turn a comfortable retirement into a constant scramble before the first year ends.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
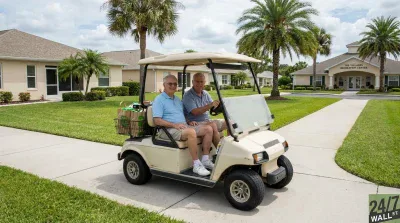
Ask around any retirement planning forum and you will encounter this question at least once a week: could I retire to The Villages on Social Security alone, roughly two grand a month? It is a fair question. The Villages markets itself as a place where a modest budget stretches, and for many residents that is genuinely true. But two thousand dollars a month in one of Florida’s most famous retirement zip codes is a specific stress test, and the answer depends almost entirely on line items most brochures never mention. Here is what it actually takes.
What $2,000 a Month Buys in Sumter County
Start with the state backdrop. Florida’s cost of living index has shifted considerably over the past several years, moving from roughly 95 in 2019 to a 2026 range of approximately 100.7 to 103, depending on the composite measure used. That is not the cheap-Florida of a generation ago. It also has no state income tax, the single most important tax feature for anyone drawing from Social Security and a modest IRA.
A workable $2,000 monthly budget in The Villages looks like this, in current dollars:
- Housing (owned patio villa, no mortgage): $250 property tax escrow, $350 homeowner insurance, $204 amenity fee, roughly $150 in CDD maintenance assessments. Call it $950 before utilities.
- Utilities (electric, water, internet, phone): about $280.
- Food at home on the USDA Low-Cost Food Plan for one: about $330.
- Medicare Part B and a zero-premium Advantage plan: roughly $203 for Part B alone, with a $0-premium Medicare Advantage plan to hold the combined figure near $250. A Medigap supplement would push this line well above $300.
- Golf cart, gas, and one older car (insurance, fuel, registration): about $150.
- Everything else (clothing, gifts, dining, home repair reserve, deductibles): $40.
That adds to roughly $2,000 for a single retiree who already owns the house outright, keeps the car a long time, and stays healthy. Two people at this budget is not realistic without a paid-off home and disciplined spending. For context, the average U.S. household spent $78,535 in 2024, according to the Bureau of Labor Statistics. This scenario runs at less than a third of that.
The Math on the Portfolio
The 2026 Social Security COLA came in at 2.8%, and the average retired worker collects about $2,084 a month as of June 2026, or roughly $25,000 a year. A benefit at that level puts a solo retiree right at budget with essentially no portfolio required, provided the house is already theirs.
If Social Security only delivers $1,600 a month, the gap is $400 monthly, $4,800 a year. At a 4% withdrawal rate that requires a $120,000 portfolio. At a more conservative 3.5% for a 30-year horizon, the figure rises to about $137,000. Retiring in The Villages on $2,000 a month requires an owned home, a Social Security check near the national average, and somewhere between zero and about $150,000 in liquid savings to cover the shortfall and shocks.
Where it breaks down is the mortgage case. Financing even a $260,000 home at current rates adds roughly $1,400 a month in principal, interest, and higher insurance. The $2,000 budget cannot absorb that. If you arrive with a mortgage, the scenario does not work. You either bring cash, downsize to a manufactured-home section, or plan on $3,500 monthly instead.
The Line Item Buyers Underprice
Most analyses overlook this: The Villages is a district-governed community, and every home carries a CDD bond used to finance infrastructure. On a resale patio villa the remaining bond can run $10,000 to $30,000, amortized as an annual assessment on top of the monthly amenity fee, which is contractually indexed to CPI and has climbed every year. When you add in the CDD maintenance charge, combined annual CDD assessments across The Villages range from $1,600 to over $6,000 per year, with newer sections carrying active bond payments at the high end.
Layer on Florida’s post-2022 homeowner insurance market, where premiums on modest Villages homes routinely land between $2,500 and $4,500 a year even inland, and the non-negotiable carrying cost of a paid-off house is closer to $850 a month than the $400 a mainland retiree might assume.
That stack of bond assessment, amenity fee, and Florida wind and hazard insurance quietly displaces the discretionary spending the brochure implies. Paying off the CDD bond at closing is often the single highest-return move a $2,000-a-month Villages retiree can make. It converts a rising annual assessment into a fixed sunk cost and buys back roughly $100 to $200 of monthly headroom for the next twenty years. That difference can be the line between comfortable and constantly counting.
The Bottom Line
The Villages on $2,000 a month is achievable, but only under a narrow specification: a paid-off home in a modest section, the CDD bond retired or nearly so, a Social Security benefit near the national average of about $2,084 a month, Medicare with a zero-premium Advantage plan, and a reserve fund of about $100,000 to $150,000 to cover the shortfall, a new roof, a replacement car, and the insurance renewal that inevitably surprises you. Withdraw from that reserve at 3.5% to 4%, let the 2.8% COLA carry the Social Security piece, and the math holds. Skip the paid-off house or the retired bond, and it does not.
Editor’s note: This pass updated the Florida cost of living index from 103.4 to the current 2026 range of approximately 100.7 to 103 per multiple composite sources, revised the amenity fee from $199 to $204 per month for new buyers, updated the Medicare Part B premium to the 2026 standard rate of $202.90 per month (up from $185 in 2025), and tightened the Social Security average benefit to approximately $2,084 per month as of June 2026 per SSA data. The CDD annual combined assessment range of $1,600 to over $6,000 per year was also added for context.
Contact [email protected] for any questions or corrections.
I am a long time investor and student of business, and believe finding good companies that can become great investments is the best game on earth. After 20 years of writing and researching the public markets it is clear that individuals have never had more tools and information to take control of their financial lives. From ETFs and $0 commissions to cryptos and prediction markets there has never been a greater democratization of access to investing.
I write to help people understand the investments available to them so they can make the best choice for their portfolio, whether they're starting out or looking for income in retirement.