Lancaster County Has Farm Markets, Light Taxes on Retirees and a Major Hospital. What It Takes to Retire There at 63 on $800,000

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
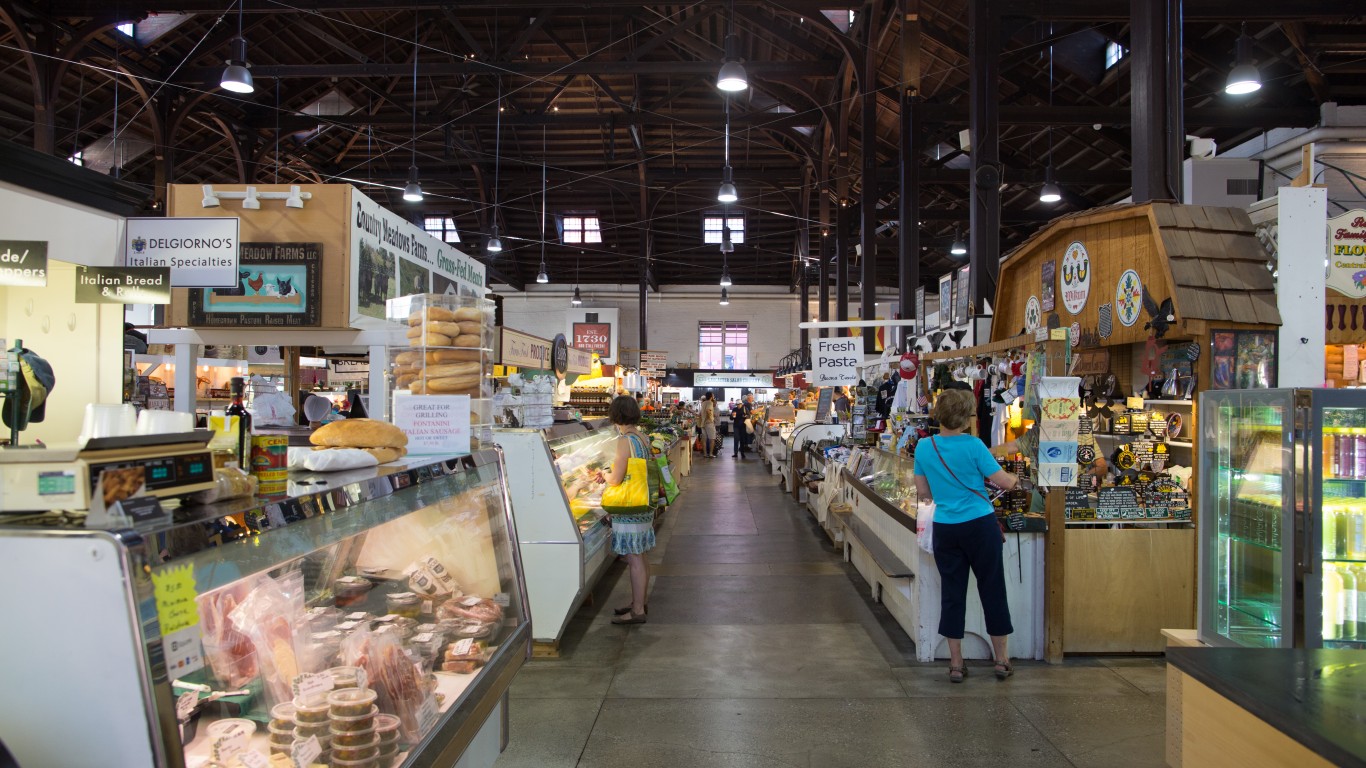
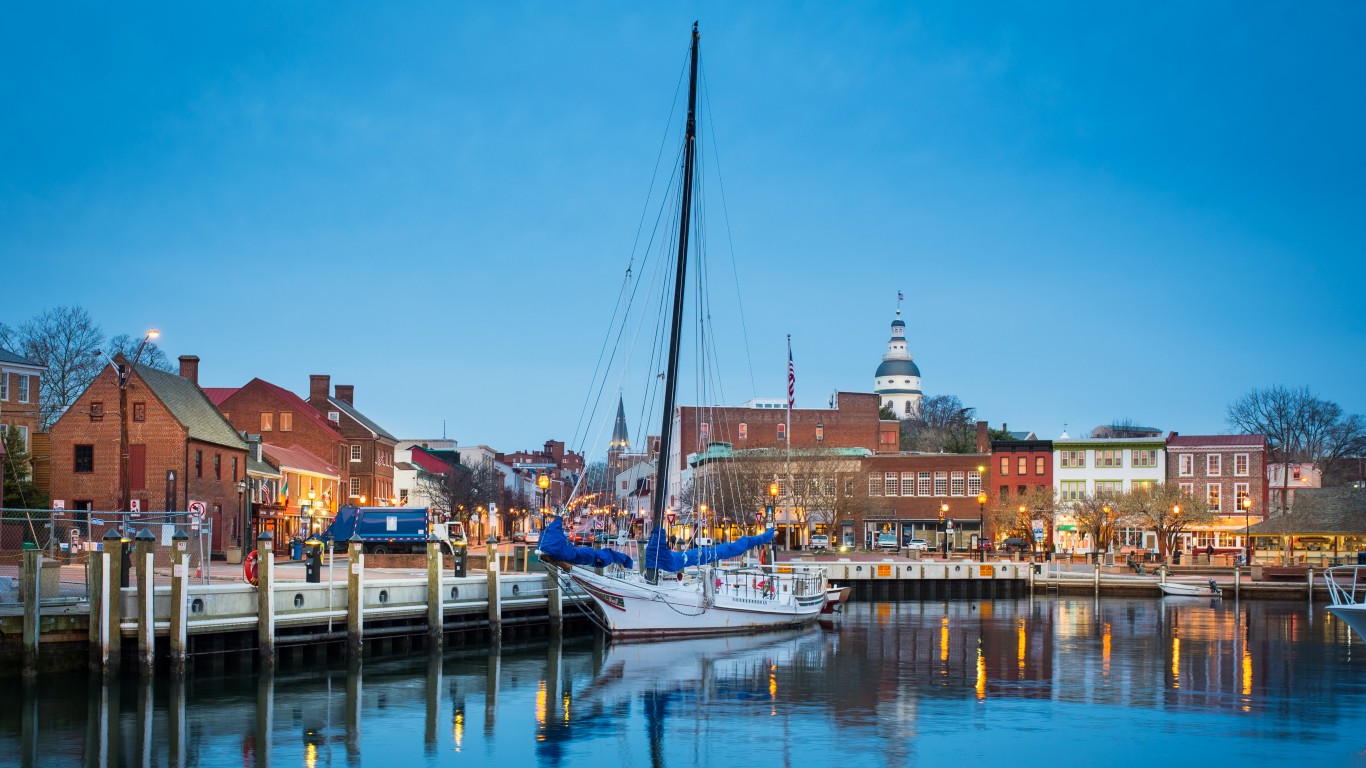
Can a 63-year-old retire in Lancaster, Pennsylvania, home to Central Market, Amish and Mennonite farm stands, and long-standing local communities? The question is whether retirement savings can cover everyday expenses there. Here’s what it takes for a 63-year-old, single or married, with $800,000 saved to make life work in this region.
How Pennsylvania Taxes a Retiree’s Income
Pennsylvania doesn’t tax Social Security, and its income tax is a flat 3.07%. Pension income is off the table too, but only under one condition. The Department of Revenue says it’s exempt “if you retired AFTER meeting the eligibility requirements for separation from service by retirement based on old age, infirmity, long-continued service” or a mix of those. IRA and 401(k) withdrawals get the same break, but only after you have retired. Local earned income taxes apply to wages, so a retiree’s checks aren’t affected.
Property tax is the largest tax cost for Lancaster County retirees, with the median homeowner paying $4,074 this year, an effective rate of 2.21%. The state’s Property Tax/Rent Rebate pays up to $1,000, but it’s open to residents aged 65 and older with a household income of $48,110 or less. At 63, it’s not available yet. Pennsylvania’s taxes are light on retirement income and higher on homeowners.
Running $800,000 Through a Lancaster Budget
A 4% draw on the savings gives $32,000 a year. The SSA estimates an aged couple both collecting averages $3,355 a month after the 2027 raise, or $40,260 a year. Together that’s about $6,020 a month. A single retiree averaging $2,170 lands near $4,840.
Take out the median property tax, about $340 a month, and Medicare Part B at $202.90 each once you’re 65, or $405.80 for two. A couple keeps roughly $5,280 for groceries, utilities, insurance, a car fund, home repairs, and federal tax, while a single retiree keeps about $4,927. That’s workable in a county where the state’s cost index is 97.572, below the national 100, though a single retiree has less room.
This budget carries three risks that could strain it over time. First, that budget assumes the house is paid off. Lancaster’s median sale price hit $364,900 in April, up 7.8% in a year, and FHFA data shows metro prices up 54.04% over five years. Buy that house out of savings, and the 4% draw drops to about $17,400. Second, those Social Security figures are averages, and taking at 63 locks in a smaller check for life.
Third, you need two years of health coverage before Medicare. After enhanced subsidies expire at the end of 2025, KFF found insurers proposed another median 15% premium increase for 2027. Retirees in this position often hold those premiums in cash, separate from the 4% draw, and keep taxable income low so any subsidy they qualify for stays intact.
What You Get, and What You Put Up With
You get farmland, small towns like Lititz and Strasburg, a walkable downtown, and Lancaster General Hospital close by. Amtrak’s Keystone Service runs between New York City and Harrisburg via Philadelphia, with a stop in Lancaster. You also get gray winters, tour-bus traffic around Bird-in-Hand and Intercourse, and home prices that keep rising. We ran similar numbers for Pittsburgh, which shares the same state tax rules but has lower housing costs.
Pennsylvania’s Inheritance Tax Lands on Your Heirs
Pennsylvania also levies an inheritance tax. Pennsylvania taxes what heirs receive: 0% to a surviving spouse, 4.5% to children and other direct descendants, 12% to siblings, and 15% to most others. For non-spouse heirs, retirement accounts generally escape the tax only if the owner dies before age 59.5; after that, IRAs and 401(k)s are taxed at the heir’s rate.
Leave $500,000 to your kids and the state takes $22,500. Leave it to a sibling, and it’s $60,000. Then the heirs owe federal income tax as they draw down an inherited traditional IRA.
What It Actually Takes
A couple who owns the home outright and invests the full $800,000 can make the plan work. A 3.5% to 4% draw, or $28,000 to $32,000, from a balanced mix of index funds with a Treasury ladder covering the first few years is one common approach. The 4% figure itself has aged, and we made the case for an income-first alternative in a free guide here.
To keep that draw rising with prices, the portfolio has to earn at least the withdrawal rate plus inflation over time. Delaying Social Security as long as cash allows, and setting aside the health bridge to 65 as its own fund, can strengthen the plan. A single retiree can do it on a tighter budget, or with a later claim.
One step costs nothing today: reviewing every beneficiary form. Listing a spouse first means 0% state tax on the first transfer. Leaving part of an IRA to charity, or buying life insurance to cover the bill, can protect what your children get. Pennsylvania’s inheritance tax determines how much your heirs keep.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.