Albemarle: A Dividend Aristocrat Hanging on by a Lithium Thread
Albemarle (NYSE: ALB | ALB Price Prediction) is a global leader in lithium production, supplying battery materials for electric vehicles and grid storage. After a prolonged downturn in lithium pricing, it is also paying dividends while losing money. That tension defines the…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Albemarle (NYSE: ALB | ALB Price Prediction) is a global leader in lithium production, supplying battery materials for electric vehicles and grid storage. After a prolonged downturn in lithium pricing, it is also paying dividends while losing money. That tension defines the entire dividend safety question.
Albemarle
| Metric | Value |
|---|---|
| Annual Dividend | $1.62 per share |
| Dividend Yield | ~1.0% |
| Consecutive Years of Increases | 31 years |
| Most Recent Increase | ~1.25% (Q2 2024) |
| Dividend Aristocrat Status | Yes |
Cash Flow Covers the Dividend. Earnings Do Not.
| Metric | TTM Value | Assessment |
|---|---|---|
| Earnings Payout Ratio | Negative (net loss) | Concerning |
| FCF Payout Ratio | 51.6% | Healthy |
| Operating Cash Flow Coverage | ~3.6x | Strong |
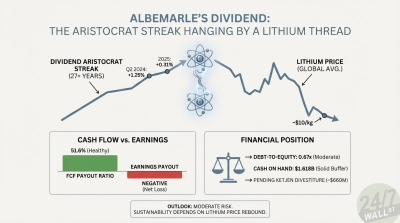
Albemarle paid $357 million in dividends in 2025 against $692 million in free cash flow, a FCF payout ratio of 51.6%. That is genuinely healthy, but context matters: 2024 saw negative FCF of -$993 million, and 2025’s OCF improvement was partly driven by a $212 million inventory reduction that will not repeat. The underlying business posted a net loss of $465 million in 2025.
Debt Is Manageable, but Not Invisible
| Metric | Value | Assessment |
|---|---|---|
| Debt-to-Equity | 0.67x | Moderate |
| Interest Coverage (adjusted) | Near breakeven | Tight |
| Cash on Hand | $1.618B | Solid Buffer |
With $1.618 billion in cash and net debt-to-EBITDA around 1.8x, the balance sheet is not in crisis. The pending Ketjen divestiture, expected to close Q1 2026 for roughly $660 million in gross proceeds, adds flexibility, with management targeting debt reduction as the primary use.
A Streak Preserved by Token Increases
| Year | Annual Dividend | YoY Change |
|---|---|---|
| 2025 | $1.62 | +0.31% |
| 2024 | $1.615 | +1.25% |
| 2023 | $1.60 | +0% |
| 2022 | $1.58 | +0% |
| 2021 | $1.56 | +0% |
The Aristocrat streak is real, but growth has effectively stopped. The five-year CAGR is roughly 1%, with recent increases existing primarily to keep the streak alive. The absolute cost remains low: $357 million annually against $16.4 billion in total assets.
Management Emphasizes Flexibility, Not the Dividend
CEO Kent Masters on Q4 2025 results: “The steps we have taken to optimize our asset portfolio, reduce costs and strengthen our financial flexibility have improved our competitive position.” CFO Neal Sheorey focused similarly on debt: “We are obviously looking at a combination of things, not just gross delevering, but also anything else that we can do with our debt towers.” Neither executive explicitly pledged to protect the dividend. That’s a notable omission for income investors.
Safe for Now, but Lithium Prices Hold the Answer
Dividend Safety Rating: Moderate Risk
The FCF payout ratio of 51.6% is healthy, the cash buffer is substantial, and the absolute dividend cost is low enough to sustain through another difficult year. But earnings are deeply negative, 2025 FCF leaned on non-recurring inventory liquidation, and the recovery thesis depends entirely on lithium prices rebounding from roughly $10 per kilogram. If prices stay depressed, FCF could erode to levels where maintaining even a $357 million annual payout becomes a genuine board-level debate. The streak has survived 31 years. Whether it survives a prolonged lithium bear market depends on a commodity price Albemarle cannot control.
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.