Apple just provided guidance for next quarter on their conference call. We’ll provide the full quote and then layer on some context below it:
Kevan ParekhChief Financial Officer
“Importantly, the color we’re providing assumes that global tariff rates, policies and their application remain in effect as of this call, and the global macroeconomic outlook does not worsen from today. We expect our June quarter total company revenue to grow by 14% to 17% year-over-year, which comprehends our best view of constrained supply. On iPad, keep in mind, we face a difficult compare driven by the launch of the A16 powered iPad in the prior year. We expect services revenue to grow at a year-over-year rate similar to what we reported in the March quarter, after removing the favorable year-over-year impact from foreign exchange tailwinds.
Keep in mind, during the March quarter, FX was a 2.5 percentage point tailwind to the total company growth rate and for services, that impact was slightly more favorable. We expect gross margin to be between 47.5% and 48.5%. We expect operating expenses to be between $18.8 billion and $19.1 billion. We expect OI&E to be around $250 million, excluding any potential impact from the mark-to-market of minority investments and our tax rate to be around 17%.”
I bolded the gross margin expectations because that’s the figure Wall Street will be most closely studying. The Street expected gross margins to be 47.6%, so this guidance is above expectations.
Apple shares are up 3.6% as of 6 p.m., in large part due to the company maintaining pricing power despite rising supply costs.
Apple CEO Tim Cook discussed the company’s Services division passing $31 billion in revenue this quarter. Here’s what he had to say about Apple TV and how the company is using sports to drive subscriptions:
Timothy CookChief Executive Officer
“Now let’s turn to services, which set an all-time revenue record with $31 billion. We saw double-digit growth in both developed and emerging markets and set new all-time revenue records across most of the services categories. There’s no better place to find celebrated storytellers than Apple TV. Audiences are plotting the return to shows like your friends and neighbors shrinking and for all mankind while discovering new favorites like Winow’s Bay.
Apple TV has also earned its place among the most decorated names in entertainment with more than 800 wins and more than 3,400 nominations in the 6 years since launch. This is a great time for sports fans on Apple TV, too. Formula One season kicked off in March and Apple TV subscribers in the U.S. have 1 of the best views of the track. The new MLS season is also well underway and subscribers in more than 100 countries and regions can watch every match with no blackouts. And Friday night baseball returned for its fifth year on Apple TV with a full season of marquee matchups.”
With Apple (NASDAQ:AAPL) earnings now out, context from peers April 29 sharpens the read. All four mega-cap peers beat EPS estimates: Alphabet (NASDAQ:GOOGL) by 94.10%, Amazon (NASDAQ:AMZN) 60.69%, Meta Platforms (NASDAQ:META) 56.79%, and Microsoft (NASDAQ:MSFT) 4.90%.
The market rewarded AI capacity over headline beats. Alphabet rallied 9.96% on Google Cloud’s 63% growth and a $460 billion backlog. Meta fell 8.55% after lifting 2026 capex guidance to $125 to $145 billion. Microsoft slipped 3.93% despite Azure growth of 40%.
Apple differs from these peers. With minimal AI capex and a Services-led beat at $30.98B, today’s 0.5% slip reflects a sector tired of premium multiples for in-line execution. Margin commentary on tonight’s earnings call remains the key swing factor.
Apple (NASDAQ:AAPL) cleared the bar with $111.18B revenue and $2.01 EPS, yet shares slipped 0.5%. The June quarter call commentary now matters more than tonight’s earnings report.
Apple does not issue formal numerical guidance, so investors parse CFO Kevan Parekh’s qualitative ranges on revenue growth, gross margin, opex, and tax rate. Management historically guides conservatively.
Bullish setup: revenue growth framed in high-single to low-double digits, Services sustaining 13%+, gross margin at the 46-47% high end, and constructive China color after Q1’s $25.53B surge.
Bearish setup: deceleration commentary, tariff-driven margin pressure, Services slowing toward high single digits, or cautious iPhone normalization tone. With shares at $271.35 and a 34 P/E, the call sets the tone into Friday.
With results in hand, Polymarket’s pre-earnings call looks vindicated. The headline market priced a 99.9% probability of an EPS beat above the $1.94 consensus, and Apple (NASDAQ:AAPL) delivered $2.01. The “Yes” contract was trading at 0.9995 into the close on $18,008 in volume.
Price-level markets were equally calibrated. Traders assigned probability 1.0 to a close above $270 and only 0.001 above $275. Apple sits at $271.35, threading that range exactly.
Context matters: across 73 resolved AAPL markets, the crowd correct rate is 71.2%, with an average Brier score of 0.1. Watch the week-of-April-27 market, where $276 leads at 74.2%.
Apple announced a new share repurchase authorization of up to $100 billion, reinforcing its commitment to returning capital to shareholders. The move extends one of the largest and most consistent buyback programs in the market and signals continued confidence in the company’s long-term cash flow generation.
Apple also increased its quarterly dividend from $0.26 to $0.27 per share, marking another steady step higher in its capital return strategy as the company continues to generate significant free cash flow.
This quarter carries added significance as it marks one of the final earnings calls for Tim Cook as CEO of Apple. Cook is expected to step down in September 2026, with longtime executive John Ternus set to take over, signaling the start of a major leadership transition.
Cook’s tenure reshaped Apple into one of the most valuable companies in the world, with its market value rising from roughly $350 billion to over $4 trillion. Investors will be paying close attention not just to the quarter’s results, but also to any commentary on the transition, Apple’s long-term strategy, and how the next phase of leadership will build on that foundation.
Apple earnings are expected in 8 minutes. Once they drop, we’ll provide the key figures you need to know and analysis on their earnings.
If you haven’t followed a 24/7 Wall St. live blog before, there’s no need to refresh this page. New updates will post automatically at the top of this feed.
Apple’s earnings are about 10 minutes away. As we wait, here are four “under the radar” storylines that could shape where the company trades tomorrow.
Greater China swing factor. The region whipsawed from $14.49B in Q4 FY2025 to $25.53B in Q1 FY2026. Polymarket traders cite a 20% surge in iPhone shipments across China with share rising to 22%, a setup that could blow past the $109.5 billion revenue bar.
Tonight’s reaction will hinge on management commentary around guidance, margins, and segment trends. Apple (NASDAQ:AAPL) doesn’t issue formal numerical guidance, so investors will parse CFO Kevan Parekh’s qualitative ranges on revenue growth, gross margin, and segment color.
Wall Street consensus sits at $1.94 EPS and $109.5 billion revenue, with Polymarket pricing a 97.5% implied probability of a beat. Last quarter set a high bar at $143.756 billion.
Bullish scenario: Tim Cook signals sustained double-digit growth, Services tracking ≥14%, gross margin above 47%, and continued China strength after Q1’s $25.526 billion surge.
Bearish scenario: iPhone deceleration after the blowout, China softening, tariff-driven margin pressure, and muted Apple Intelligence commentary. History favors guidance: the average day-of reaction is -0.19% despite eight straight beats.
As we’ve noted throughout this live blog, one of the biggest metrics Wall Street will be watching tonight is Apple’s margins. Components like memory continue soaring in price, which has pressured companies across the smartphone supply chain.
NAND producer SanDisk just reported earnings and they were an epic blowout. The company’s EPS came in at $23.41, ahead of Wall Street’s expectations of $14.42.
The bad news for SanDisk stockholders? Even with the blowout, shares are down 7%.
SanDisk’s results have limited visibility into Apple’s earnings. The company has long-term supply agreements. However, with SanDisk forecasting EPS of $30 to $33 per share next quarter, the momentum behind rising memory prices continues to build.
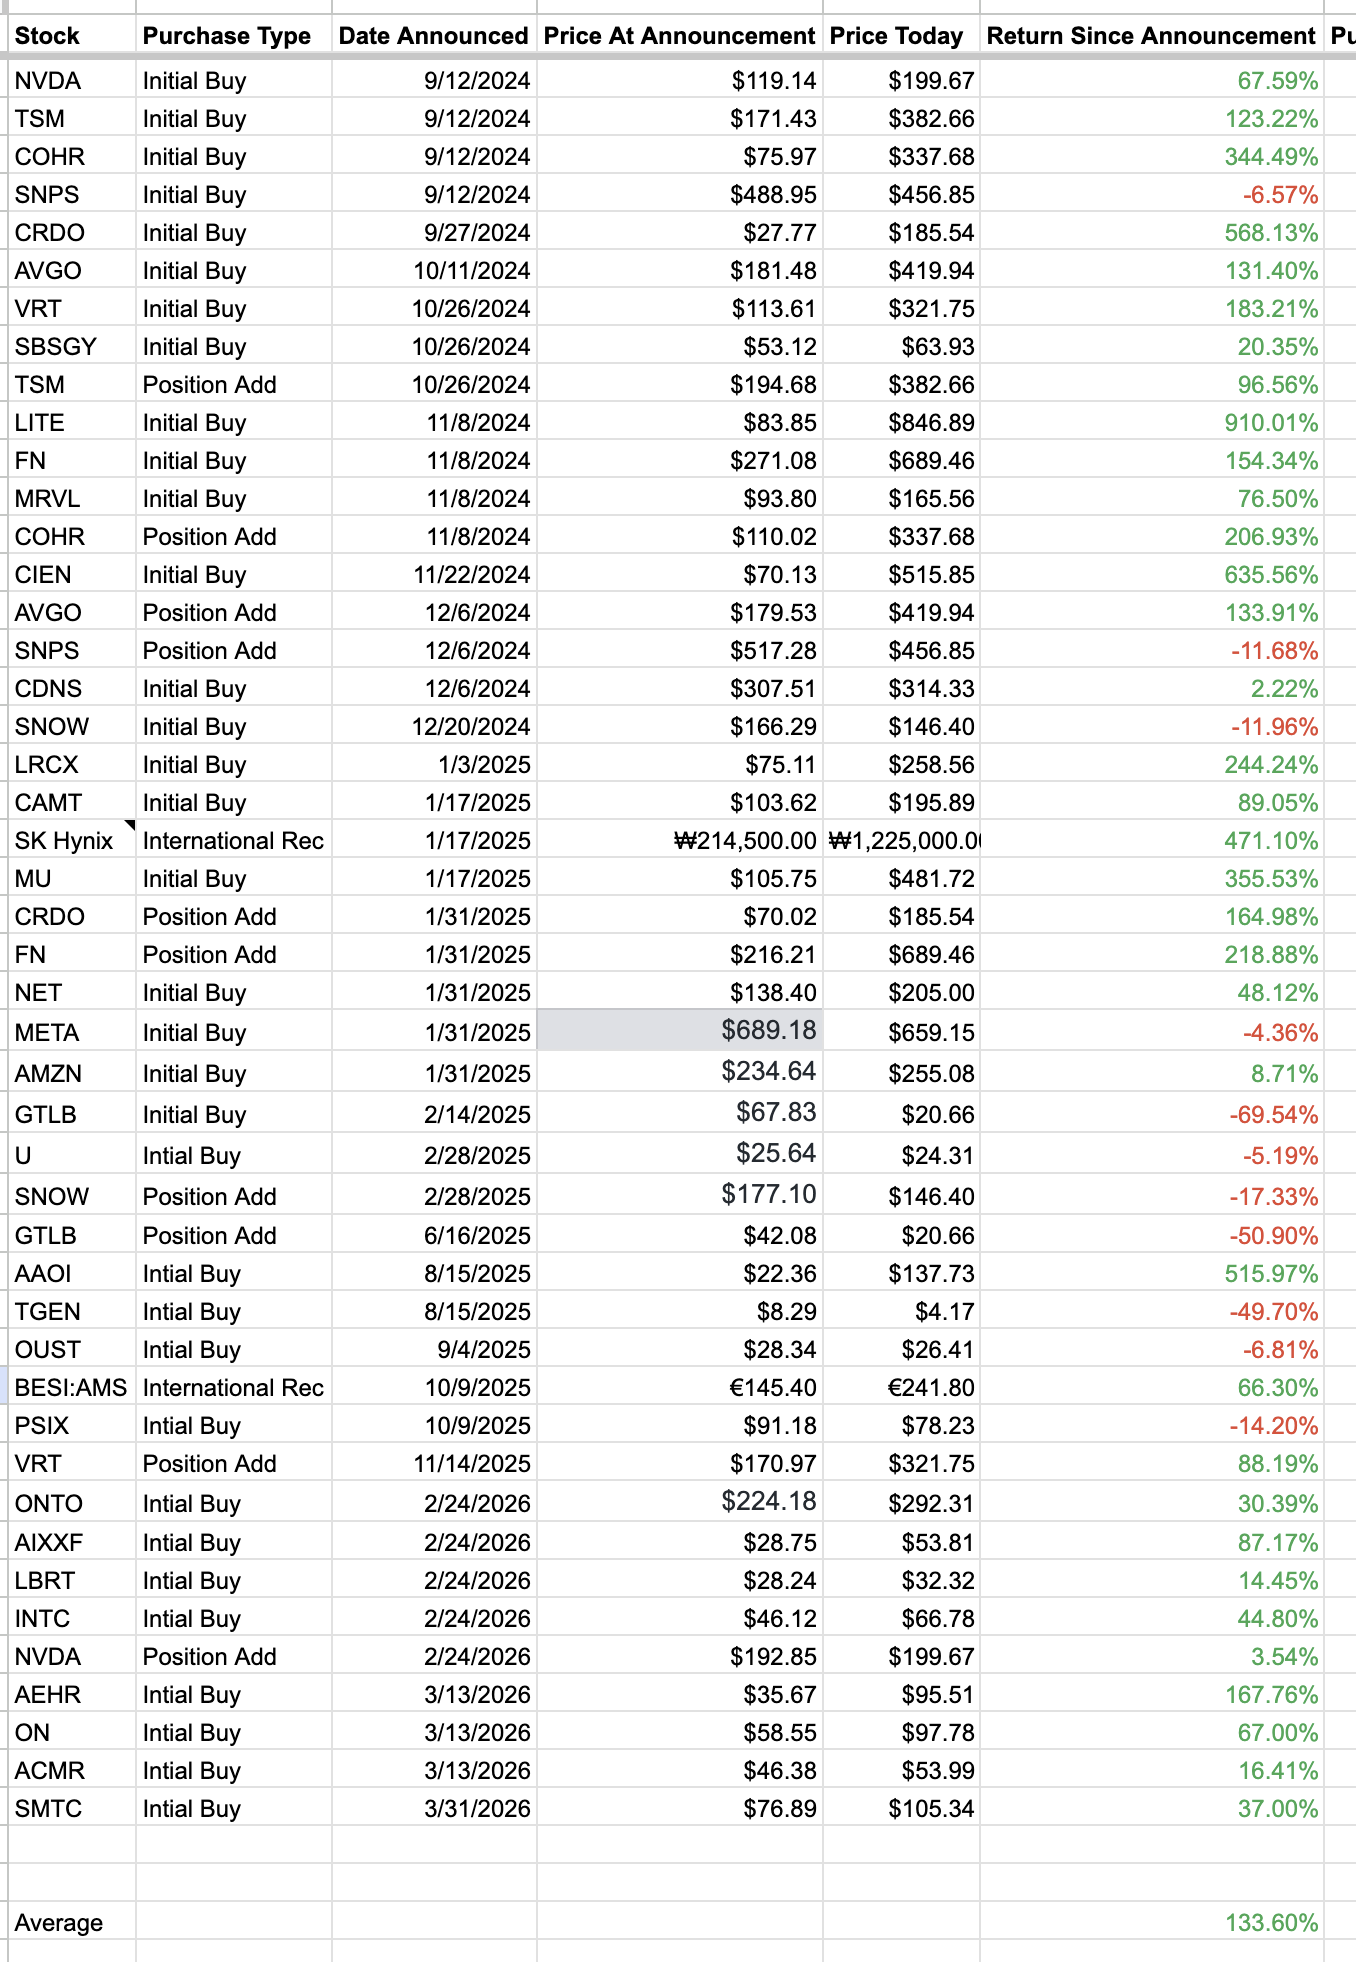
While we wait for Apple’s earnings (expected at about 4:30 p.m.), let’s talk about a free resource providing market-beating investment ideas.
Below is a scorecard from 24/7 Wall St.’s AI Investor Podcast. On the podcast, we issue recommendations that have absolutely thumped the market since we started issuing them in late 2024.
The best part? Following along is absolutely free. All these recommendations have been provided during episodes of the podcast. Simply subscribe in your favorite Podcast player if you want to follow along with a trusted, market-beating source for AI news and analysis.
Apple (AAPL) shares are up 1.45% in late trading while the Nasdaq is up 1%.
It’s been a day of diverging performances for the largest technology stocks. Meta Platforms, Amazon, Microsoft, and Alphabet all reported last night.
Alphabet shares are soaring 9% after the company issued blowout cloud and search revenues last night. On the other end, Meta shares are down afte the company raised its capex forecast up to $145 billion on the high end for the year.
Apple won’t have to worry about rising capex (the company is famously holding back on the arm’s race its rivals have embarked on). However, investors will be concerned that rising margins could crimp the company’s profitability. Any commentary from Tim Cook on supply costs will be carefully studied.
Apple carries an eight-quarter earnings streak and a freshly minted five trillion dollar market cap into tonight's fiscal Q3 report, but prediction markets just shifted in a way that suggests traders are quietly bracing…
Apple (NASDAQ: AAPL | AAPL Price Prediction) reports first-quarter fiscal 2026 results today after the bell. After a strong run of consecutive beats and a stock that’s pulled back 6% over the past month,…
Apple (NASDAQ:AAPL | AAPL Price Prediction) just delivered its best March quarter ever, raised the dividend, and authorized a fresh $100 billion buyback. Our model thinks the rally has more room to run. The…
Apple reports fiscal fourth-quarter results on Nov. 2 carrying a $5 trillion valuation, a memory cost squeeze Tim Cook called a once-in-a-century event, and a pattern of falling on earnings beats. Three forces will…
Apple (NASDAQ:AAPL | AAPL Price Prediction) has become one of the more interesting setups in mega-cap tech. After a 46.9% rally over the past year and an 8.01% year-to-date gain, the stock consolidated in…
Apple (Nasdaq:AAPL | AAPL Price Prediction) reports fiscal fourth-quarter earnings after the close today, capping a year marked by renewed product strength and record Services growth. The stock trades at all-time highs as investors…
Apple‘s (NASDAQ:AAPL | AAPL Price Prediction) fiscal Q2 2026 beat triggered a three-way split among Wall Street analysts. Morgan Stanley raised its price target on Apple stock to $330 from $315 while keeping an…
Wall Street has Apple pegged at one price target, but our proprietary model lands somewhere else entirely, and the gap between the two tells a story about where this stock may be headed after…
Shares of Apple (NASDAQ:AAPL | AAPL Price Prediction) are up roughly 5% in Friday morning trading, climbing to about $284 after the iPhone maker delivered a powerful fiscal second-quarter beat and bullish forward guidance…