Microsoft Price Prediction: After a 25% Three-Day Rally, Here’s Where The Stock is Headed
Microsoft just posted its biggest post-earnings surge in recent mega-cap history, and the move happened so fast it raises a serious question about what comes next for investors still eyeing the stock.

Microsoft (NASDAQ:MSFT | MSFT Price Prediction) has delivered one of the most dramatic post-earnings rallies in mega-cap history. My 24/7 Wall St. price target says the run has legs, but with a caveat about how quickly the market got here.
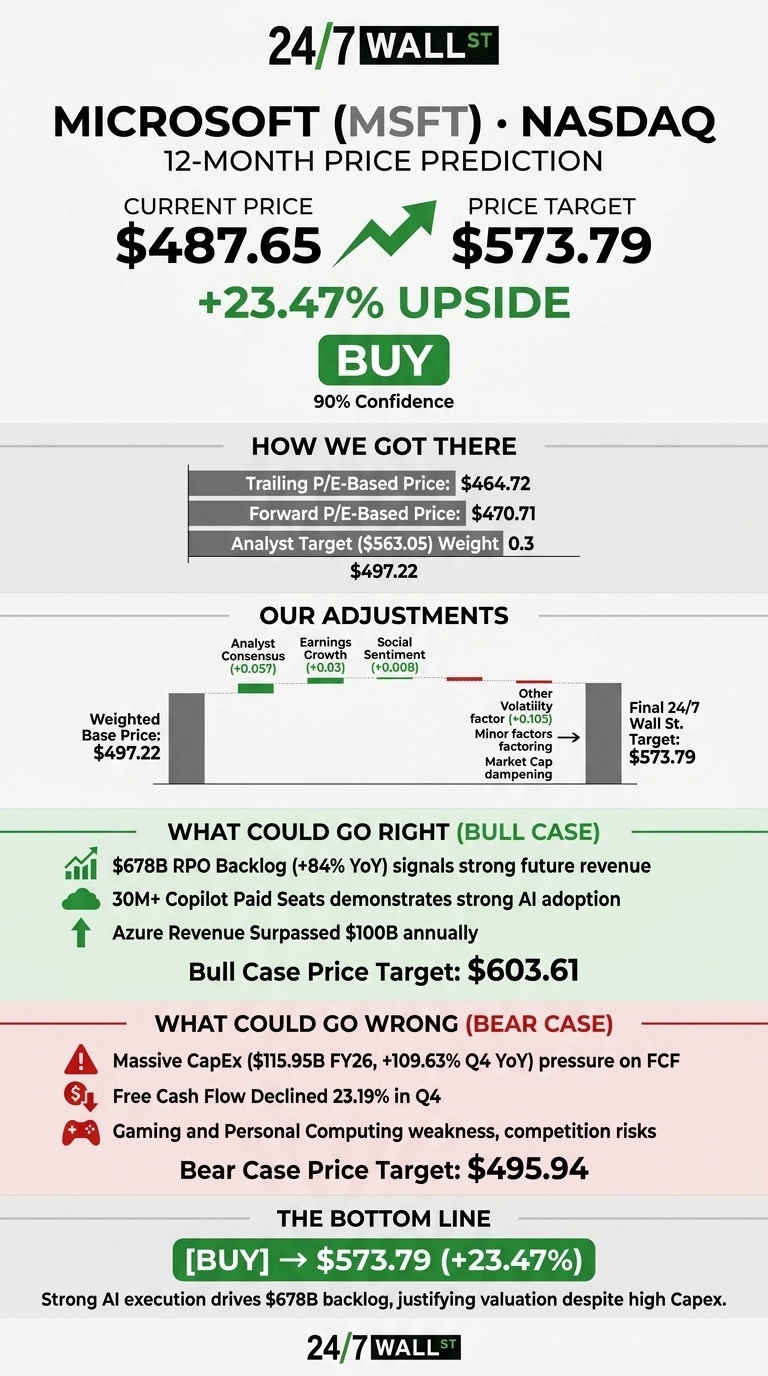
Microsoft trades at $487.65 after a 25.33% one-week surge triggered by a blowout Q4 FY26 earnings report. Our 24/7 Wall St. price target for Microsoft is $573.79, implying 23.47% upside over the next 12 months. The recommendation is buy at 90% confidence. Azure crossing $100B in annual revenue and Copilot scaling past 30M paid seats are the pillars.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $487.65 |
| 24/7 Wall St. Price Target | $573.79 |
| Upside | 23.47% |
| Recommendation | BUY |
| Confidence Level | 90% |
The Rally That Rewrote The Chart
MSFT entered earnings week near $389, down from a 52-week high of $550.24 and stuck in a months-long slide from last August. Q4 FY26 delivered: Revenue hit $90.01 billion, up 17.75% YoY, with non-GAAP EPS of $4.74 against $4.2397 consensus, an 11.81% beat.
Azure grew 43% and commercial RPO ballooned to $678 billion, up 84% YoY. Shares jumped 15.51% on the earnings report, the largest single-day earnings reaction in the six-quarter dataset.
The Case For $600+
Bulls have real ammunition. Azure crossed $100 billion in annual revenue, Microsoft 365 Copilot passed 30 million paid seats, and the extended OpenAI partnership locks in $250B Azure commitment through 2032.
Our bull-case scenario points to $603.61, a 29.89% total return. Reddit chatter reflects the shift, with sentiment jumping from 35 on July 28 to 94 by July 31.
What Could Go Wrong
The bear case starts with capex. Full-year FY26 capex hit $115.95 billion, with Q4 consuming $35.80 billion, up 109.63% YoY. Free cash flow fell 23.19% in the quarter. Bulls counter that FCF pressure reflects buildout supporting the $678B RPO backlog, meaning spend has contracted demand behind it.
More Personal Computing revenue declined 4%, insider activity shows net selling across 33 recent transactions, and mean reversion is real. Historical MSFT one-week post-earnings returns average -2.16%. Our bear scenario is $495.94.
How Microsoft Compares To Alphabet, Amazon, And Oracle
Alphabet (NASDAQ:GOOGL) is the closest cloud competitor via Google Cloud. Amazon (NASDAQ:AMZN) runs AWS, Azure’s direct hyperscale rival. Oracle (NYSE:ORCL) has emerged as the surprise enterprise-AI infrastructure winner, with RPO growth paralleling Microsoft’s $678B backlog.
Microsoft trades at a trailing P/E of 27 with forward P/E near 26 against 31.7% earnings growth and a 46.78% operating margin. That margin premium, combined with Azure’s 43% growth rate, makes our $573.79 target reasonable against the peer group.
The Bull Case Holds, With Discipline
The 24/7 Wall St. price target of $573.79 and buy rating stand at 90% confidence. The RPO backlog tips the scale. Contracted future revenue that grew 84% YoY is rare at this scale.
The setup looks most attractive on any pullback above the $460 pre-rally breakout, while a Q1 FY27 print showing Azure decelerating below 35% or capex efficiency worsening would warrant caution. Given the vertical rally, the setup favors scaling in rather than chasing.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $525 |
| 2027 | $573.79 |
| 2028 | $665 |
| 2029 | $765 |
| 2030 | $870.44 |
These projections assume Microsoft executes on Azure and Copilot monetization. Significant upside or downside could result from AI capex returns materializing faster than expected, or regulatory action against the OpenAI partnership.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.