Microsoft’s AI Investment Could Pay Off for Years. Here’s My Price Target
Azure just crossed a milestone that most analysts dismissed as years away, and Microsoft's backlog tells a story the stock price has not caught up to yet.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Our Microsoft (NASDAQ:MSFT | MSFT Price Prediction) call is straightforward: the AI investment cycle is starting to produce real financial leverage, and the market has not fully repriced it.
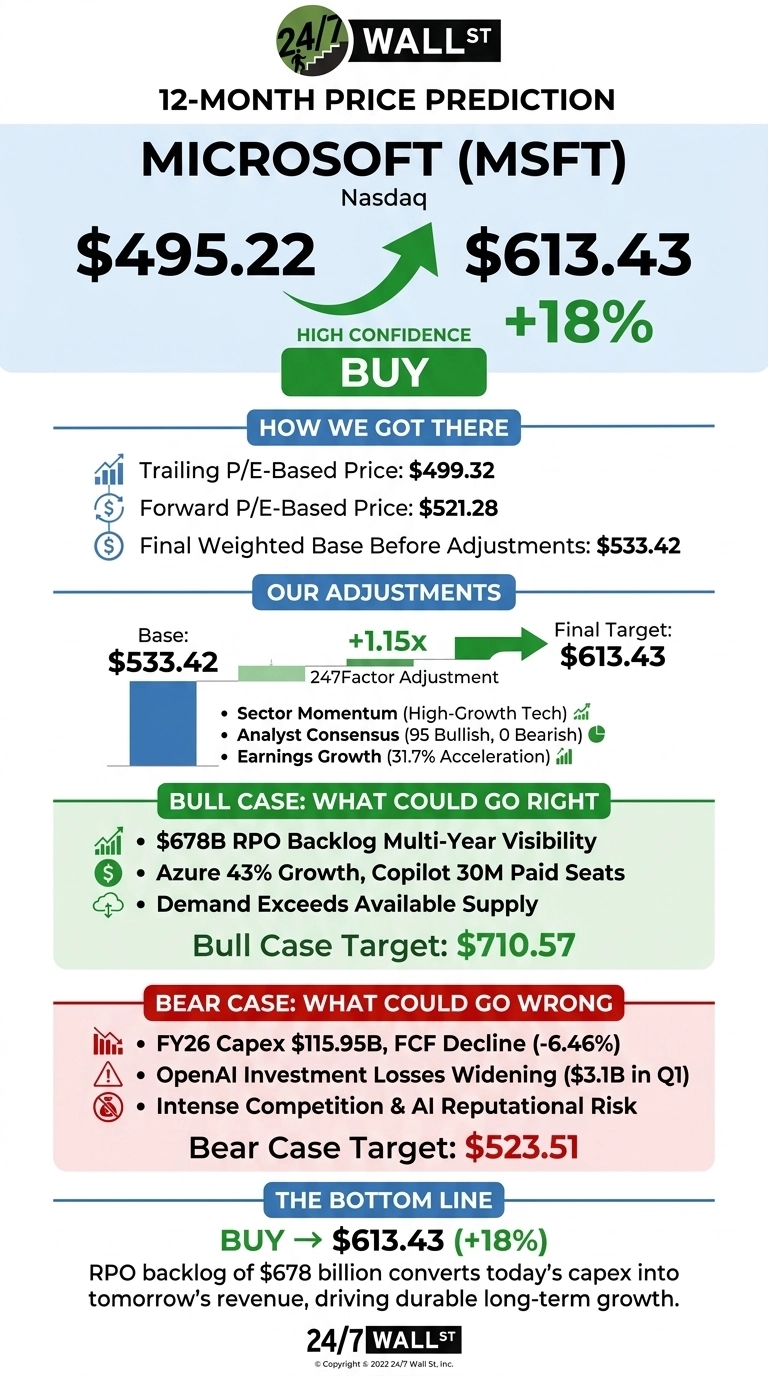
The 24/7 Wall St. price target for Microsoft is $613.43, versus a current price of $495.22. That implies 22.85% upside over the next 12 months. Our recommendation is buy, and our confidence level is high at 90%.

24/7 Wall St. Price Target Summary for MSFT
| Metric | Value |
|---|---|
| Current Price | $495.22 |
| 24/7 Wall St. Price Target | $613.43 |
| Upside | 22.85% |
| Recommendation | BUY |
| Confidence Level | 90% |

Why Microsoft Finally Turned the Corner
Microsoft is roughly flat over the past year at -1.95%, but shorter-term momentum has quietly returned: up 1.62% in the past month and 3.05% year to date.
The bigger story is fundamentals. Fiscal Q4 2026 revenue hit $90.01 billion, up 17.8% year over year, non-GAAP EPS of $4.74 beat estimates by 11.81%, and Azure crossed $100 billion in full-year revenue for the first time. Even a previously skeptical analyst at CNBC this week said Microsoft has “clearly turned the corner” on monetizing its buildout.
Why Bulls See a Breakout Ahead
The bull case rests on the RPO backlog. Commercial remaining performance obligations surged 84% year over year to $678 billion, giving Microsoft multi-year revenue visibility few software companies can match.
Azure grew 43%, Microsoft 365 Copilot passed 30 million paid seats, and CFO Amy Hood told investors that “demand continues to exceed available supply” for Azure capacity.
If the FY27 Azure guide of roughly 45% growth in constant currency holds, our bull-case one-year path reaches $710.57. The Wall Street consensus target of $576.40 sits between our base and bull scenarios.

Risks Worth Watching
The bear case starts with capex. Full-year FY26 capital expenditures ballooned to $115.95 billion, dragging free cash flow down 6.46% despite record earnings. OpenAI-related investment losses widened to $3.1 billion in Q1 FY26.
That said, bulls would argue this reflects investment in future capacity: the $678 billion RPO covers the buildout, and Hood emphasized that GPU-heavy capex is “short-lived assets” that can be throttled if demand softens.
All of that spending has to be powered, cooled, and networked by somebody, and we pulled together seven companies doing exactly that in a free AI infrastructure report. Our bear-case one-year path still lands at $523.51, above today’s price.

How Microsoft Compares to Alphabet and Amazon
Alphabet (NASDAQ:GOOGL) is the sharpest valuation contrast. Google Cloud grew 82% in Q2 2026, faster than Azure, yet Alphabet trades at a trailing P/E of just 15 versus Microsoft’s 28. That makes Microsoft look expensive on the multiple, but its 46.78% operating margin dwarfs Alphabet’s 34%.
Amazon (NASDAQ:AMZN) is the direct hyperscaler comparison. AWS revenue grew 37% in Q2 2026 at a 39.4% AWS operating margin, but Amazon’s overall net margin is only 10.83% versus Microsoft’s 40.31%. On a per-dollar-of-earnings basis, our $613.43 target for Microsoft looks reasonable on the earnings power.
Microsoft on the AI Payoff Curve
The 24/7 Wall St. price target for Microsoft is $613.43, a buy rating with 90% confidence. The key factor tipping the scale is the $678 billion RPO backlog, which converts today’s capex into tomorrow’s revenue.
The bullish case strengthens if Azure holds its mid-40s growth rate into calendar 2027. The thesis weakens if AI capex growth outpaces RPO conversion for two consecutive quarters. On balance, the setup favors the bull scenario.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $523 |
| 2027 | $613 |
| 2028 | $723 |
| 2029 | $782 |
| 2030 | $862 |
These projections assume Microsoft continues executing on Azure and Copilot monetization. Significant upside or downside could result from AI infrastructure returns, OpenAI partnership economics, or a broader tech multiple reset.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.