32 Analysts Say Hold on Intel. Here’s What the Numbers Actually Show
Wall Street has overwhelmingly parked Intel in hold territory, but the stock just posted a 212% gain this year while simultaneously losing billions in its foundry division. Something in those conflicting signals deserves a closer look before you decide what…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
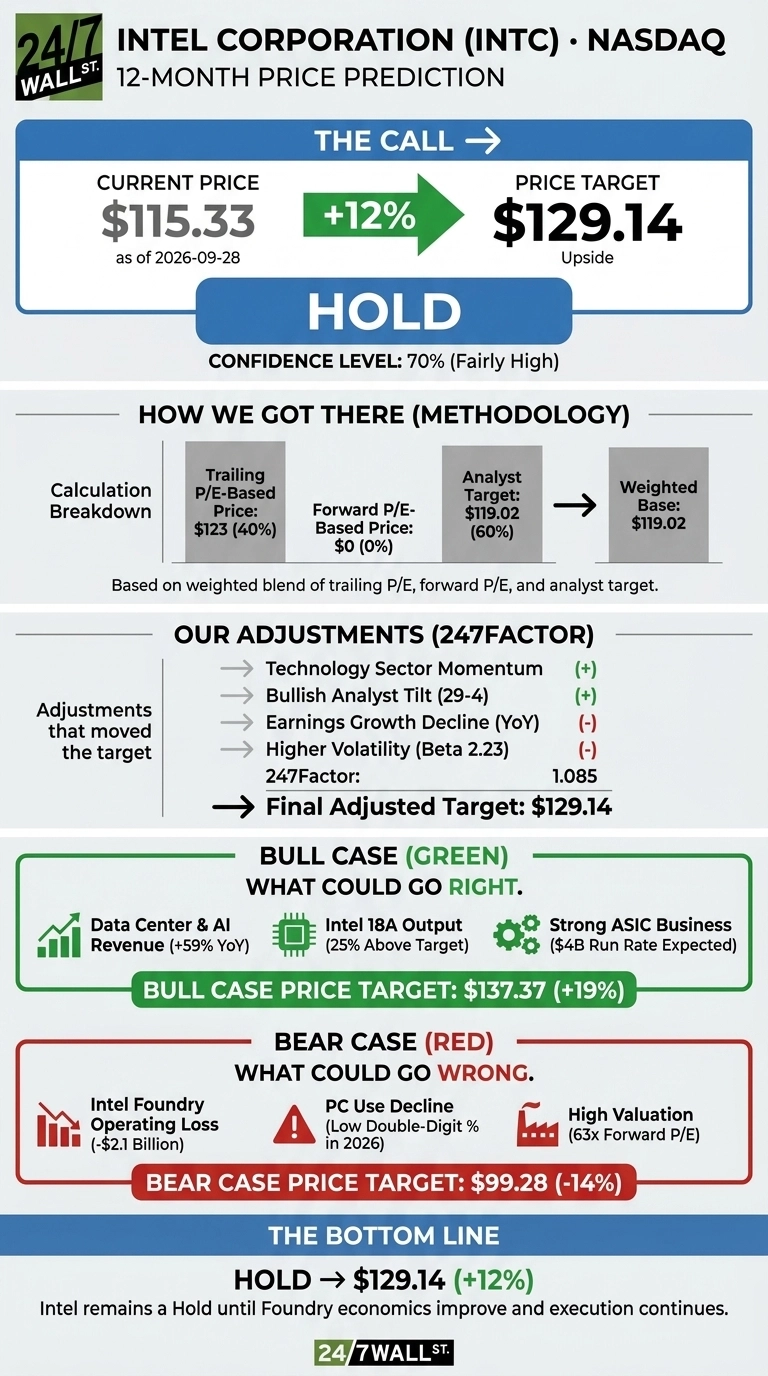
Intel (NASDAQ:INTC | INTC Price Prediction) trades at $115.33. That is down 6.24% from a $123 open as AI fears mount across chip stocks. The price target from 24/7 Wall St. for Intel is $129.14 over the next 12 months, which means about 12% upside. The model gives the stock a hold rating with fairly high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $115.33 |
| Price Target from 24/7 Wall St. | $129.14 |
| Upside/Downside | 12.0% |
| Recommendation | HOLD |
| Confidence Level | 70% |

Most of Wall Street agrees with that rating. Of 48 analysts, 32 rate Intel a Hold, 13 rate it a Buy and 1 rates it a Strong Buy. The consensus target of $116.37 sits almost exactly where the stock trades now.
Our model finds somewhat more room because sector momentum and upward estimate revisions carry more weight than the stock’s volatility does.

A 212% Rally Runs Into Monday’s AI Jitters
Intel has gained 6.2% over the past week, 30.7% over the past month and 212.55% year to date. It still sits about 19% below its 52-week high of $142.35 and far above its low of $32.89.
In the second quarter, revenue of $16.13 billion rose 25.4% and exceeded the $14.45 billion estimate. Non-GAAP EPS of $0.42 beat expectations of $0.2175. September also brought a reported SK Hynix discussion about making memory chips in Intel’s U.S. fabs.
Why Bulls See $137 and Beyond
Data Center and AI revenue rose 59%. Output on the Intel 18A process node ran about 25% above target. The ASIC business is at roughly a $2 billion run rate, and management expects it to reach $4 billion. Xeon 6 won the host CPU slot in NVIDIA’s DGX Rubin systems.
Consensus 2027 EPS stands at $2.0621, and the high estimate is $3.44. The bull case of $137.37 means about 19% upside. Firm-level analyst targets were unavailable.

What Could Push Intel Back Under $100
Intel Foundry lost $2.1 billion last quarter, and external customers added only $293 million in revenue. Intel says it could pause 14A without enough outside demand. Management expects PC use to fall by a low double digits percent in 2026.
At 63x forward earnings, the valuation leaves little room for mistakes. Our bear case is $99.28, about 14% downside. One counterpoint: the GAAP loss of -$2.16 per share came from a $12.53 billion non-cash escrow charge, and operating cash flow rose 241.8%.
How Intel Compares to AMD and NVIDIA
AMD (NASDAQ:AMD) competes directly with Intel in x86 server and PC chips. It trades at 40x forward earnings on 50.1% revenue growth, so it is cheaper and growing faster.
NVIDIA (NASDAQ:NVDA) is both an Intel investor and the benchmark for AI computing. It trades at 25x with 105.9% growth.
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Intel | 63 | 25.4% |
| AMD | 40 | 50.1% |
| NVIDIA | 25 | 105.9% |
Intel already carries a turnaround premium over both peers. That makes our target reasonable, but it leaves little margin if earnings slip.
The other way to play the AI expansion is to skip the chipmakers entirely and look at the power, cooling, and networking suppliers behind the data centers, which we covered in a free report on seven AI infrastructure names.
Intel Price Prediction 2026-2030
The 24/7 Wall St. price target of $129.14 supports a hold with 70% confidence. Foundry economics tip the scale.
I’d get more constructive if Intel announces outside 14A customers and foundry losses keep shrinking. I’d stay patient if server supply limits and PC weakness drag the next earnings report below the $0.38 EPS guidance.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $119.91 |
| 2027 | $126.87 |
| 2028 | $140.89 |
| 2029 | $144.95 |
| 2030 | $149.80 |
The projections rest on Intel continuing to execute its current strategy. The 14A ramp planned for 2028 could move them sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.