Apple (AAPL) Trading Above Analyst Targets as Memory Costs Crimp Margin Outlook
Apple shares have lapped analyst price targets while memory costs quietly eat into margins, and a $1,999 folding phone debut is about to test whether the market's goodwill toward a new CEO holds up.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Apple (NASDAQ:AAPL | AAPL Price Prediction) shareholders face an unusual problem because the stock has risen past the forecasts of the analysts who cover it. Apple closed at $332.89, which is above the $328.09 average analyst price target. Apple has caught up to a full year of expected appreciation, and most analysts have not raised their numbers yet.
If we look at price targets issued in only the past few months, the average is higher at $334.90. Regardless, AAPL stock is getting close.
A target under the share price means estimates are stale relative to the rally, and analysts will likely raise targets to match the price unless results disappoint, in which case downgrades become more likely. Apple is up 22.79% this year, compared with 13.62% for the S&P 500, extending the valuation.
A Wide Target Range Shows a Street That Can’t Agree
44 analysts cover Apple, and their targets range from $215 to $405. For a mature company, a range this wide suggests analysts disagree about what Apple is: some see a hardware maker facing rising costs, while others see a services and artificial intelligence platform that deserves a premium.
The median target is at $340, above both the average and share price. A few low outliers pull the mean down. The average fiscal 2027 earnings estimate has slid to $9.5758 per share from $9.6826 three months ago, meaning the rally happened while earnings expectations drifted lower.


Rising Memory Costs Are the Margin Risk Analysts Are Starting to Flag
Morgan Stanley cut its target to $355 from $360. It kept an Overweight rating, citing “limited upside… after a strong six-month run.” The bank also pointed to lower-than-expected iPhone pricing and sharply higher memory chip costs.
Memory costs are the bigger issue. Demand from artificial intelligence has pushed chip prices into an upcycle, and Apple buys a great deal of memory. On the July earnings call, Tim Cook described memory pricing as a “100-year flood”.
Excluding tariff refunds, gross margin fell to 48.1% in the June quarter from 49.3% in March, and September guidance points to a 46.5% midpoint. Management said memory accounted for more than that decline, and it expects help from carry-in inventory to shrink after September. That margin pressure exists no matter how many phones Apple sells.
Paying 36 Times Forward Earnings for a Folding Phone
Apple is trading at about 36 times forward earnings, compared with a trailing multiple of about 43x. That gap shows the market already expects strong profit growth, even though Apple guided September-quarter revenue growth to 9% to 11%.
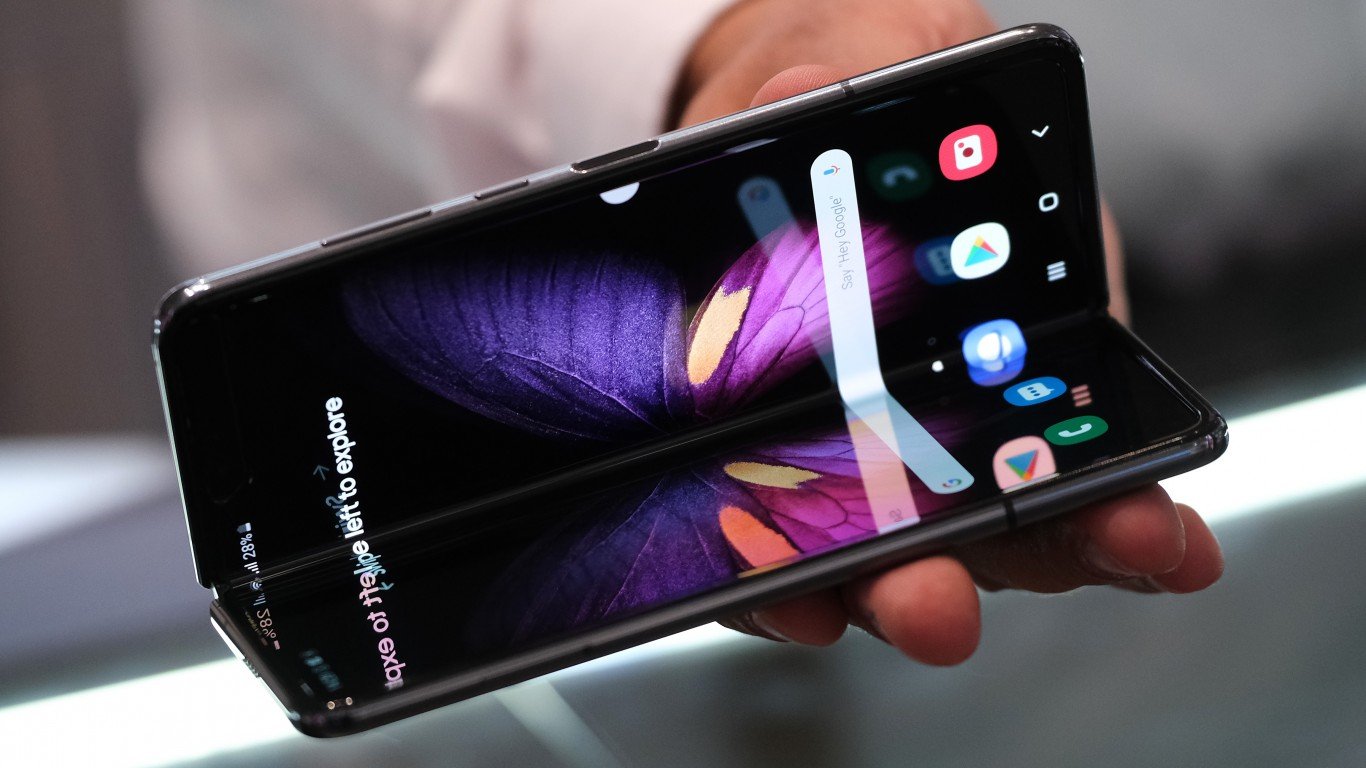
The iPhone Duo, Apple’s first folding phone, is priced at $1,999 and goes on sale Oct. 23. Bloomberg reports that a smart home product is due Oct. 13.
The market expects Apple to sell about 6 million units of the Duo this year. Apple has more than 2.5 billion active devices, and its iPhone line brought in $54.3 billion in the June quarter alone. Next to numbers that size, a first-generation folding phone matters more for the brand than for revenue.
Apple hit an all-time high of $345.34 on Sept. 22, three weeks after John Ternus took over as chief executive. New leaders often get the benefit of the doubt until their first earnings report. Apple’s market value of about $4.86 trillion is also close to the $5 trillion mark. Some of the current multiple likely shows goodwill toward a leadership change whose results have not been tested yet.
What Could Change the Outlook for Apple Stock Before Earnings
Apple looks fully valued at this price. The business is excellent, but the stock already reflects a year of gains while memory costs push margins lower.
The Duo launch and the earnings report scheduled for Oct. 29, which Apple has not confirmed, could change my view. Apple would need strong early Duo demand. It would also need gross margin at or above its 47% to 48% guidance and a December-quarter outlook that shows memory costs under control.
Results like that would push targets higher. If margins slid instead, the next round of analyst changes is more likely to be downgrades.
Microsoft (NASDAQ:MSFT) trades at a trailing earnings multiple of about 29. Azure grew 43% last quarter, and Microsoft Cloud revenue rose 27% to $59.3 billion. That growth comes from enterprise cloud and AI contracts, so it depends much less on smartphone upgrade cycles.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.