96% of Analysts Are Bullish on Microsoft. Here’s the Price That Implies
Nearly every analyst covering a $3 trillion company agrees it belongs higher, yet the stock still trades below its 52-week high. The real question is how much higher, and the answer depends on a few risks that bulls are quietly…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Analysts rarely agree this much on a $3 trillion company. Microsoft (NASDAQ:MSFT | MSFT Price Prediction) has 14 Strong Buy and 39 Buy ratings against just 2 Holds and no Sells. That works out to 96% bullish.
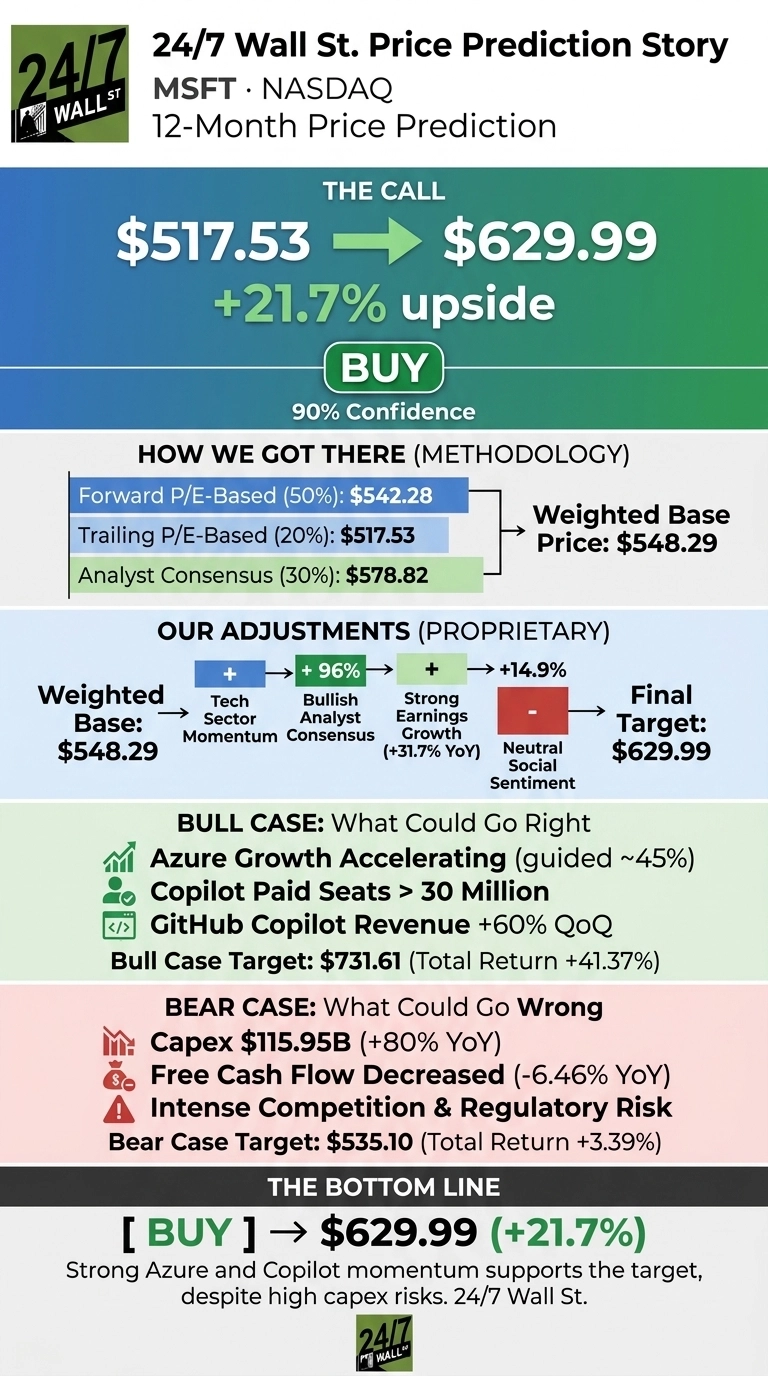
The 24/7 Wall St. price target for Microsoft is $629.99 over the next 12 months, which means 21.73% upside from $517.53.

| Metric | Value |
|---|---|
| Current Price | $517.53 |
| Price Target from 24/7 Wall St. | $629.99 |
| Upside/Downside | 21.73% |
| Model Rating | BUY |
| Confidence Level | 90% |
Our target sits well above the consensus analyst target of $578.82, which means 11.8% upside. Azure growth is accelerating, and analysts have made 21 upward revisions for fiscal 2027 EPS in the past 30 days against 8 cuts.

Azure’s Blowout Quarter Fueled a Historic Rebound
Microsoft is up 8.4% year to date and on track for its biggest quarterly gain in 28 years. Shares trade 5.8% below their 52-week high of $549.20. On Monday, Barron’s reported a fresh upgrade to Buy that calls Microsoft the “adult in charge” on AI security.
The rally started with fiscal Q4. Revenue came in at $90.01 billion, ahead of the $87.63 billion estimate. EPS of $4.74 exceeded the $4.2394 consensus. Azure grew 43%, and commercial RPO rose 84% to $678 billion.
Why Bulls See $731 Within Reach
The bull case values Microsoft at $731.61. Management guided Azure growth to approximately 45% in constant currency for fiscal Q1. CFO Amy Hood said “demand continues to exceed available supply.” Microsoft 365 Copilot has passed 30 million paid seats, and net seat additions more than doubled from the prior quarter.
GitHub Copilot revenue grew more than 60% quarter over quarter after the switch to usage-based billing. The most bullish analyst puts fiscal 2028 EPS at $26.

Capex and OpenAI Exposure Are the Risks to Watch
The bear case lands at $535.10. Fiscal 2026 capex rose 79.62% to $115.95 billion, and free cash flow fell 6.46%. Excluding OpenAI, RPO grew only 25%.
Q4 EPS included a $3.2 billion gain on the Anthropic investment. Operating cash flow rose 34.35% for the year. Adjusted for the OpenAI impact, EPS still grew 23%.
Microsoft Carries a Premium Over Alphabet, Amazon and Oracle
Alphabet (NASDAQ:GOOGL) and Amazon (NASDAQ:AMZN) compete directly with Azure through Google Cloud and AWS. Oracle (NYSE:ORCL) is in the same software-infrastructure industry and chasing the same AI capacity contracts.
| Company | Forward P/E | Operating Margin (TTM) |
|---|---|---|
| Microsoft | 25x | 45.1% |
| Alphabet | 23x | 34% |
| Amazon | 24x | 13.7% |
| Oracle | 18x | 35.6% |
Alphabet grew quarterly revenue faster at 24.2% and trades at a lower multiple. Amazon’s retail-heavy mix keeps margins far below Microsoft’s. Oracle grew revenue 29.6% but trades at a discount due to higher beta. Our target means about 30x earnings, reasonable for the highest margins among the four.
Signed Demand Makes the Case for Upside
The 24/7 Wall St. price target is $629.99, with a buy rating and 90% confidence. The $678 billion in signed commercial backlog supports the case.
Upside speeds up if Azure delivers near 45% growth and Copilot monetization compounds. I’d turn conservative if capex keeps rising while free cash flow contracts.
Microsoft’s estimated trading range in coming years comes from the 24/7 Wall St. price target model, if current growth and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $542.92 |
| 2027 | $629.99 |
| 2028 | $695.64 |
| 2029 | $768.13 |
| 2030 | $848.18 |
The projections depend on Microsoft executing on its AI infrastructure strategy. Faster Copilot adoption could push results above this path. A decline in AI spending could pull them below it. All that capex has to be powered, cooled, and networked by somebody, and we featured seven of those suppliers in a free AI infrastructure report.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.