One Big Question Could Determine Where Microsoft Stock Goes Next
Microsoft just spent over $115 billion on capital expenditures, and now everything hinges on whether that bet pays off fast enough to justify the price tag. Azure's trajectory in the next quarter could either validate the bull case or hand…


Shares of the software company now hinge on one question: will the $115.95B it spent on fiscal 2026 capital expenditures keep turning into Azure growth and real returns?
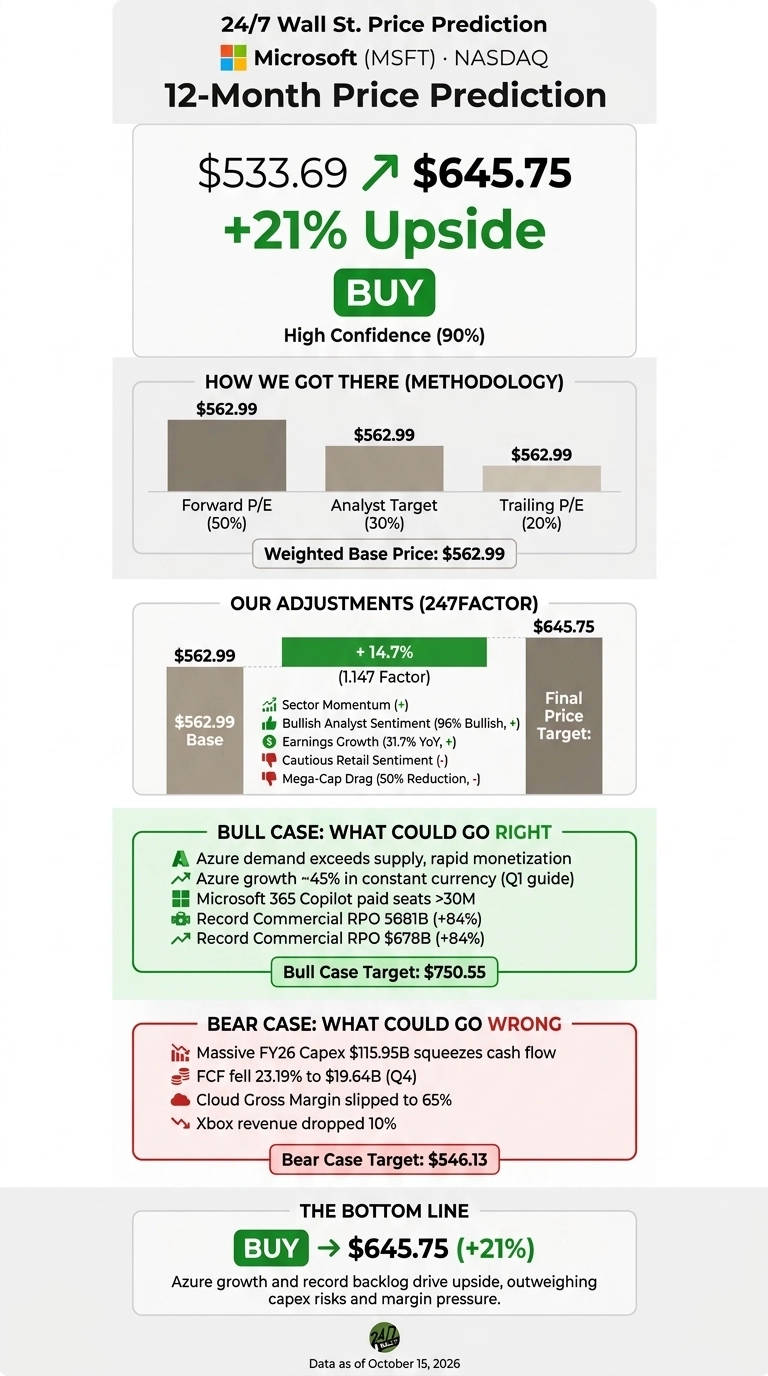
Our 24/7 Wall St. price target for Microsoft (NASDAQ:MSFT | MSFT Price Prediction) is $645.75, which implies 21% upside over the next 12 months.
| Metric | Value |
|---|---|
| Current Price (model reference) | $533.69 |
| 24/7 Wall St. Price Target | $645.75 |
| Upside/Downside | 21% |
| Recommendation | BUY |
| Confidence Level | 90% |
We rate Microsoft a buy with high confidence. Azure grew 43% last quarter, commercial backlog reached $678B, and management guided to Azure growth of about 45% in constant currency for fiscal Q1.
Analysts are almost all positive: 14 strong buy, 39 buy and 2 hold ratings, with no sells. The open question is whether spending pays off as fast as it grows.

Microsoft Has Rallied Hard Since July
Shares changed hands near $537.53 at midday. That’s up 1.47% for the week, 6.36% for the month and 11.85% year to date. It’s also about 36% above the $395.63 close on July 15. The stock sits roughly 2.5% below its 52-week high of $551.15. Barron’s reported today that Wall Street is comfortable with Microsoft even as the AI trade comes under pressure.
The rally started with fiscal Q4 results. Revenue came in at $90.01B, beating the $87.63B estimate. EPS of $4.74 beat expectations of $4.24, with a little help from a $3.2B gain on Microsoft’s Anthropic investment.

Why Bulls See $750 Within Reach
Demand for Azure is still bigger than the capacity Microsoft can supply. CFO Amy Hood said “demand continues to exceed available supply,” and new capacity gets sold almost as soon as it comes online. Paid Microsoft 365 Copilot seats passed 30 million, and net seat increases more than doubled from the prior quarter. Copilot is also adding usage-based pricing on top of per-seat licenses.
In prediction markets, traders assign a 47% chance to Azure growing 46% to 48% in Q1. The consensus analyst target is $589.60. In our bull case, the stock reaches $750.55.

Capex Could Squeeze Cash Flow
Management expects Q1 capex of over $50 billion. Fiscal Q4 free cash flow fell 23.19% to $19.64B, and Microsoft Cloud gross margin slipped to 65%. Xbox revenue dropped 10%.
On the other side, operating cash flow rose 30%, and about two thirds of capex went to short-lived chips that Microsoft can cut back if demand cools (the power, cooling and networking suppliers that benefit from all this data-center spend are the subject of a free report we put together here). The bear case has the stock stalling at $546.13.
How Microsoft Compares to Alphabet and Amazon
Alphabet (NASDAQ:GOOGL) competes directly with Azure through Google Cloud, which grew 82% last quarter. Its P/E of about 15 is held down by a $99.03 billion equity gain, and quarterly free cash flow came in at -$5.855B.
Amazon (NASDAQ:AMZN) is the biggest name in cloud. AWS grew 37%, but Amazon trades at a P/E of about 35, and its trailing free cash flow is negative at -$7.6 billion.
| Company | P/E | Cloud Growth (Latest Qtr) |
|---|---|---|
| Microsoft | 30 | 43% |
| Alphabet | 15 | 82% |
| Amazon | 35 | 37% |
Microsoft is the only one of the three still producing positive free cash flow while spending heavily on AI. Next to these peers, our 24/7 Wall St. price target looks reasonable.
Azure Momentum Makes Microsoft a Buy
A 24/7 Wall St. price target of $645.75 comes with a buy rating and 90% confidence. What decides it for me is the record backlog combined with Azure demand that still exceeds supply.
Azure holding above 40% growth with positive free cash flow keeps the upside case valid. Capex rising while Azure growth slows would undercut the thesis. The current numbers still support the bulls.
Our model projects where Microsoft could trade if current growth trends and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 (by Jan. 2027) | $564.60 |
| 2027 | $646.46 |
| 2028 | $747.90 |
| 2029 | $816.57 |
| 2030 | $901.76 |
These projections rest on Microsoft continuing to carry out its AI strategy. The biggest swing factor is whether returns on AI infrastructure keep up with the capex.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.