Microsoft Has a $1 Trillion Opportunity Hiding in Plain Sight
Azure just crossed a milestone that has analysts quietly raising their ceiling for Microsoft, but the real story is buried in a contract number that almost nobody is talking about.

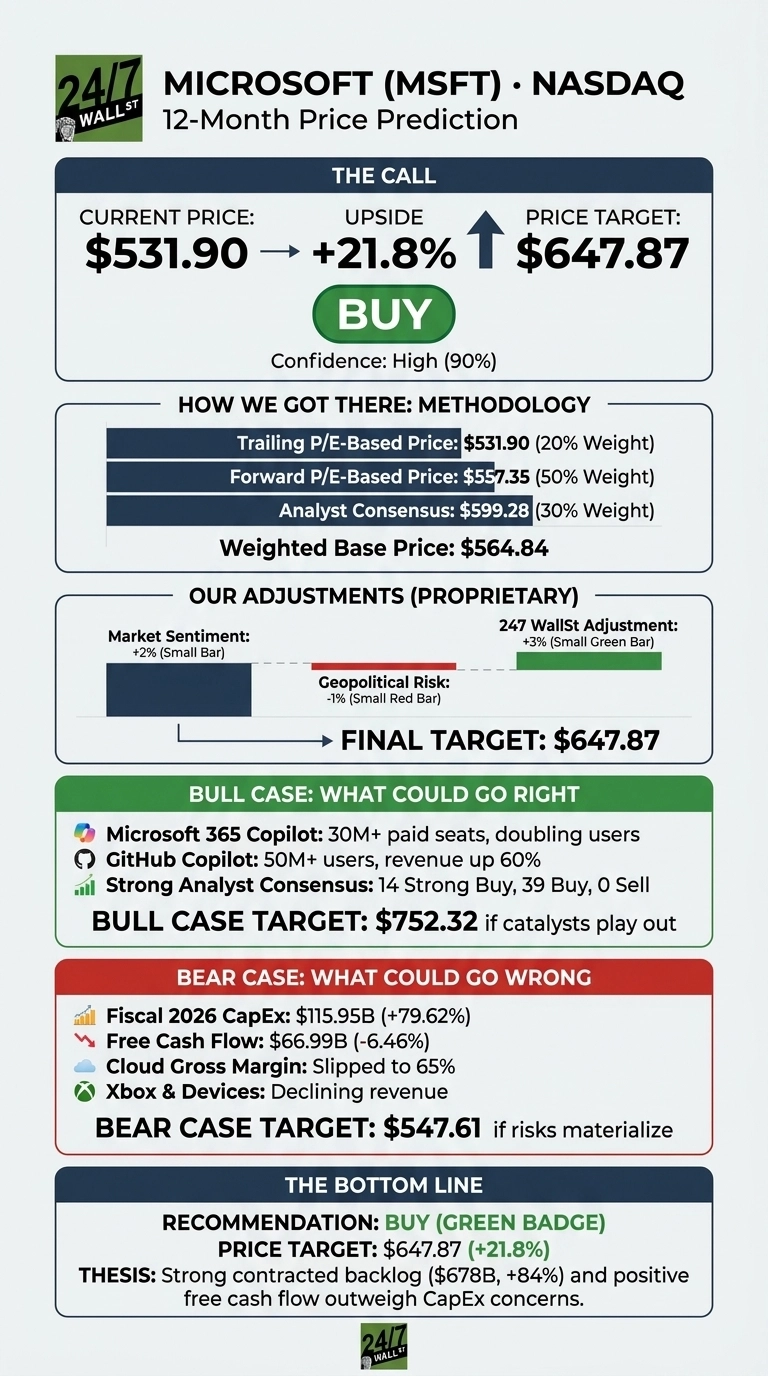
Our 24/7 Wall St. price target for Microsoft (NASDAQ:MSFT | MSFT Price Prediction) is $647.87 over the next 12 months. From a current price of $531.90, that implies 21.8% upside. Our model rates the stock a buy, and we hold that view with high confidence.
| Metric | Value |
|---|---|
| Current Price | $531.90 |
| Price Target from 24/7 Wall St. | $647.87 |
| Upside/Downside | 21.8% |
| Recommendation | BUY |
| Confidence Level | 90% |

The opportunity hiding in plain sight is contracted demand. Commercial remaining performance obligations rose 84% to $678 billion, and the portion recognized beyond 12 months jumped 112%.
Azure exceeded $100 billion in annual revenue, and the CFO said demand “continues to exceed available capacity.” That backlog is the path toward a trillion-dollar cloud and AI franchise.
Azure Acceleration Has Shares Closing In on Their High
Microsoft slipped 2.19% over the past week but gained 7.65% over the past month and 10.61% year to date. It sits about 3.5% below its 52-week high of $551.15 and roughly 52.6% above its low of $348.54.
Fiscal Q4 revenue of $90.01 billion beat the $87.63 billion consensus, and EPS of $4.74 exceeded the $4.2394 estimate. That was the fifth consecutive EPS beat.
Azure grew 43%, and management forecast for about 45% in constant currency this quarter. Away from the fundamentals, Microsoft also joined other blue chips this week in pushing back against efforts to tokenize their stocks.

Copilot Monetization Could Push Shares Toward $752
Our bull scenario reaches $752.32, a 41.44% gain. Microsoft 365 Copilot has passed 30 million paid seats, and net seat adds more than doubled quarter over quarter. Pricing is moving to seat plus usage, which CEO Satya Nadella said makes “the TAM much more expansive.”
GitHub Copilot has reached 50 million users, and Microsoft expects to roughly double its total capacity in two years. Analysts agree: 14 rate the stock Strong Buy, 39 give a Buy rating, and none rate it Sell. Their consensus target is $599.28.

Capex Intensity Is the Risk Worth Watching
Fiscal 2026 capex rose 79.62% to $115.95 billion, while free cash flow fell 6.46%. Microsoft Cloud gross margin slipped to 65%, and Xbox revenue fell 10%. If the worst-case scenario plays out, shares reach just $547.61.
One fair counterpoint is that about two-thirds of capex goes to short-lived CPUs and GPUs, the same supplier network we broke down in a free report on seven companies powering the AI buildout beyond the chipmakers.
The CFO said that “if the demand environment changes, you just slow down” that spending. Microsoft also expects to stay free-cash-flow positive in fiscal 2027.

Microsoft Offers Cash Flow That Rivals Are Burning
| Company | Trailing P/E | P/FCF | Latest Cloud Growth |
|---|---|---|---|
| Microsoft | 30 | 59 | 43% |
| Alphabet | 15 | 57 | 82% |
| Amazon | 36 | 368 | 37% |
Alphabet (NASDAQ:GOOGL) is the most direct rival in AI infrastructure. Its low P/E is inflated by a $99.03 billion gain on equity securities, and its free cash flow turned negative at -$5.86 billion.
Amazon (NASDAQ:AMZN) runs AWS, which grew 37%, yet the stock trades at a higher P/E than Microsoft.
Oracle (NYSE:ORCL) has a similar backlog of $664 billion but posted negative free cash flow of -$5.40 billion. Measured against these peers, the 24/7 Wall St. price target looks reasonable, even modest.
Microsoft Earns Its Buy Rating at $647.87
Our 24/7 Wall St. price target of $647.87 carries a buy rating with 90% confidence. What tips the scale is a growing contracted backlog coupled with positive free cash flow.
The case improves if Azure delivers the forecast acceleration and Copilot usage revenue scales. I’d be more cautious if capex keeps rising while Azure growth stalls. For now, I think the backlog more than supports the spending.
| Year-End | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $556.15 |
| 2027 | $668.29 |
| 2028 | $777.13 |
| 2029 | $828.35 |
| 2030 | $900.53 |
These estimates rely on Microsoft continuing to carry out its current AI strategy. The biggest swing factors are faster Copilot usage monetization on the upside and a slowdown in AI demand on the downside.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.