Chevron Is Up 59% This Year and Trades Above Its Price Target. Time to Take Profits?
Chevron just blew past every analyst price target on the street after a blowout quarter fueled by record refining profits, but one model is flashing a sell signal with unusual conviction. Here is what the bulls are missing.


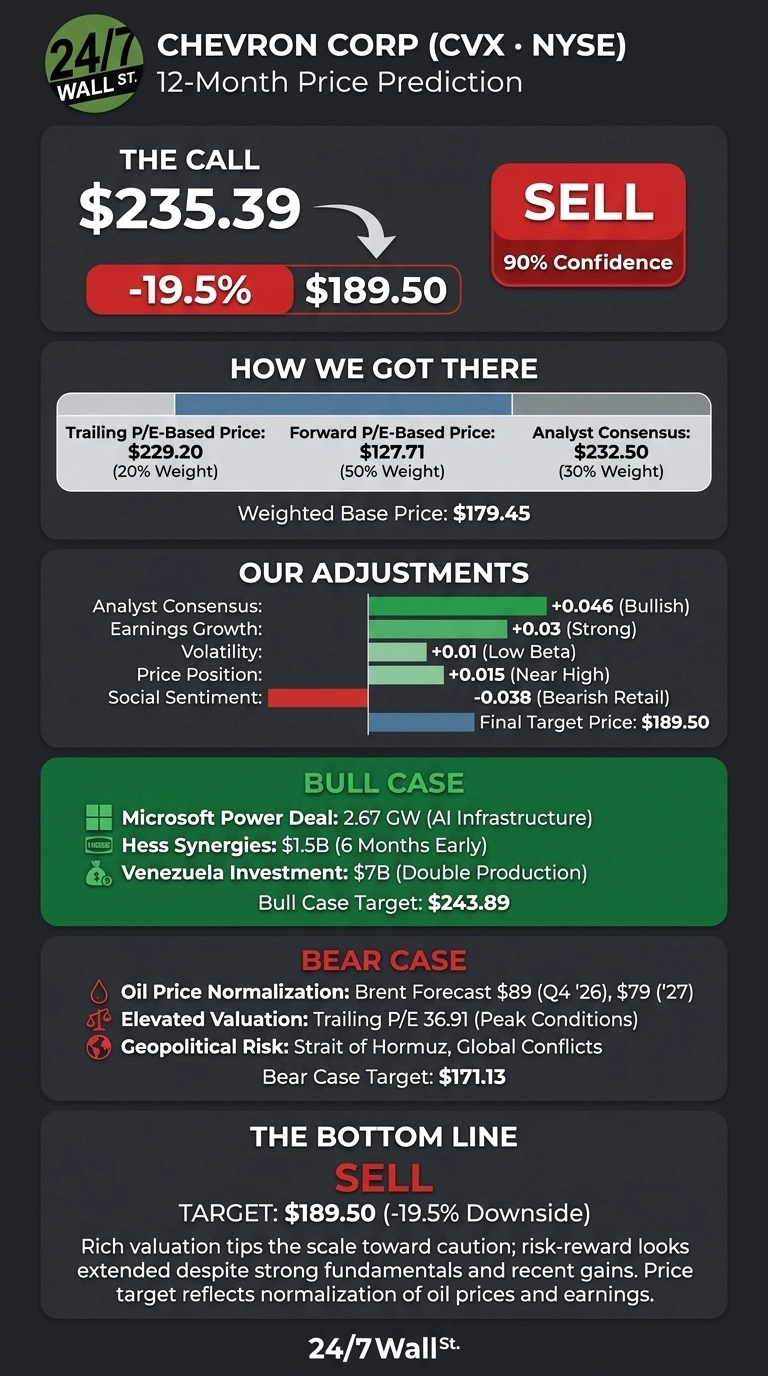
The 24/7 Wall St. price target for Chevron (NYSE:CVX | CVX Price Prediction) is $189.50. That is about 19.5% below this morning’s price of $235.39. The stock is up 58.74% year to date. Our model rates it a sell with 90% confidence.
| Metric | Value |
|---|---|
| Current Price | $235.39 |
| Price Target from 24/7 Wall St. | $189.50 |
| Upside/Downside | -19.5% |
| Recommendation | SELL |
| Confidence Level | 90% |

Chevron’s fundamentals look strong. Our concern is valuation. The stock now trades above the consensus analyst target of $232.50, which means Wall Street’s own math has fallen behind the rally.
Our model expects earnings to normalize as oil prices cool, so it places most of its weight on forward earnings power and less on what investors are paying today.
Why We Could Be Wrong
Our target is well below where Chevron trades, and the bull arguments carry real weight. Upside could come from Project Kilby, the Microsoft (NASDAQ:MSFT) power deal, or from Brent staying high for longer than forecasts assume.
Treat our 24/7 Wall St. price target as one data point among many. The bull case below lays out how Chevron could beat our model.
Record Refining Profits Push Chevron to New Highs
Over the past week Chevron gained 3.84%. It rose 15.17% over the past month and 21.4% over the past quarter. That run took the stock past its prior 52-week high of $234.08 and far above its low of $142.51.
In this morning’s third-quarter report, adjusted EPS came in at $5.28, ahead of the $4.83 estimate. Revenue of $65.24 billion beat expectations and rose 35.4% from a year earlier.
Diesel prices drove much of the gain, as Chevron and Exxon Mobil (NYSE:XOM) both reported sharply higher refining profits according to CNBC. U.S. downstream earnings reached $3.58 billion, up from $638 million. Brent averaged $97 per barrel, compared with $69 a year ago.
Why Bulls See More Room to Run
Chevron captured $1.5 billion of Hess synergies six months ahead of schedule. It also hit its $3 billion structural cost target early. Project Kilby, a 2.67 gigawatt power agreement with Microsoft, is expected to earn “mid-teens returns” that do not depend on oil prices.
That Kilby deal is a reminder that the AI expansion runs on power, cooling, and fuel supplied by names outside the chip sector (we covered seven of them in a free report here).
Venezuela adds more upside through a planned $7 billion joint venture investment. Management also targets adjusted free cash flow growth of greater than 10% per year through 2030, and that target assumes lower commodity prices.
Analysts lean bullish, with 20 Buy or Strong Buy ratings and just one Sell. The bull scenario reaches $243.89.

Oil Price Normalization Is the Risk Worth Watching
This year’s earnings depend heavily on oil prices that have been pushed up by the conflict around the Strait of Hormuz. The EIA projected that Brent would fall to $89 in the fourth quarter of 2026 and $79 in 2027. At 22x trailing earnings, Chevron is priced for peak conditions to last.
GAAP results also included a $160 million legal reserve and a $110 million impairment. In fairness, those charges are mostly non-recurring. Chevron also cut net debt by $7.8 billion in the quarter, which improves the balance sheet. In our bear scenario, the stock falls to $171.13.

How Chevron Compares to Exxon Mobil and ConocoPhillips
| Company | Forward P/E | Dividend Yield |
|---|---|---|
| Chevron | 17x | 3.06% |
| Exxon Mobil | 15x | 2.27% |
| ConocoPhillips | 14x | 2.21% |
Exxon Mobil is the closest integrated rival and had the same diesel-driven quarter. Its adjusted EPS of $4.23 beat the $3.981 estimate. Even so, Exxon trades at a cheaper forward multiple than Chevron.
ConocoPhillips (NYSE:COP) shows what pure upstream exposure looks like, without refining. It also trades at the lowest forward multiple of the three. Both peers trade at a discount, which makes the 24/7 Wall St. price target look reasonable. Chevron’s higher yield partly explains its premium.
Rich Valuation Tips the Scale Toward Caution
Our 24/7 Wall St. price target is $189.50, with a sell rating and 90% confidence. The deciding factor is the premium multiple sitting on top of peak-cycle earnings.
I would turn more constructive if Kilby reaches a final investment decision and Brent holds near current levels. If oil follows the EIA’s forecast lower, I would expect the stock to give back gains. At these levels, the risk-reward looks extended to me.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $221.87 |
| 2027 | $188.52 |
| 2028 | $172.97 |
| 2029 | $169.29 |
| 2030 | $167.79 |
They rest on Chevron continuing its current strategy as oil prices normalize. How the Middle East supply disruption plays out and how quickly Kilby scales could push results well above or below these levels.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.