This Magnificent 7 Stock Is Quietly Building an AI Empire
Azure is accelerating, Copilot adoption is surging, and a $677 billion commercial backlog sits on the books, yet a massive capex bill threatens to swallow the gains before investors ever see them.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

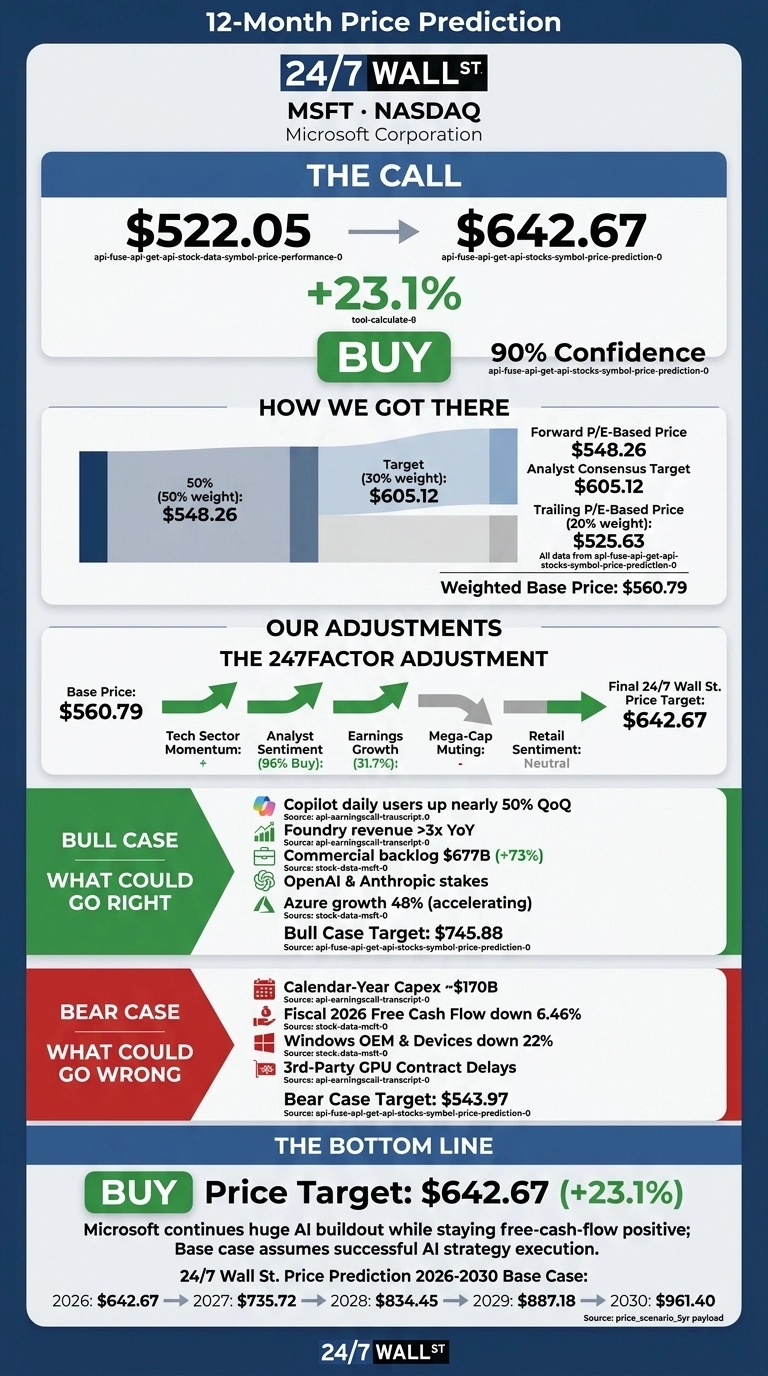
Microsoft (NASDAQ:MSFT | MSFT Price Prediction) traded at $522.05 Friday morning, down 1.53% on the session. Our own model sets the 24/7 Wall St. price target at $642.67 over the next 12 months. That means 23.1% upside. Our rating is buy, and the model has high confidence in it.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $522.05 |
| Price Target from 24/7 Wall St. | $642.67 |
| Upside/Downside | 23.1% |
| Recommendation | BUY |
| Confidence Level | 90% |

Analyst sentiment is strongly positive. Microsoft has 14 Strong Buy and 39 Buy ratings against just 2 Holds, and Barron’s reported Friday that Wall Street remains comfortable with Microsoft even as the AI trade skids.

Azure Growth Hits 48% as Microsoft Beats Again
Over the past week the stock is up 0.19%. It has gained 2.57% over the past month and 8.63% year to date, but it is still down 2.8% over one year. Shares sit 5.3% below the 52-week high of $551.15.
Microsoft reported fiscal first-quarter results on October 28. Revenue rose 18.8% to $92.28 billion, beating the $90.75 billion estimate. Non-GAAP EPS of $4.89 exceeded the $4.72 consensus, making it the sixth consecutive beat. Azure grew 48%, and management forecast next-quarter Azure growth to 49% to 50% in constant currency.

Why Bulls See $745 Ahead
The bull case reaches $745.88. Daily Copilot users rose nearly 50% quarter over quarter, and Foundry revenue grew more than threefold.
Commercial backlog reached $677 billion, up 73%. Microsoft also holds stakes in OpenAI and Anthropic. CEO Satya Nadella said, “I’ve never been more confident in the long-term returns for our investments.”

A $170 Billion Capex Bill Is the Risk to Watch
The bear case sits at $543.97. Calendar-year capex is expected to reach about $170 billion. Fiscal 2026 free cash flow fell 6.46%, Windows OEM and Devices revenue dropped 22%, and some third-party GPU contracts have slipped into the second half of the fiscal year.
Offset by that, operating cash flow rose 28.73% to $58 billion, and CFO Amy Hood said “customer demand continues to exceed available supply.”
How Microsoft Compares to Alphabet and Amazon
Alphabet (NASDAQ:GOOGL) competes directly with Microsoft in cloud and frontier AI models. Google Cloud grew 103%, and the stock trades at a cheaper trailing P/E of 13. However, Alphabet’s third-quarter free cash flow was negative $9.065 billion.
Amazon (NASDAQ:AMZN) owns AWS, Azure’s largest rival, which grew 39%. Amazon trades at 34 times trailing earnings and expects about $220 billion in 2026 capex.
Microsoft’s trailing P/E of 29 sits between the two rivals, and Microsoft still generates positive free cash flow. Against this peer group, the 24/7 Wall St. price target looks reasonable.
| Company | Trailing P/E | Cloud Growth (Latest Qtr) |
|---|---|---|
| Microsoft | 29 | 48% |
| Alphabet | 13 | 103% |
| Amazon | 34 | 39% |
Our Verdict on Microsoft’s Upside
My 24/7 Wall St. price target is $642.67, rated buy with 90% confidence. The deciding factor for me is that Microsoft keeps funding a huge AI buildout while staying free-cash-flow positive (and the power, cooling, and networking suppliers riding alongside that spend are the subject of a free report on seven AI infrastructure stocks that aren’t chipmakers).
The argument strengthens if Azure has growth near 50%. The argument weakens if capex keeps rising while backlog stops growing. At current levels, the model’s base case points to further upside.
If current trends hold, here is the model’s base-case path for each year’s 12-month price target.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $642.67 |
| 2027 | $735.72 |
| 2028 | $834.45 |
| 2029 | $887.18 |
| 2030 | $961.40 |
The projections rest on Microsoft continuing to execute its current AI strategy. Turning Copilot usage into faster revenue growth could push the stock higher. Weaker returns on capex could pull it lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.