Apple Vs. Tesla: Low CapEx Only Matters if Non-Cyclical Cash Flows Come With It
Apple and Tesla both just reported, and both are spending less than expected. Only one of them has a business that keeps paying when the economy turns, and the other may be setting up for a far bigger bill.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Apple (NASDAQ:AAPL | AAPL Price Prediction) and Tesla (NASDAQ:TSLA) both just reported, and both can point to restrained spending. Apple’s fiscal 2026 capex fell 28.9% to $9.04 billion. Tesla cut its 2026 capex guidance to about $20 billion from $25 billion. Only Apple supports that restraint with cash flow that holds up in a downturn.
Subscriptions Lift Apple While Battery Supply Caps Tesla
Apple’s September-quarter revenue rose 11.7% to a record $114.48 billion. iPhone revenue climbed 17% to $57.6 billion. Services hit an all-time high of $31.6 billion at a 76% gross margin. That is the durable part of the business: more than 1.5 billion paid subscriptions running on 2.5 billion active devices. New CEO John Ternus called that base “the foundation for future growth.”
Tesla’s revenue was flat at $28.05 billion. GAAP operating income fell to $718 million from $1.62 billion as autonomy spending outpaced car profits. Battery supply held deliveries to 486,532 even with the biggest backlog in four years. CFO Vaibhav Taneja summed it up: “We are in a huge investment cycle to set us up for the future.”
| Business Driver | Apple | Tesla |
|---|---|---|
| Recurring Engine | 1.5B+ paid subscriptions | 1.74M FSD subscriptions |
| Quarterly Capex | $2.24B | $4.73B |
| Operating Cash Flow | $28.1B | $6.26B |
Light Capex Pays Off When Customers Keep Paying
Apple relies on third parties for components and manufacturing. That kept fiscal 2026 operating cash flow of $145.10 billion far above capex and paid for $28 billion of shareholder returns in the quarter. Subscriptions keep that cash coming in between iPhone launches.
Tesla’s lower guidance looks more like a pause. Management said capex “for the next few years would continue to expand,” and Elon Musk put spending on Terafab, Tesla’s planned chip fab, at “certainly in the tens of billions” through early 2028. Tesla also secured up to $30 billion in borrowing capacity. Cars still answer to commodity prices and interest rates. FSD is the closest thing Tesla has to an annuity, and Taneja agreed its recurring revenue is approaching $1 billion. That is bright, but it remains small next to Apple Services.
Memory Costs and Robotaxi Timelines Set the Next Test
My focus will be on Apple’s December-quarter gross margin guidance of 45% to 46%. Memory pricing, which management called “unprecedented,” is pressuring it. iPhone Duo is still short on supply, so holiday upside depends on the supply chain.
You should keep an eye on whether Robotaxi becomes “a big deal by Q3 or Q4 of next year,” as Musk forecast. I would discount that timeline until it shows up in segment results.
Why I Lean Toward Apple for Cash Flow I Can Count On
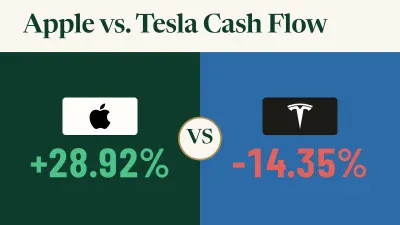
Apple is the cleaner story for me. Its shares are up 28.92% this year, while Tesla is down 14.35%. A free cash flow yield of about 1.94% looks expensive, and memory inflation could pressure margins for several quarters. Still, I prefer low capex supports by subscriptions over a quiet spending year that comes right before a much larger build.
Tesla trades at a P/E near 401 with a 0.41% free cash flow yield. It fits investors willing to fund autonomy before the cash comes. Taneja said Tesla will disclose FSD revenue and churn as the business grows, and those numbers could change my mind.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.