Microsoft Just Overtook NVIDIA. Our Model Sees $650+

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
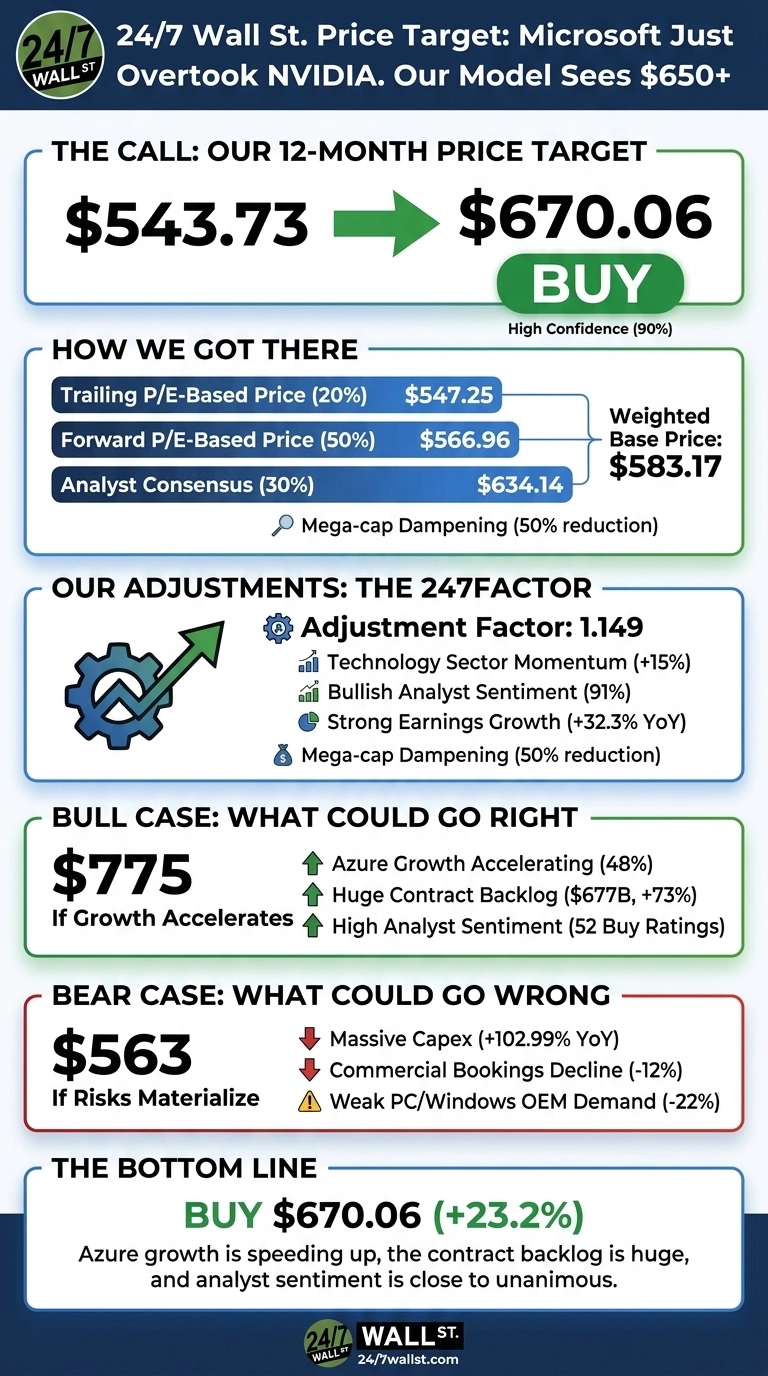
Microsoft (NASDAQ:MSFT | MSFT Price Prediction) now has a market value of roughly $4.05 trillion, which puts it just ahead of NVIDIA (NASDAQ:NVDA) at about $4.04 trillion. The 24/7 Wall St. price target for Microsoft is $670.06. From today’s $543.73, that works out to 23.2% upside.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $543.73 |
| Price Target from 24/7 Wall St. | $670.06 |
| Upside/Downside | 23.2% |
| Recommendation | BUY |
| Confidence Level | 90% |

The market-cap lead is narrow enough to change hands within a single session. What drives the stock is more durable. Azure growth is speeding up, the contract backlog is huge, and analyst sentiment is close to unanimous. Microsoft earns a buy rating with high confidence from the model.
Azure’s 48% Surge Extends a Six-Quarter Beat Streak
Shares rose 7.22% over the past week and 1.62% over the past month. They are up 13.14% year to date. The stock sits 2.8% below its 52-week high of $559.15 and 56% above its low of $348.54.
Fiscal Q1 2027 extended a six-quarter run of EPS beats. Revenue came in at $92.279 billion, ahead of the $90.751 billion estimate, and non-GAAP EPS of $4.89 topped the $4.72 consensus. Azure grew 48%, and commercial remaining performance obligations reached $677 billion, up 73%.

Why Bulls See $775 in Reach
Our bull case lands at $774.71. For next quarter, management guided Azure growth to 49% to 50% in constant currency. On the call, CFO Amy Hood said, “Customer demand continues to exceed available supply.”
Foundry revenue more than tripled, and daily Copilot users rose nearly 50% quarter over quarter. Analysts are in step: 12 Strong Buy, 40 Buy, 5 Hold and zero Sell ratings, with a consensus target of $636.12.


Capex and PCs Are the Pressure Points
Our bear case is $563.15. Quarterly capex jumped 102.99%, and calendar-year spending is expected to reach about $170 billion (much of that goes to the infrastructure suppliers we profiled in a free AI infrastructure report here).
Commercial bookings fell 12%, and management guided Windows OEM revenue down in the mid-30s. There are offsets. The bookings decline shows large Azure commitments in the prior year. Operating cash flow rose 29% to $58 billion, and Microsoft expects to stay free cash flow positive in fiscal 2027.
How Microsoft Compares to Alphabet and Amazon
Alphabet (NASDAQ:GOOGL) earns its place because Google Cloud competes directly with Azure for AI workloads. Google Cloud grew 103%, but Alphabet’s free cash flow fell to negative $9.065 billion. Its low P/E is inflated by a $99 billion equity gain, so it understates how the market prices Alphabet’s core business.
Amazon (NASDAQ:AMZN) runs AWS, the largest rival cloud. AWS grew 39%, but Amazon trades at a higher P/E and runs a far thinner operating margin than Microsoft.
| Company | P/E | Cloud Growth | Operating Margin |
|---|---|---|---|
| Microsoft | 30 | 48% | 46.78% |
| Alphabet | 13 | 103% | 32.03% |
| Amazon | 37 | 39% | 11.16% |
Microsoft has the highest margin of the three and trades below Amazon’s multiple. Against that peer set, our target looks reasonable.
Microsoft Earns Its BUY Rating
The 24/7 Wall St. price target of $670.06 has a buy rating at 90% confidence. The deciding factor is Azure growth that keeps speeding up while margins hold.
The case gets stronger if Azure hits its guidance and delayed GPU capacity arrives in the second half. It gets weaker if capex starts outpacing revenue.
Over the longer term, here is where our model projects Microsoft could trade if current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $563.73 |
| 2027 | $669.82 |
| 2028 | $782.76 |
| 2029 | $878.02 |
| 2030 | $931.13 |
These estimates assume Microsoft stays on its current path. Faster Copilot adoption could push results higher, while AI spending that fails to earn its keep could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.