Microsoft Price Prediction: Analysts’ Target Clears the 52-Week High

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
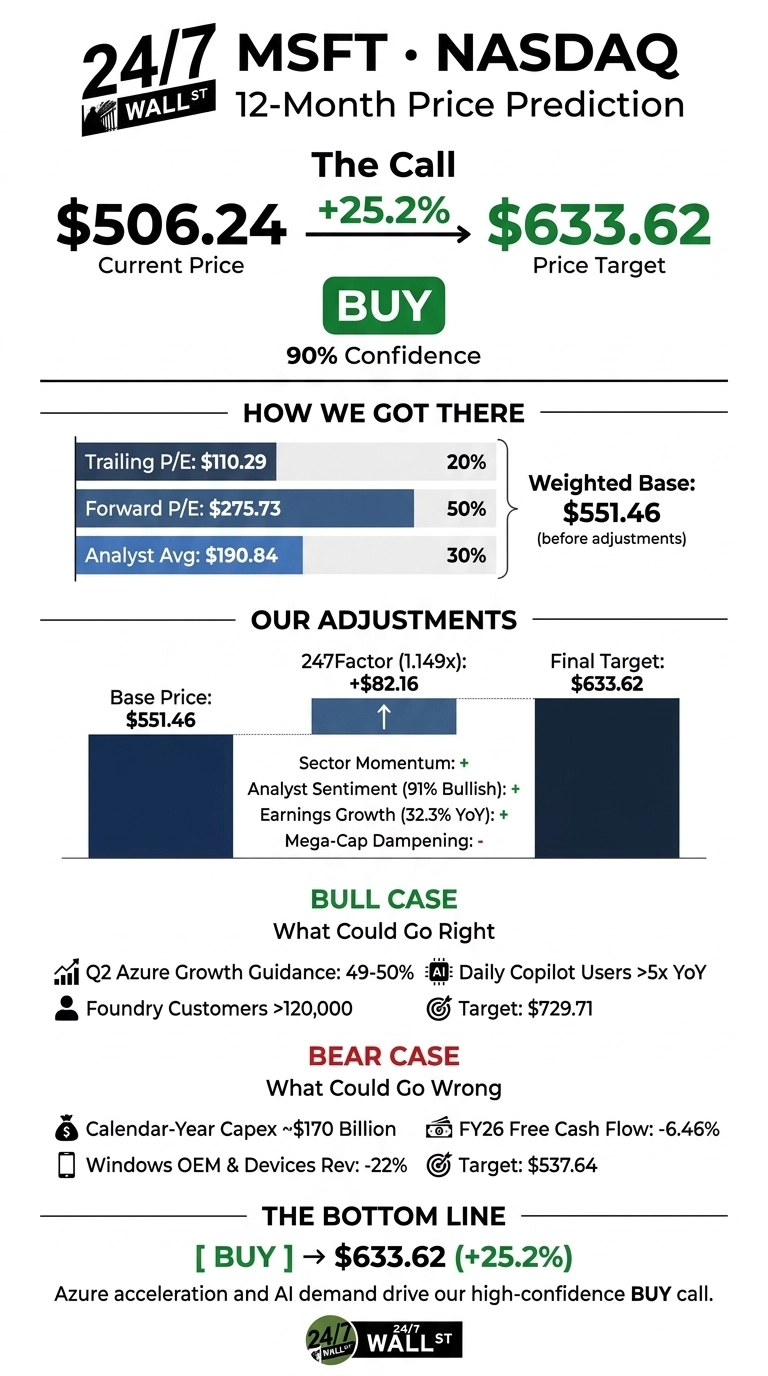
Our 24/7 Wall St. price target for Microsoft (NASDAQ:MSFT | MSFT Price Prediction) is $633.62 over the next 12 months. That implies 25.2% upside from the latest close of $506.24. Our model rates the stock a buy, and its confidence in the call is high.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $506.24 |
| Price Target from 24/7 Wall St. | $633.62 |
| Upside/Downside | 25.2% |
| Recommendation | BUY |
| Confidence Level | 90% |

Wall Street’s consensus target of $636.12 sits 13.8% above the 52-week high of $559.15. Shares, meanwhile, trade 9.5% below that peak.
Our target lands within a few dollars of consensus. Fiscal Q1 2027 supports it, with Azure growth of 48%[1] and commercial remaining performance obligation (RPO, or contracted future revenue) of $677B.
Outage Headlines Hit a Stock Coming Off a Strong Quarter
Over the past week Microsoft fell 5.05%, and over the past month it lost 4.31%. That includes a 2.27% drop on November 17. On November 13, the WSJ reported that the stock fell after a widespread outage. Over longer periods the picture improves: shares are up 5.31% over the past quarter, up 5.34% year to date and 45.2% above the 52-week low of $348.54.
Microsoft reported fiscal Q1 2027 results on October 28[1]. Revenue was $92.279B[1], beating estimates of $90.751B, and non-GAAP EPS was $4.89 against $4.72 expected. Microsoft Cloud revenue rose 30%[1] to $63.9B.
Why Bulls See $729 and Beyond
Management guided Q2 Azure growth to 49% to 50% in constant currency[2]. Foundry, Microsoft’s platform for building AI apps and agents, now has more than 120,000[2] customers, and its revenue more than tripled. Daily Copilot users grew over 5x year-over-year[2].
On the call, CEO Satya Nadella said, “Demand continues to exceed available supply.”[2] Among analysts, 12 rate the stock Strong Buy, 40 rate it Buy and none rate it Sell. The bull case reaches $729.71.

Capex Load and Legacy Drag Are the Risks Worth Watching
Q2 capex is expected to top $50 billion[2], and calendar-year capex should land near $170 billion. That spend flows through to the power, cooling, and networking suppliers behind the data centers (we covered seven of them in a free report on the AI infrastructure buildout).
Fiscal 2026 free cash flow fell 6.46%. Revenue from Windows OEM and devices dropped 22%[1], and commercial bookings declined 12%[2]. Each of these has context.
Management attributed the bookings decline to large Azure commitments in the prior-year quarter. Roughly three-quarters of capex goes to short-lived CPUs and GPUs that serve current demand, and CFO Amy Hood expects free cash flow to stay positive in FY2027. The bear case is $537.64, which is still above today’s price.

Microsoft Sits Between Alphabet and Amazon on Valuation
As it competes with Microsoft for AI-cloud customers, Alphabet (NASDAQ:GOOGL) saw Google Cloud grow 103% last quarter. Its P/E of 12 looks cheap, but an unrealized $99 billion equity gain in Q2 inflated its earnings, and quarterly free cash flow was -$9.065B.
The closest read on hyperscaler spending comes from Amazon (NASDAQ:AMZN). Even with AWS growing 39%, Amazon trades at 36x earnings and 362x free cash flow.
| Company | P/E | P/FCF |
|---|---|---|
| Microsoft | 28 | 56 |
| Alphabet | 12 | 48 |
| Amazon | 36 | 362 |
Microsoft has the highest operating margin of the three at 46.78%. That makes the 24/7 Wall St. price target look reasonable relative to peers.
Fundamentals Favor the Upside Case
The 24/7 Wall St. price target stays at $633.62, rated buy at 90% confidence. What convinces me is Azure growth speeding up while the backlog builds.
I would find the stock compelling if Azure reaches its Q2 guidance and free cash flow stays positive. I’d stay cautious if supply delays drag Azure growth back into the low 40s. Today’s weakness reflects headline risk, while the underlying business keeps strengthening.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $502.28 |
| 2027 | $633.62 |
| 2028 | $708.54 |
| 2029 | $792.33 |
| 2030 | $886.02 |
The projections rest on Microsoft continuing to execute on its current strategy and follow our five-year base case of $990.79. Faster Copilot monetization could lift the path, and capex returns that fall short could pull it lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.