Retirees Who Buy the Model Home in a Big 55+ Community Will Find the Upgrades Were the Whole Price
The brochure price on a 55+ model home is only the beginning, and where that upgrade money comes from can quietly reshape your Medicare bill for years. Before you sign, there are costs most buyers only discover after closing.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
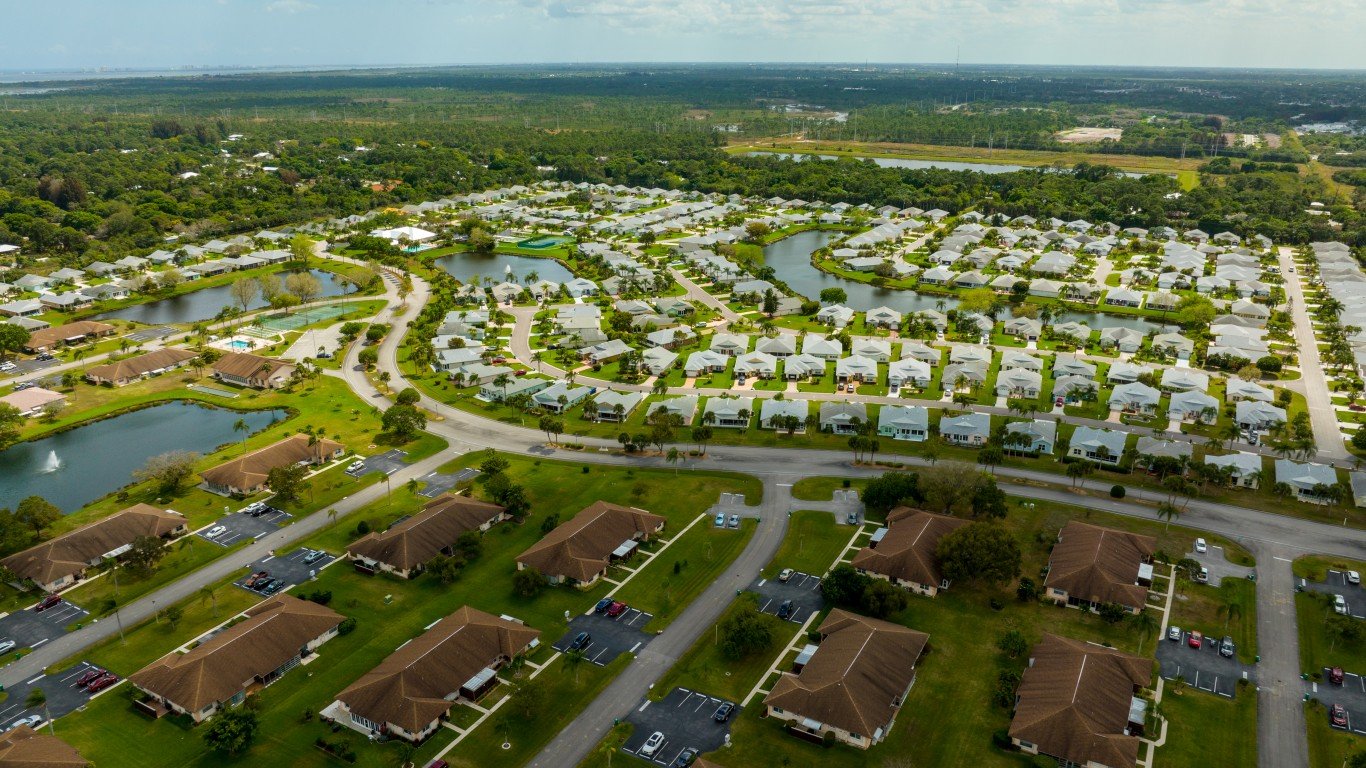
Model homes in big 55+ communities are typically staged with options that appear standard: the quartz island, the extended lanai, the tray ceilings, the paver driveway. A common question for people planning a move to The Villages in Florida or a Del Webb community is: what does this house really cost, and how big a portfolio does it take to retire into it comfortably? The brochure price is the starting point for a stripped-down version of what’s on display, but there is more to the story.
Pricing the House as Shown, Plus the Community Layer
Builders fill their models with the options that sell, and that package is what buyers typically see. For this example, assume the shown version carries $100,000 in upgrades, lot premium, and finishes on top of base.
The community layer adds further costs. New buyers in The Villages pay a monthly amenity fee of $204 (about $2,448 a year), and newer homes there carry infrastructure bonds of about $25,000 to $30,000. In the newest villages, this rises to $30,000 to $50,000+. At Del Webb Lakewood Ranch, HOA fees run about $320 to $420 per month.
Florida’s tax structure favors retirees, as the state ranks No. 1 for individual income tax and No. 5 overall in the 2025 State Tax Competitiveness Index. The homestead exemption reduces taxable value by up to $50,000, and Save Our Homes limits annual increases in assessed value to 3% or inflation, whichever is less. That cap only starts counting from a purchase price that already includes every upgrade.
| Annual Line Item (Couple) | Amount |
|---|---|
| Amenity fee | $2,448 |
| Property tax, homeowners and wind insurance (assumed) | $9,000 |
| Maintenance and replacement reserve (assumed) | $6,000 |
| Medicare Part B, two people at $202.90 each | $4,870 |
| Medigap, Part D, dental, out-of-pocket (assumed) | $10,000 |
| Food, utilities, vehicles, golf cart, travel, gifts, personal, emergency reserve and taxes on withdrawals (assumed) | Remainder of total |
| Total | $90,318 |
Turning the Budget Into a Portfolio Target
After the 3.6% COLA for 2027, the Social Security Administration estimates an aged couple both drawing benefits will average $3,355 a month, or $40,260 a year. That leaves $50,058 a year for the portfolio to cover. At a 4% draw, the target is $1,251,450. A couple in their early 60s can reasonably plan for 30 years or more, so a 3.5% rate fits better, which raises the target to about $1.43 million. The upgrades and the bond are also paid at closing. That brings the totals to $1,381,450 and $1.56 million.
Taking Social Security later changes the answer more than anything else here. Waiting from full retirement age (67) to 70 raises benefits by 24%. If the couple’s combined benefit grew by that much, to about $49,922, the 4% target would drop to around $1.01 million. One way to cover those three years is a dedicated treasury ladder.
How Paying for Upgrades Can Raise a Couple’s Medicare Bill
Buyers can miss how the upgrade money comes out of their accounts. Say the $100,000 comes from a traditional IRA in one tax year. It all counts as ordinary income. Medicare sets Part B premiums from the tax return filed two years earlier, and depending on income, those premiums run from $202.90 to $689.90 per person each month.
The highest level would cost a couple $16,558 a year instead of $4,870, a $11,688 jump. Most couples land in a lower surcharge level, but a lump withdrawal stacked on Social Security can still trigger one. Paying from proceeds from selling the old home, from a taxable account or Roth money, or spreading withdrawals across two tax years can avoid most of it.
Resale is the other hidden cost. U.S. home prices rose just 1.5% year over year on the Case-Shiller index. In a community still under construction, a used home also competes with brand-new houses that come with this year’s features. Many owners also find that paying off the bond early typically does not mean you automatically get that money back at resale.
What It Takes to Afford the Model Home
A couple receiving typical Social Security benefits needs around $1.4 million to $1.56 million in investable assets. That covers a working budget near $90,000 a year at a 3.5% draw, plus the upgrades and bond paid upfront. Taking at 70 and funding the gap years with Treasury bonds substantially reduces the requirement.
The remaining assets would need to slightly beat inflation to support a 3.5% draw (we laid out why the old 4% rule should be retired, and what to run instead, in a free report). Buyers who price the house exactly as shown and identify which accounts will fund the upgrades before signing have a cleaner view of total costs. The source of that money affects Medicare premiums two years later.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.