Retirees Who Pick a Big 55+ Community for the Golf Will Learn What the Course Costs Once They Stop Playing
Golf fees in a 55+ community look like a bargain compared to a private club, but the math changes sharply once the clubs go into storage and those fees keep pulling from the portfolio for years.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
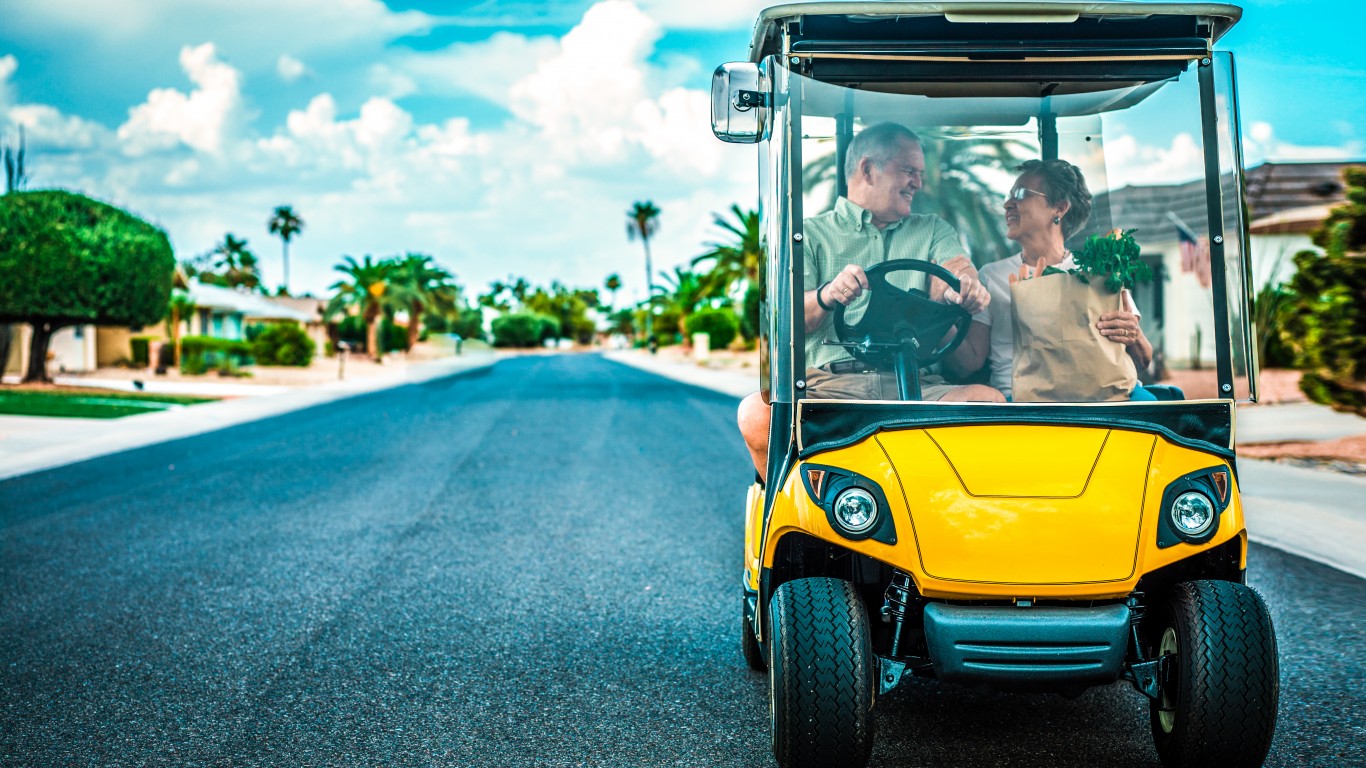
It won’t surprise you to learn that many golfers share the same retirement plan. The plan starts with selling the house up north, buying into one of the big age-restricted communities in Florida or Arizona, and living a cart ride from the first tee for less than a country club would cost. Planning for that move can focus on years of regular play, while fees continue into later retirement, when clubs are sold, and every fee is still due. What matters most is that everyone considering this move goes through the budget, their portfolio target, and the part of the golf bill that keeps coming after the golf ends.
What a Golf Community Budget Really Covers
The Villages in central Florida is a useful reference. New buyers there pay a monthly amenity fee of $204, which works out to $2,448 a year. Residents pay no green fees on the executive courses, but they pay a trail fee to use a golf cart, and the championship courses charge their own green fees. Community development district charges appear on the property tax bill and typically range from about $1,600 to over $6,000 per year, depending on the section.
Healthcare for a couple on Medicare starts with the standard Part B premium of $202.90 a month each, or about $4,870 a year before extra coverage and drug plans. Groceries on the USDA moderate plan run about $770 to $850 a month for two adults. For the full budget, a reasonable anchor is the BLS Consumer Expenditure Survey’s average annual household spending: $78,535 in 2024.
That total must cover the fees above, plus property insurance, maintenance, golf car replacement, taxes on withdrawals, and an emergency reserve. Because Florida has no state income tax, the tax line covers federal tax on IRA withdrawals and the taxable portion of Social Security.
Turning the Budget Into a Portfolio Number
After the 2027 COLA of 3.6%, the SSA estimates the average aged couple will collect $3,355 a month, or $40,260 a year. Subtracting that from the budget creates a $38,275 shortfall. Closing that shortfall with a 4% withdrawal rate takes about $957,000. A couple retiring at 62 and planning for 30 years or more might use 3.5% instead, which increases the target to about $1.09 million. Delaying Social Security adds delayed retirement credits and narrows the gap, though the portfolio must cover the full budget until benefits start.
Inflation also matters here, since in September the CPI ran 3.7% above a year earlier, slightly faster than the COLA.
Paying for Fairways After the Last Round
The amenity fee is tied to the house, and the owner pays it whether or not anyone in the house still plays. Funding $2,448 a year at 4% ties up about $61,200 of the portfolio, and that money keeps paying for courses long after the owner’s last round. A surviving spouse sees Social Security fall toward the average widow(er) benefit of $2,005 a month, or $24,060 a year. The fee doesn’t change, and it now equals about 10% of the survivor’s benefit.
Downsizing inside the community can increase the fee. A move into a smaller villa resets the fee to that year’s current rate. If that rate keeps rising at 5.1% a year, a $200 fee grows to about $539 a month over 20 years, and funding that would take roughly $161,700 at 4%.
Of course, golf courses can also run into financial trouble. One industry example described a community of 2,000 homes with a course that lost $400,000 a year, with an annual assessment of $200 per home. That assessment amounts to about $5,000 in capital per household. Closing the course instead can reduce property values. The national Case-Shiller home price index is at 337.3, but a national number says little about how easily a golf-course home in a specific 55+ community will sell.
What It Takes to Make the Math Hold
For a couple spending close to the national average and drawing typical Social Security benefits, the target lands between about $957,000 and $1.09 million in investable assets on top of home equity. The lower number assumes a 4% withdrawal rate each year. The higher number assumes a 3.5% withdrawal rate, which suits retirements starting in the early 60s. Withdrawals at that pace assume portfolio returns of roughly 3.5% to 4% a year after inflation.
Because the fees are tied to the house, they act as fixed costs that last until the house sells. Covering today’s amenity fee takes about $61,200, more if a downsizing is likely, and the budget also has to hold up on a single survivor’s Social Security. Golf draws many buyers to these communities, and the fees continue even after play stops.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.