Three Costs to Price Before Retiring to the Mountains: Winter Access, the Drive to a Hospital and Insurance

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
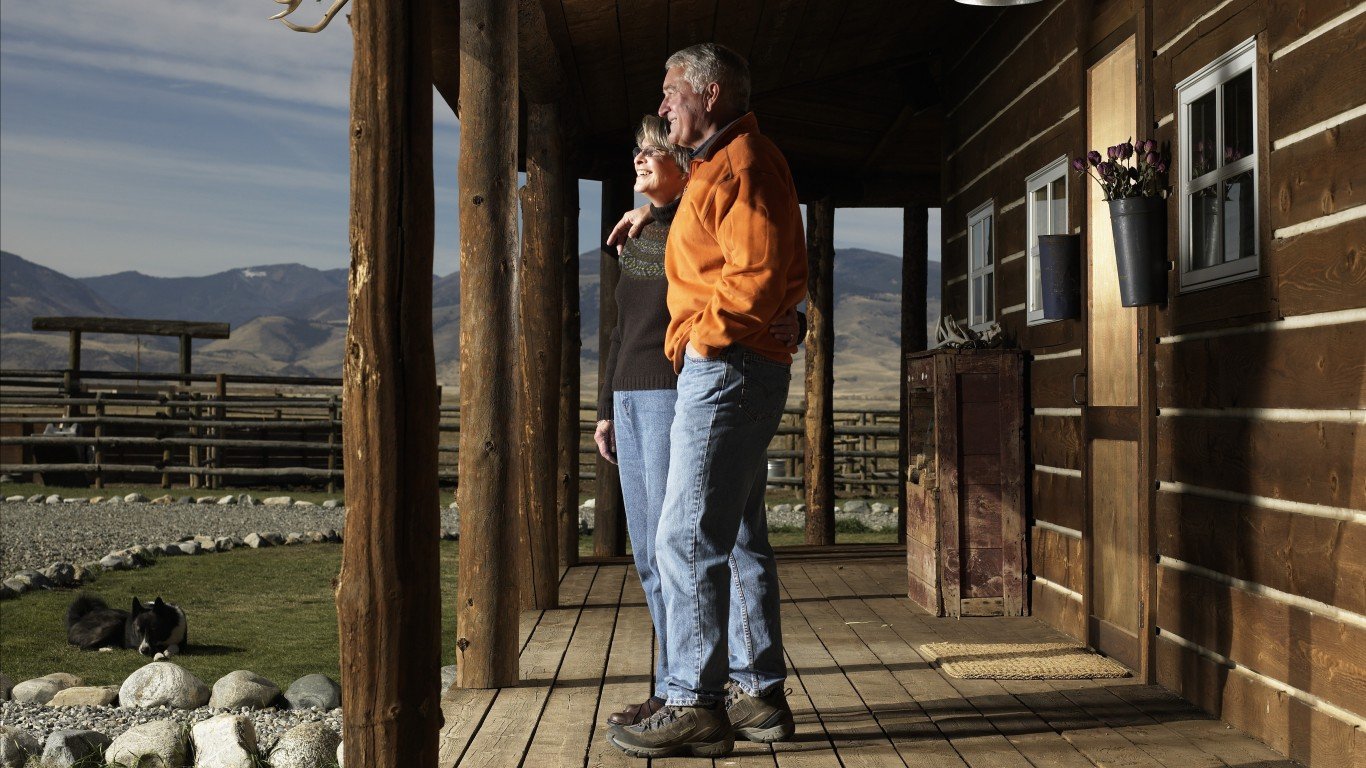
A mountain cabin with a west-facing porch can carry a price that looks fair next to what a suburban house would sell for. Buyers often run retirement numbers on the spot, and fewer ask the February question: what happens when the road is buried, the nearest real hospital is an hour away, and the insurer won’t renew?
Those three costs sit outside the listing price, and you can price each before closing.
Who Plows the Road Sets the Winter Budget
The county road department can answer the key question: is this road publicly maintained, and to what standard? Many mountain homes sit on private roads, where plowing, grading, and culvert repair fall to the owners. That cost usually gets split through a road maintenance agreement, a recorded document that divides the bill among neighbors. Buyers typically review it before closing, and if no agreement exists, plowing depends on neighbors volunteering to share the cost.
On the equipment side, a four-wheel-drive vehicle with real snow tires becomes a fixed line item, as do a plow contract, a generator, and enough food and fuel to sit tight for days. Fuel prices swing, too, with the national average for regular gas sitting at $3.81[1] a gallon in mid-November, down from a September high of $4.478.
Mapping the Winter Drive to a Full-Service Hospital
Two drive times matter: one to the nearest hospital and one to the nearest full-service hospital with cardiac care, a trauma designation, and specialists, because those are often two different buildings. A small rural hospital can stabilize a patient and then transfer them. Both routes take longer in snow, and the snow-season figure is the real drive time.
Rural hospital closings are continuing: Forbes reported this week that more than 100 rural hospitals have closed over the past decade, leaving an estimated four million Americans without timely access to care. Public Citizen calculated that the new $50 billion rural fund equals 37% of the estimated loss in federal Medicaid funding to rural areas over 10 years. Hospitals that serve rural retired people today face continued closure risk.
Distance costs money even in a quiet year. The 2027 Part B premium is $209.40[2] a month, about $5,026 a year for a couple, and the inpatient deductible is $1,776. A specialist visit that takes a morning in the suburbs can take a full day from a remote mountain home.
Medicare limits what participating ambulance providers can charge, while federal surprise billing protections cover air ambulances under private insurance. Ground ambulance protections vary by state.
Getting Insurance Quotes Before Making an Offer
In wildfire country, the insurance quote comes before the inspection. Major insurers continue to pull back from high-risk areas, and in California the FAIR Plan acts as the insurer of last resort. It offers basic fire coverage without the breadth of a standard policy, so many owners add a second policy for liability and water damage.
That means two premiums, two renewals, and two chances to get a nonrenewal letter. An agent can provide a written quote, the carrier’s appetite for that ZIP code, and which defensible-space or roof work would change the price.
What the Portfolio Has to Cover
The baseline math starts with household spending. The average household spent $81,905 in 2025. A couple who each draw the average retired-worker benefit, which reaches $2,170 a month after the 3.6% 2027 COLA, receives $26,040 apiece. The gap comes to $29,825. Covering it takes about $745,625 at a 4% withdrawal rate, or roughly $852,000 at 3.5%.
The mountain costs go on top of that. Each $1,000 a year in ongoing cost, whether it’s the owner’s share of the plowing, a second insurance policy, or medical travel, adds about $25,000 to the portfolio target at 4%. That 4% figure itself is doing a lot of work here, and it has drawn fresh examination lately (we laid out the case for an income-first alternative in a free guide: The 4% Rule Is Broken).
Waiting until 70 to claim Social Security reduces the gap for life. That carries extra weight for mountain owners, who face the insurance and healthcare costs outlined above.
Three items in writing set the true cost before an offer: the road agreement, the winter drive time, and the insurance quote. Each yearly cost multiplied by 25 shows its addition to the portfolio target, and the total has to hold up at a 3.5% to 4% withdrawal rate. A house without an available insurance quote leaves the owner exposed at any purchase price.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.