Prediction: Eli Lilly Could Have More Room to Grow Than Its Valuation Suggests
Eli Lilly trades at a premium multiple, yet its revenue growth dwarfs every major pharma peer by a wide margin. Whether that gap justifies buying shares near all-time highs depends on one critical assumption about Lilly's pipeline.


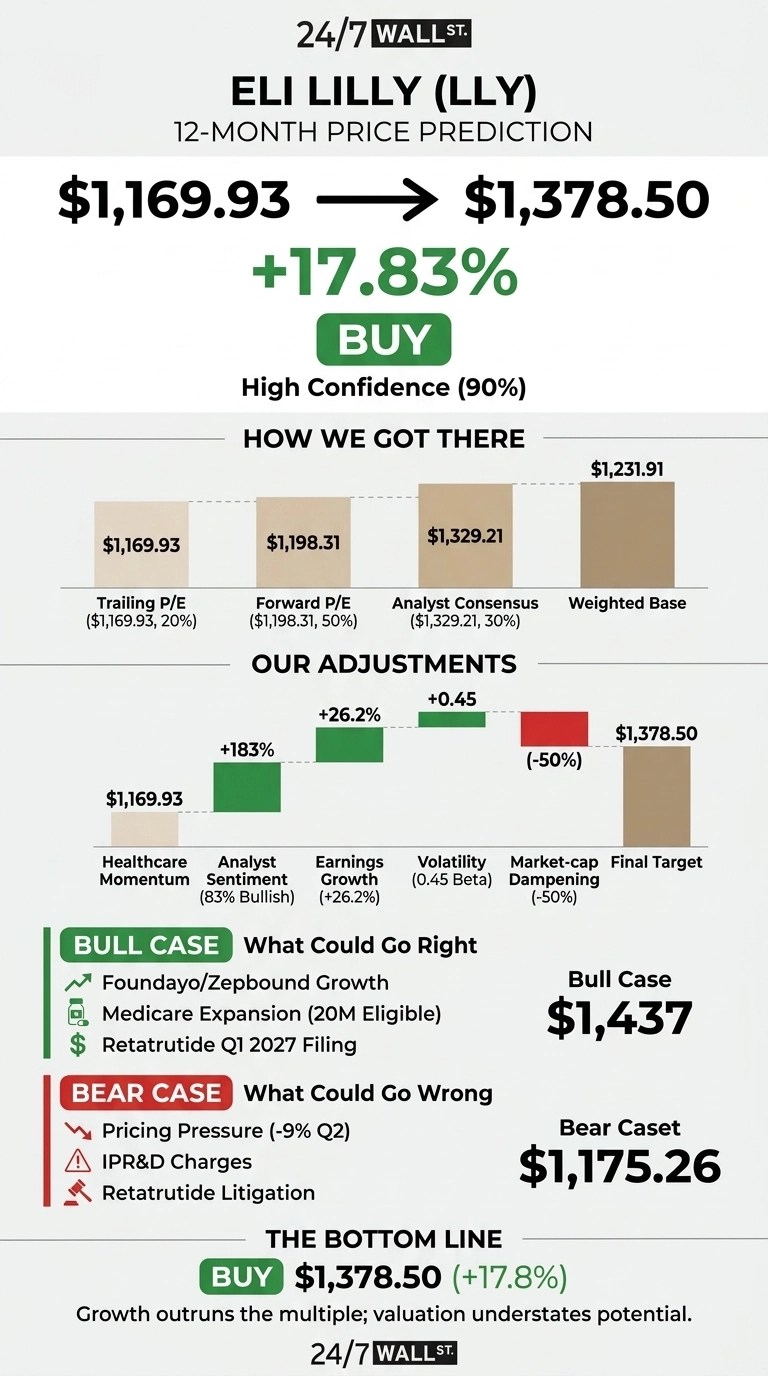
Our 24/7 Wall St. price target for Eli Lilly (NYSE:LLY | LLY Price Prediction) is $1,378.50. That points to 17.83% upside from the current $1,169.93. Our model rates the stock a buy, with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $1,169.93 |
| Price Target from 24/7 Wall St. | $1,378.50 |
| Upside/Downside | 17.83% |
| Recommendation | BUY |
| Confidence Level | 90% |
Lilly trades at 24x forward earnings while revenue grew 47.7% year over year last quarter. For a stock with a trillion-dollar market cap, that multiple looks modest against the growth. Management has raised 2026 revenue guidance twice, to $85B-$87B, and plans to submit retatrutide in Q1 2027.

Lilly Climbs Back Toward Its Highs After Another Guidance Raise
Shares are up 1.81% over the past week, 4.16% over the past month, 9.46% year to date and 39.3% over the past year. The stock sits about 9.5% below its 52-week high of $1,292.65 and 50.2% off its low of $778.94.
Q2 revenue reached $22.97B, ahead of the $20.69B estimate. EPS of $8.38 beat the $6.58 consensus. Mounjaro brought in $9.94B (+91%) and Zepbound $4.93B (+46%).
Since the report, the FDA has approved the once-weekly insulin Onswik and expanded Jaypirca’s label into previously untreated CLL. Lilly has also broken ground on a Houston plant, one of ten U.S. manufacturing sites announced since 2020.

Why Bulls See $1,437 and Beyond
Lilly’s pipeline goes well past Mounjaro and Zepbound. In Q2, Foundayo prescribers grew from about 8,000 to 36,000. Medicare’s GLP-1 Bridge Program now covers 20 million eligible Americans at $50 per month.
Analysts expect 2027 EPS of $47.5925, and the high estimate reaches $54.94. The consensus target is $1,330.25, supported by 6 Strong Buy ratings plus 19 Buy ratings. In our bull scenario, the stock reaches $1,437.

Pricing Pressure Is the Risk Worth Watching
Lilly’s U.S. price fell 9% in Q2 when rebate estimate adjustments are excluded. Management says rising volume will more than offset lower prices, calling the decline “very much embedded in our guide.” Acquired IPR&D charges of $3.03 per share also cut into Q2 EPS.
Those charges came from one-time deals that added to the pipeline. Retatrutide’s filing pathway still faces litigation over how the drug is classified. Analysts include 1 Sell and 1 Strong Sell rating. The bear case is $1,175.26.
How Lilly Compares to Novo Nordisk and AbbVie
Novo Nordisk (NYSE:NVO) is Lilly’s direct GLP-1 rival. The stock trades at 12x forward earnings, but its revenue grew just 2.1% last quarter, and earnings declined 20.6%.
AbbVie (NYSE:ABBV) is a large pharma name with a strong immunology franchise. The shares trade at 16x forward earnings on 10.2% revenue growth.
| Company | Forward P/E | Quarterly Revenue Growth YoY |
|---|---|---|
| Eli Lilly | 24x | 47.7% |
| Novo Nordisk | 12x | 2.1% |
| AbbVie | 16x | 10.2% |
Lilly’s premium multiple comes with several times the revenue growth of either peer. Against that background, the 24/7 Wall St. price target looks reasonable.
Growth Outruns the Multiple, So Lilly Rates a Buy
Our 24/7 Wall St. price target of $1,378.50 carries a buy rating with 90% confidence. What tips the scale for me is earnings momentum.
The case gets stronger if Foundayo keeps gaining share and retatrutide is filed on schedule. It weakens if price cuts start to outpace volume growth. On the current data, I think Lilly’s valuation understates its growth.
Here is where our model projects Lilly could trade at each year-end if current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $1,221.61 |
| 2027 | $1,417.01 |
| 2028 | $1,596.31 |
| 2029 | $1,747.66 |
| 2030 | $1,853.50 |
The projections rest on Lilly continuing to execute its current strategy. Retatrutide’s approval, or deeper GLP-1 price cuts, could move the stock well above or below these figures.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.