Prediction: Wall Street’s Next AI Favorite May Not Be Nvidia
Broadcom's AI revenue is growing faster than almost anyone on Wall Street expected, yet the stock sits nearly 30% below its 52-week high. Something about that disconnect deserves a closer look.


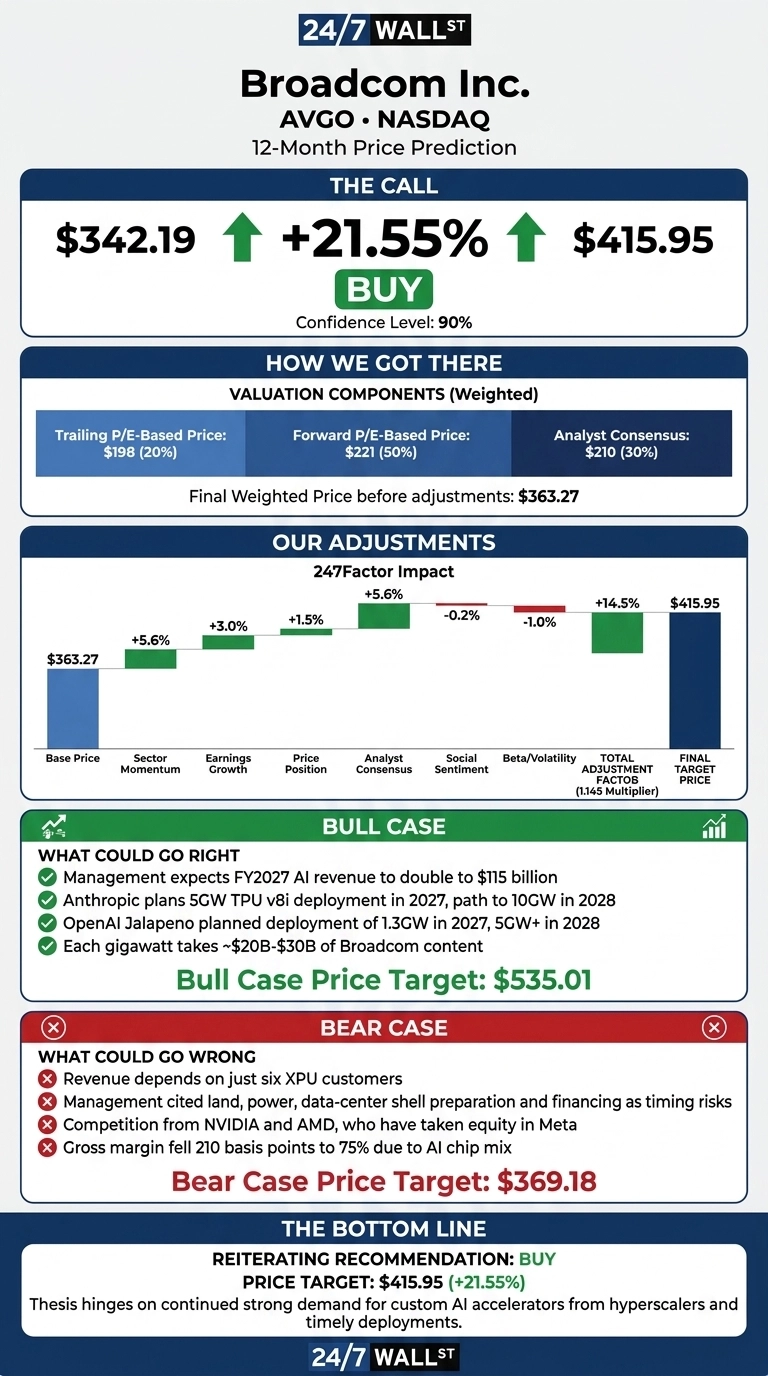
The 24/7 Wall St. price target for Broadcom (NASDAQ:AVGO | AVGO Price Prediction) is $415.95. This sits 21.55% above the $342.19 reference price, and the model rates the stock a buy.
| Metric | Value |
|---|---|
| Current Price | $342.19 |
| Price Target from 24/7 Wall St. | $415.95 |
| Upside/Downside | 21.55% |
| Recommendation | BUY |
| Confidence Level | 90% |

We hold this view with high confidence. Broadcom designs custom AI accelerators (XPUs) for Google (NASDAQ:GOOGL), Anthropic, OpenAI and Meta (NASDAQ:META).
Management expects fiscal 2027 AI revenue to about double to $115 billion. Even so, the stock has fallen behind the AI trade this year, and that gap is where our model finds upside.
Record AI Sales Meet a Stock Stuck Near Flat
Shares rose 1.32% to $346.86 Wednesday. They are up 3.74% over the past week, down 1.69% over the past month and up only 0.77% year to date. That leaves Broadcom 29.7% below its $493.28 52-week high and 20.0% above its $288.95 low.
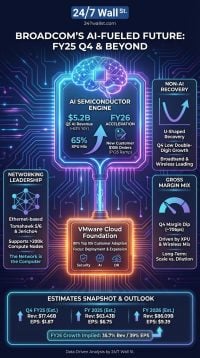
The business looks far stronger than the share price. Fiscal third-quarter revenue reached $29.59 billion, up 85.5% and ahead of the $29.44 billion estimate. EPS of $3.32 beat the $3.24 consensus.
AI semiconductor revenue grew 221% to $16.70 billion, and fourth-quarter guidance calls for $21.7 billion. On October 26, Bank of America, Blackstone, Citi and Morgan Stanley announced a $63 billion financing structure for AI compute capacity built around Broadcom.

Why Bulls See $535 Ahead
Management expects AI revenue of $230 billion in fiscal 2028 and EPS above $30. Anthropic plans to deploy 5 gigawatts of TPU version 8i in 2027, and Broadcom sees a path to another 10 gigawatts for Anthropic in 2028.
Each gigawatt takes about $20 billion to $30 billion of Broadcom content. The 7 Strong Buy, 40 Buy and 3 Hold ratings support a consensus target of $529.10. The bull case reaches $535.01.

What Could Stall the Custom Chip Story
Revenue depends on just six XPU customers. Management also named land, power, data-center shell preparation and financing as timing risks. Gross margin fell 210 basis points from the prior quarter to 75%, though that reflects a greater mix of AI chips, and operating margin hit a record 67.9%.
Barron’s also reports that NVIDIA (NASDAQ:NVDA) and Advanced Micro Devices (NASDAQ:AMD) have taken equity in Meta as they fight custom chips (Barron’s). The bear case still lands at $369.18.
Broadcom Trades Like NVIDIA but Grows Like a Challenger
| Company | Trailing P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Broadcom | 44x | 85.5% |
| NVIDIA | 44x | 105.85% |
| AMD | 211x | 50.11% |
NVIDIA belongs here because its GPUs are the chips Broadcom’s XPUs aim to replace. NVIDIA posted $96.22 billion in revenue last quarter and is up 16.63% year to date. Broadcom trades at the same trailing multiple but guides to faster AI growth, which makes its lag look like a valuation gap.
AMD competes for the same hyperscaler budgets, including a Meta deal for up to 6 gigawatts of GPUs. At 211x earnings, AMD makes our target look conservative.
Broadcom Earns Its Buy Rating
The 24/7 Wall St. price target of $415.95 comes with a buy rating and 90% confidence. Broadcom’s forward P/E of 19 against revenue that is nearly doubling tips the scale.
The thesis holds if Anthropic and OpenAI deployments stay on schedule. It weakens if power or financing delays drove gigawatts into later years.
The 24/7 Wall St. price target model projects where Broadcom could trade, assuming current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $363.58 |
| 2027 | $405.51 |
| 2028 | $471.37 |
| 2029 | $515.01 |
| 2030 | $575.57 |
The projections assume Broadcom keeps executing on custom silicon. The biggest swing factors are whether frontier labs keep financing gigawatt-scale buildouts and how fast new supply comes online. The power, cooling, and networking companies behind those data centers are the other half of this trade, and we rounded up seven of them in a free AI infrastructure report.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.