Alphabet Lost a Record $500 Billion in a Day. Is This the Buying Opportunity?
Alphabet just shed half a trillion dollars in market value after a single earnings report, but the numbers driving that collapse tell a more complicated story than Wall Street's reaction suggests.

Alphabet (NASDAQ:GOOG | GOOG Price Prediction) lost roughly $500 billion in market value after its third-quarter report. Shares are down 11.91% today because GAAP EPS of $2.12 missed the $2.9659 consensus.
Our proprietary model sets the 24/7 Wall St. price target at $407.60, which implies 44.96% upside. The model rates the stock a buy with moderately high confidence.
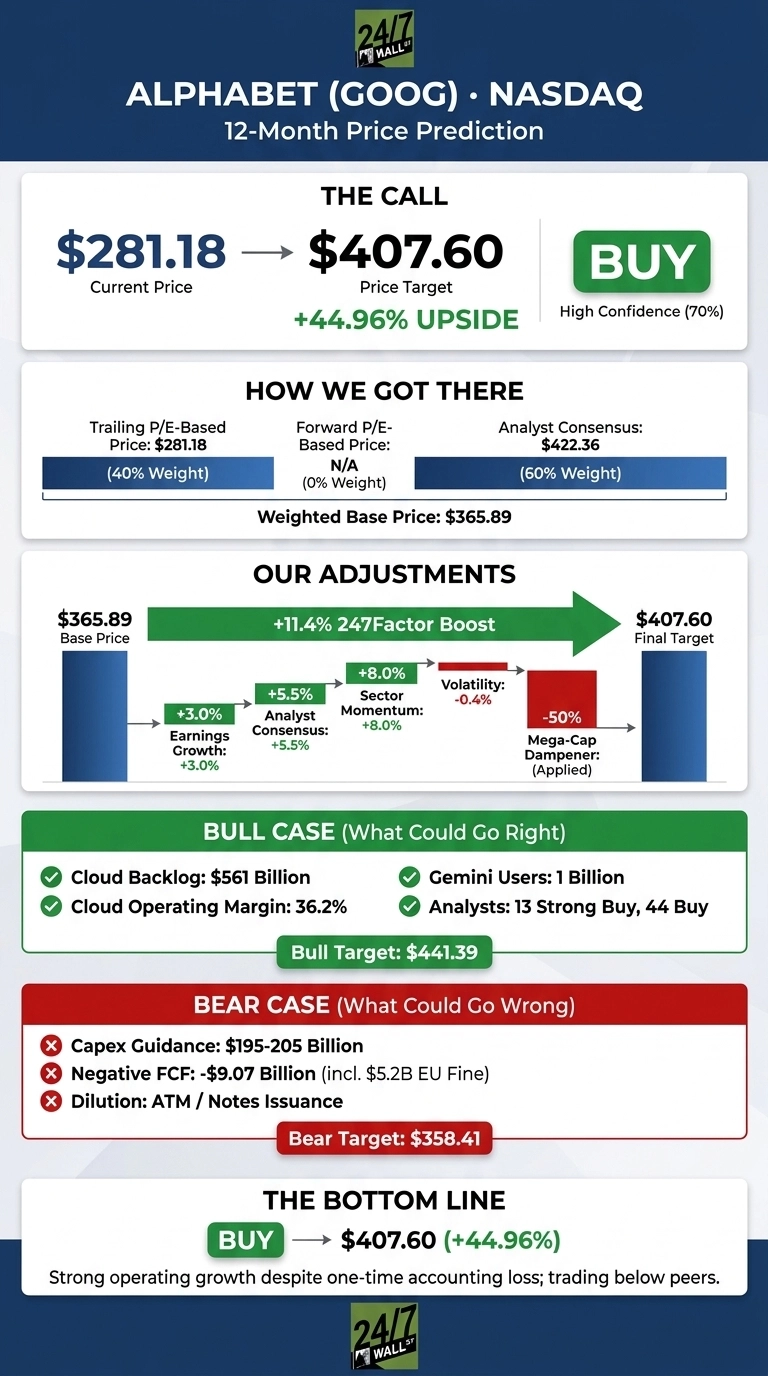

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $281.18 |
| 24/7 Wall St. Price Target | $407.60 |
| Upside/Downside | 44.96% |
| Model Rating | BUY |
| Confidence Level | 70% |
Most of the miss came from an accounting mark. A $8.7 billion loss on equity securities took $0.55 off diluted EPS. Operating income still rose 29.93% to $40.58 billion. The opportunity sits in that gap between a falling stock and rising operating profit.
An Investment Mark Ends a 12-Quarter Beat Streak
Shares are down 14.32% over the past week, 16.4% over the past month and 9.46% year to date. The 52-week range runs from $270.70 to $403.96, so the stock now trades near the bottom of it.
Revenue came in at $127.58 billion, slightly below the $127.83 billion estimate, and grew 24.6%. Google Cloud grew 103% to $30.71 billion. Free cash flow was -$9.07 billion because capex reached $51.36 billion.

Why Bulls See $441 Ahead
Google Cloud’s backlog reached $561 billion. Management expects just over 55% of it to become revenue within 24 months. Cloud operating margin rose to 36.2% from 23.7%.
The Gemini app now has 1 billion users, and management expects more TPU system revenue in 2027. Among analysts, 13 rate the stock a strong buy, 44 a buy and none a sell. Our bull scenario reaches $441.39.

Capex and Dilution Are the Risks Worth Watching
Capex guidance for 2026 is $195 to $205 billion, and management expects spending to increase significantly in 2027. To help fund it, Alphabet issued $28.7 billion in notes and sold $4.3 billion of Class A and $8.1 billion of Class C shares.
AI Mode queries also monetize at lower rates for now. As a counterpoint, third-quarter free cash flow included a $5.2 billion payment for an EU fine, and Alphabet holds $265.1 billion in cash and marketable securities. Our bear scenario still reaches $358.41.
Alphabet Trades Well Below Its Hyperscaler Peers
Microsoft (NASDAQ:MSFT) is Alphabet’s closest cloud rival. Azure grew 48% last quarter, well below Google Cloud’s growth rate, yet Microsoft’s earnings multiple is more than twice Alphabet’s.
Meta Platforms (NASDAQ:META) competes with Alphabet for ad budgets and also posted a one-time EPS miss: a $9.89 billion legal charge pushed EPS to $3.83. Even so, Meta trades at a higher multiple than Alphabet.
| Company | P/E | Latest Quarter Revenue Growth | Operating Margin |
|---|---|---|---|
| Alphabet | 13x | 24.6% | 32.06% |
| Microsoft | 29x | 18.8% | 46.78% |
| Meta | 22x | 26.1% | 41.44% |
Alphabet grows revenue faster than Microsoft and nearly as fast as Meta, but it trades at the lowest multiple of the three. Against that peer group, our 24/7 Wall St. price target looks reasonable, and arguably conservative.
Why Our Model Still Rates Alphabet a Buy
The 24/7 Wall St. price target of $407.60 carries a buy rating at 70% confidence. What tips the scale is that operating income kept growing while reported earnings fell.
The bull case strengthens if Cloud keeps turning its backlog into revenue and ads in AI Mode scale. It weakens if capex keeps climbing while revenue growth slows. On balance, I think the selloff priced in an accounting loss and left Alphabet’s actual business performance undervalued.

Alphabet Price Prediction 2026-2030
The longer-term projections below extend our model and assume current growth trends and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $298.56 |
| 2027 | $402.73 |
| 2028 | $521.29 |
| 2029 | $635.95 |
| 2030 | $706.96 |
These projections assume Alphabet continues with its current approach. TPU adoption could push results well above them, while weak returns on AI spending could pull results well below.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.